


The Returns Catch Up
September added to August’s gains and opened a clear gap over equities. All three trend benchmarks gained between 3.03 and 4.26 percent, while the S&P 500 Total Return Index slipped 0.35 percent. The TTU Trend Barometer read 55, 59, 45 and 52 across the four weekly closes of the month. August had climbed in a straight line from 30 to 55, and September did not repeat that. In the second week the reading moved into the favourable band for the first time since the late July low. It fell 14 points the following week and recovered half of that fall in the fourth. The returns took a steadier path. The SG Trend Index gained in every week of the month and gave back a little only in the final three sessions. Its largest weekly gain came in the week the fewest markets rose.
The ranking of the three benchmarks changed again. The SG Trend Index led at plus 4.26 percent, followed by the TTU Trend Following Index at plus 3.77 percent and BTOP50 at plus 3.03 percent. The spread from first to third widened to 123 basis points, from 92 in August. The order of the two pure trend benchmarks has now flipped in each of the past two months. The SG Trend Index moved from third in August to first, and the TTU TF Index slipped to second. BTOP50, the broadest of the three constructions, finished last. That ordering fits a month in which the payoff came from established trends in a limited number of sectors. The two pure trend benchmarks appear to have captured more of it than the broader BTOP50 mix.
The weekly path shows how the month unfolded. The first week left the Barometer unchanged at 55, and the SG Trend Index opened September at plus 0.59 percent. In the second week the reading rose to 59 even though only 14 of the 49 contracts in the weekly market review finished higher. The index added 2.20 percentage points, its strongest week of the month, as much of that week’s persistence ran downward. The third week reversed the relationship between breadth and the Barometer. Eighteen contracts rose, the reading fell 14 points to 45, and the index added only 0.44 percentage points. In the last full week, to 25 September, the reading recovered to 52 and the index added 1.24 percentage points to reach plus 4.47 percent. It gave back 0.21 percentage points in the three sessions to month end and finished at plus 4.26 percent. The Barometer held at 52 through the week that straddled the month end.
The benchmark results for September were as follows:
- TTU Trend Following Index: +3.77 percent for September (trailing 12 months +20.08 percent)
- SG Trend Index: +4.26 percent for September (trailing 12 months +21.33 percent)
- BTOP50 Index: +3.03 percent for September (trailing 12 months +17.80 percent)
- S&P 500 Total Return: -0.35 percent for September (trailing 12 months +15.74 percent)
Trailing twelve-month returns eased across the board despite the month’s gains. September 2025 has now left the window, and it was a stronger month for each benchmark than the September that replaced it. The TTU TF Index moved to 20.08 percent from 22.23 percent and the SG Trend Index to 21.33 percent from 23.04 percent. BTOP50 moved to 17.80 percent from 17.96 percent. The S&P 500 Total Return Index fell furthest, to 15.74 percent from 20.38 percent. Year to date, the SG Trend Index stands at 15.80 percent, BTOP50 at 14.81 percent and the TTU TF Index at 14.16 percent, against 12.75 percent for the S&P 500 Total Return Index. A month ago all three trend benchmarks trailed the S&P 500 on the year. All three now lead it, by between 141 and 305 basis points. The TTU TF Index still trails the SG Trend Index by 164 basis points and BTOP50 by 65.
August showed returns lagging the Barometer as it rose. In September the returns caught up, and then they began to move with the reading rather than behind it. Week by week, the Barometer held, rose 4, fell 14 and rose 7. The SG Trend Index gained 0.59, 2.20, 0.44 and 1.24 percentage points month to date over the same weeks. The return figure closed the gap in the first fortnight. After that its weekly gain shrank when the reading fell and recovered when the reading recovered. The best week came when only 14 of 49 contracts rose, because many of that week’s persistent moves were declines, and a trend follower can profit from a falling market as readily as from a rising one. The cycle that began in January remains intact, and September closes with the Barometer at 52, three points below the favourable band.
August 2026 Trend Index Performance
September was a second consecutive gain for the trend benchmarks, and this time equities did not come with them. The SG Trend Index gained 4.26 percent, the TTU Trend Following Index 3.77 percent and BTOP50 3.03 percent, while the S&P 500 Total Return Index lost 0.35 percent. August had drawn its return from a changing set of sources. In September the largest persistent moves came from a few established trends: the petroleum advance in the first half of the month, declines in Bonds and the precious metals for most of it, and the upper reaches of Grains late in the month. The Barometer was less orderly than in August. It rose to 59, fell to 45 and recovered to 52, yet the SG Trend Index improved at each of the four weekly closes. The index gained most in the weeks when established moves extended, and least in the week when the largest moves on the board ran against existing trends.
September opened with one sector doing most of the travelling. In the week to 4 September, Energy gained 5.95 percent with all six contracts higher. WTI rose 9.69 percent, Brent 9.28 percent, Heating Oil 6.85 percent and Gasoline RBOB 5.39 percent. The crude pair reclaimed the ground it had surrendered late in August and pushed above the levels that had contained it through July and August. Breadth across the 49 contracts in the weekly market review barely moved, from 21 to 24 higher, but the average move across the board rose from 0.43 to 2.24 percent. Elsewhere, the quieter moves extended trends already in place. Bonds fell across all four maturities, with the declines growing with maturity, to or near the lowest levels on their charts. Metals fell for a second week with four of five contracts lower, Coffee extended a decline running since spring and the VIX fell for a seventh week. Grains paused after their late August surge, with Wheat giving back 6.38 percent of its 12.12 percent gain, and the currency basket split four and four. The Barometer held at 55 and the SG Trend Index opened the month at plus 0.59 percent. The week’s largest move took the petroleum complex out of its summer range, so it was still young as a trend.
The second and third weeks showed the difference between extension and interruption. In the week to 11 September only 14 of 49 contracts rose, yet the SG Trend Index posted its best week of the month. The petroleum complex extended, with WTI up 9.37 percent to near 100, Heating Oil up 9.23 percent and Brent up 8.65 percent. Bonds fell across all four maturities again, with the 30 Year Bond down 1.78 percent and the sector average close to four times the prior week’s. Metals fell on all five contracts for a third week, led by Palladium at minus 5.70 percent. Orange Juice fell 6.98 percent back to the lows of a decline running most of the year, and Coffee fell for a third week. The cattle pair moved against their declines and Natural Gas fell 4.84 percent, but these were exceptions. The Barometer rose to 59 and the SG Trend Index added 2.20 percentage points to reach plus 2.79 percent month to date.
The week to 18 September broke that coherence. Breadth improved to 18 of 49 contracts higher, but the Barometer fell 14 points to 45. Metals rose on four of five contracts, with Silver up 3.01 percent inside its decline. The 30 Year Bond rose while the shorter maturities fell, and the Nasdaq 100 and Nikkei 225 gained while the other five equity indices fell. Soft Commodities fell 5.19 percent on all six contracts. Cocoa, Cotton and Sugar fell against their summer advances, with Cocoa down 10.64 percent, while Coffee, Orange Juice and Lumber extended their declines. Energy gained for a third week as leadership rotated to Gasoline RBOB, up 6.66 percent, and Oats rose 7.26 percent to the highest level on its chart. Six of the ten largest moves on the board ran against the prevailing trend in their market. The SG Trend Index added only 0.44 percentage points to reach plus 3.23 percent.
The last full week of the month looked like rotation, but most of the turnover was the previous week’s interruptions reversing. In the week to 25 September six of ten sectors changed sign, with Soft Commodities and Meats moving from weakest to strongest. Silver, Palladium, Gold and Platinum resumed the declines they have traced since February. Bonds fell across all four maturities to new lows, again with the declines growing with maturity. Grains gained 1.61 percent with six of eight contracts higher. Rough Rice rose 6.04 percent and Oats 3.38 percent, and Soybean Meal reached the top of its chart. The Nasdaq 100 set a new high, and the US Dollar Index led the currency basket higher for a second week. Against that, Energy turned sharply lower. Heating Oil fell 7.72 percent, Gasoline RBOB 4.04 percent and WTI 3.82 percent from the upper end of their charts. Orange Juice, Natural Gas and Feeder Cattle also produced large gains inside declines that remain intact. The Barometer recovered 7 points to 52, and the SG Trend Index added 1.24 percentage points to reach plus 4.47 percent at the last full weekly close. It gave back 0.21 percentage points in the three sessions to month end and closed September at plus 4.26 percent.
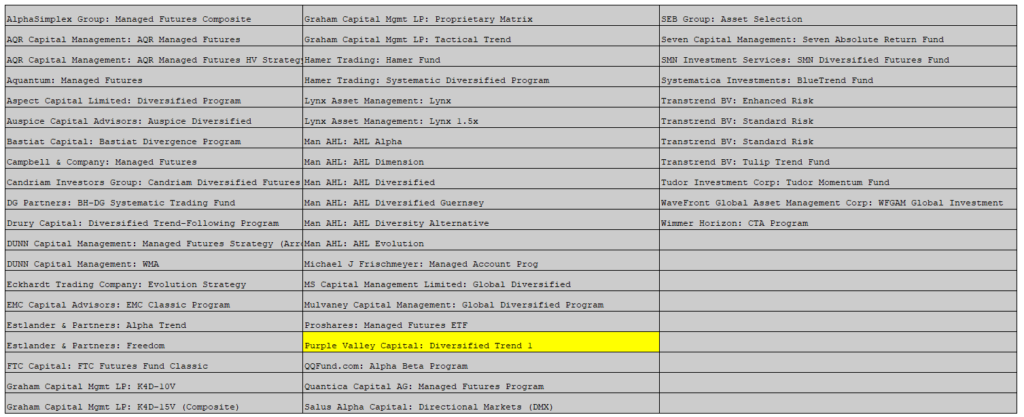
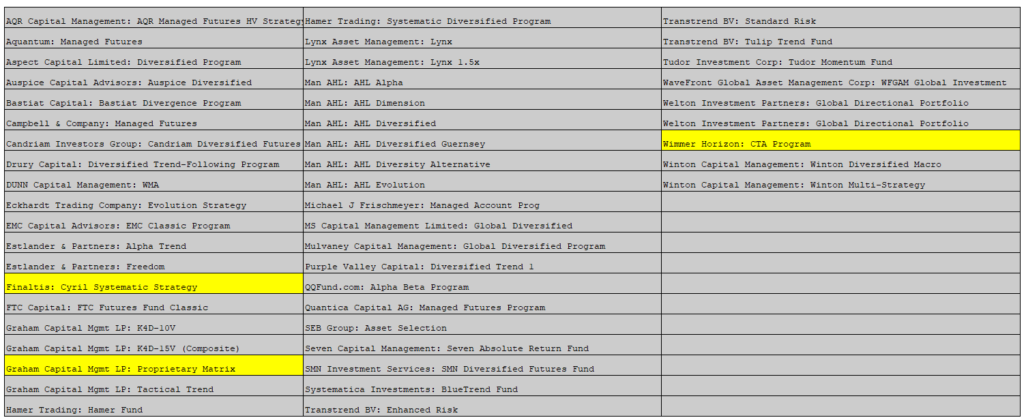
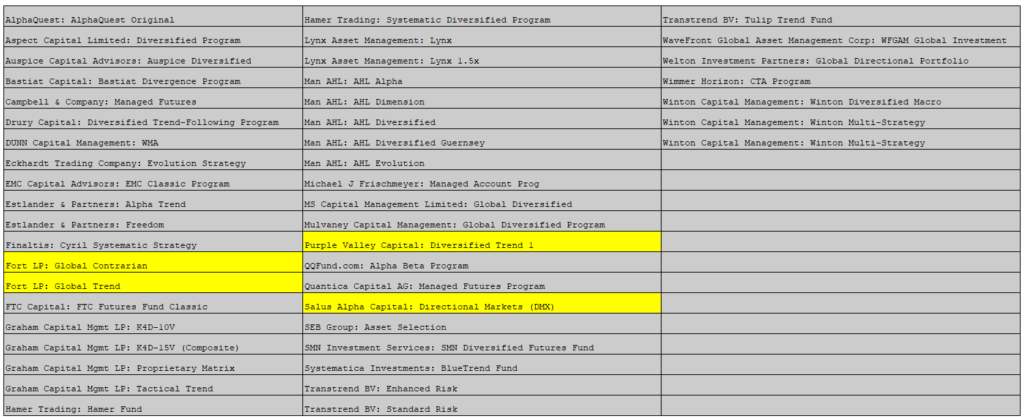
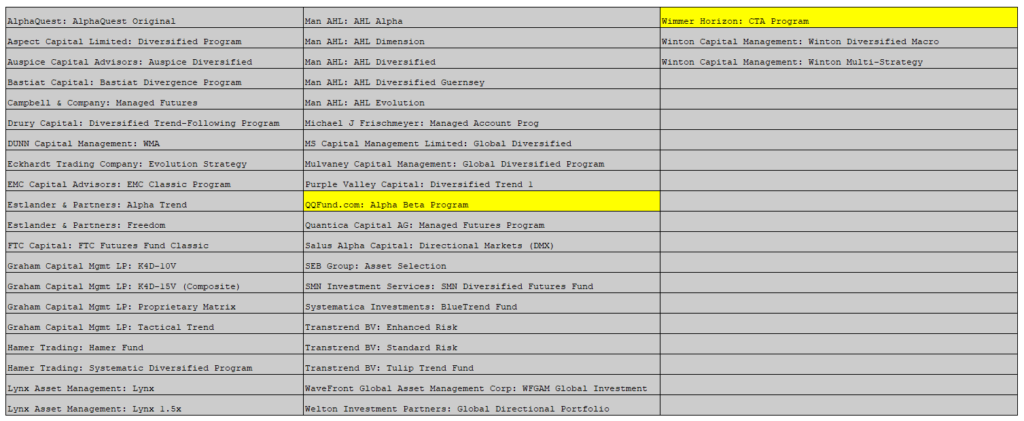
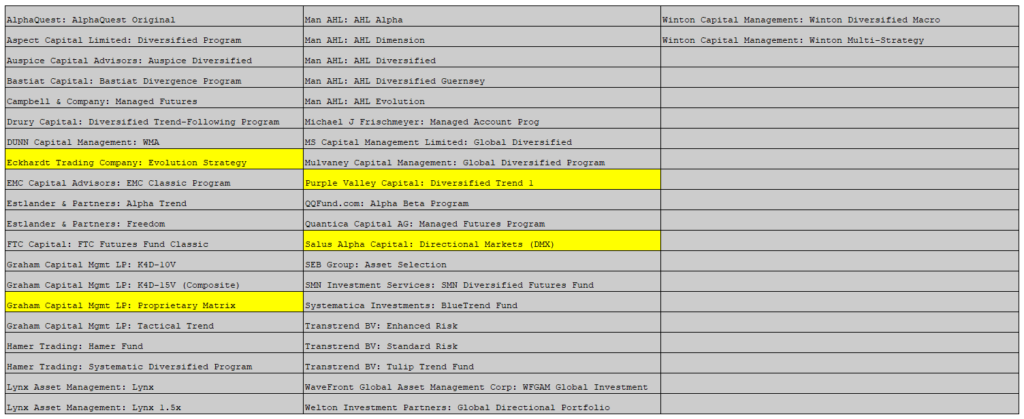
At 30 September 2026, the TTU Trend Following Index contained 52 active programs, unchanged from August. Forty-five programs had reported by the cut-off, leaving seven outstanding, as highlighted in the table below. They are Eckhardt Trading Company: Evolution Strategy, Finaltis: Cyril Systematic Strategy, Purple Valley Capital: Diversified Trend 1, QQFund.com: Alpha Beta Program, Salus Alpha Capital: Directional Markets (DMX), Seven Capital Management: Seven Absolute Return Fund and Winton Capital Management: Winton Multi-Strategy. Three of the seven, Finaltis, Purple Valley and Seven Capital, were also outstanding at the August cut-off. Reporting coverage has slipped from August, when four programs were outstanding, but remains ahead of July, when nine were. August’s return has since been revised to 3.86 percent from the provisional 3.63 percent as late reporters came in. The September return of 3.77 percent may also change as the remaining seven programs report, and with 45 of 52 in, the scope for revision is wider than it was a month ago. The construction methodology is unchanged and continues to require a fully verified 15-year track record.
September’s relationship with equities was divergence. The S&P 500 Total Return Index lost 0.35 percent, and the trend benchmarks gained between 338 and 461 basis points more. The S&P 500 contract was unchanged in the first week, lost 0.80 percent in the second and 0.19 percent in the third, and gained 1.18 percent in the fourth. The equity indices fell for three consecutive weeks as a sector, uniformly so in the week to 11 September. None of the seven contracts gave up the ground that would put its spring advance in question, and the Nasdaq 100 finished the month at new highs. For portfolios carrying long equity exposure, that pullback was more likely a modest cost than a source of return. The long-run correlation between the TTU TF Index and the S&P 500 remains minus 0.09. The month’s largest established moves were outside equities: Energy in the first fortnight, Bonds and the precious metals for most of the month, and Grains in the last full week.
SG Trend Index
The SG Trend Index is designed to track the 10 largest trend following CTAs of the Managed Futures space.
Criteria for inclusion in the Index, as determined by Société Générale, are as follows:
- Must trade primarily futures (including FX forwards);
- Must be broadly diversified across asset classes;
- Must be an industry recognized trend follower;
- Must exhibit significant correlation to trend following peers;
- Must be open to new investment; and
- Must report returns on a daily basis (net of fees).
The index currently is:
- Equally weighted;
- Calculated in base currency;
- Has an inception date of 1st January 2000;
- Rebalanced annually on 1st January; and
- Reconstituted annually on 1st January based on eligibility criteria.
There was a slight modification to the Index from January 2013 to the present. Previously, the Programs needed to be a constituent of the SG CTA Index, and the 10 largest Managers was not a requirement.
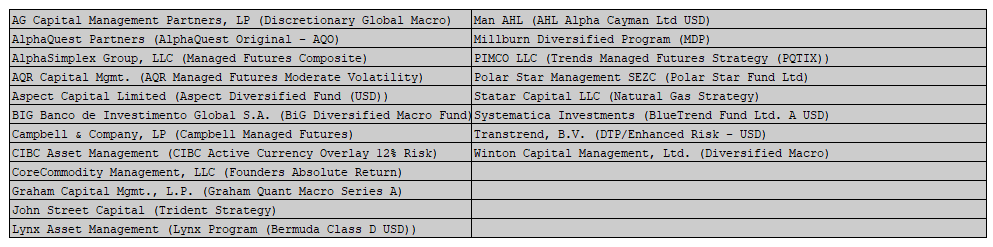
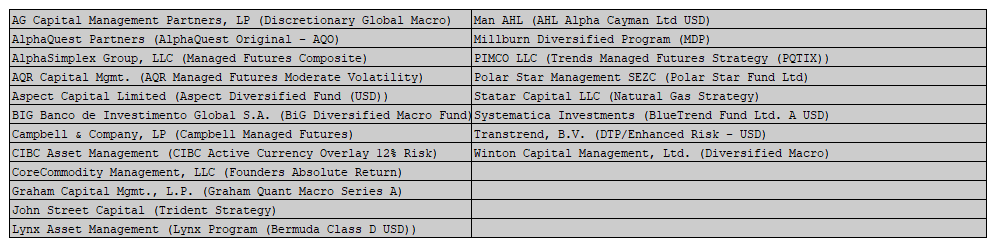
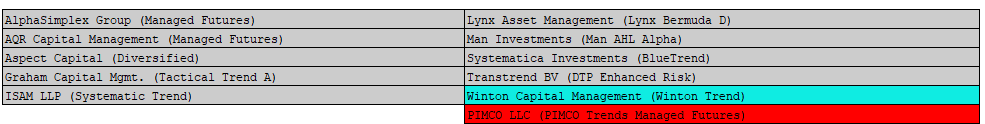
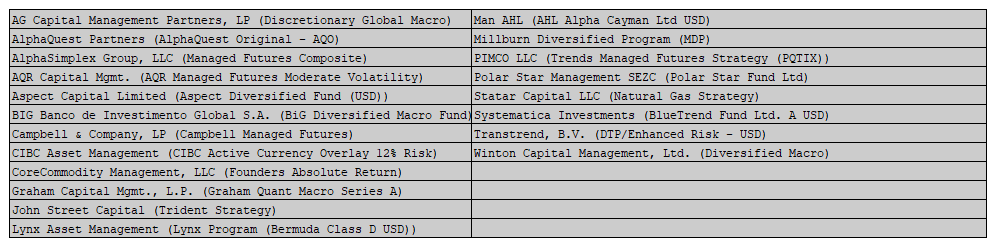
For the 2026 year, following the annual rebalance of the Index, we say goodbye to the Systematica Investments (BlueTrend) Program and welcome back the PIMCO LLC (PIMCO Trends Managed Futures) Program. The listing of the 10 eligible programs in the Index for 2026 is as follows:

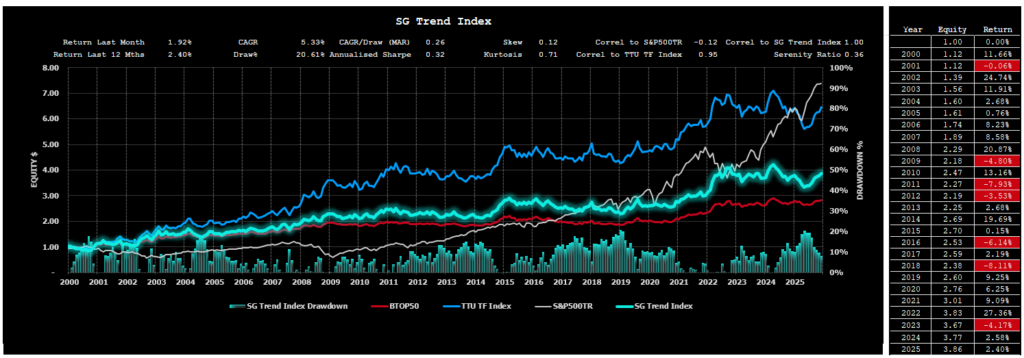
The SG Trend Index, which tracks the ten largest institutional trend-following CTAs, gained 4.26 percent in September, a second consecutive positive month. It finished first among the three trend benchmarks, 49 basis points ahead of the TTU Trend Following Index at 3.77 percent and 123 basis points ahead of the BTOP50 at 3.03 percent. In August it had finished third. The trailing twelve-month return eased to 21.33 percent from 23.04 percent despite the strong monthly result, because the September 2025 observation leaving the window was stronger still. The year-to-date figure climbed to 15.80 percent from 11.07 percent. That moves the index to the head of the field, 99 basis points ahead of the BTOP50, 164 ahead of the TTU TF Index and 305 ahead of the S&P 500 Total Return Index.
The month’s shape differed from August’s. August opened with a loss and depended on a 1.28 percentage point gain in its final session. September gained in every week and gave back 0.21 percentage points only in the three sessions after the last full weekly close. Month to date, the index stood at plus 0.59, 2.79, 3.23 and 4.47 percent at the four weekly closes. The second and fourth weeks, when established trends extended across several sectors at once, supplied 3.44 of the 4.47 percentage points gained by 25 September. The third week, when many of those trends were interrupted, added only 0.44.
The long-term characteristics of the SG Trend Index improved again on the month. Since inception it has delivered a historical CAGR of 5.75 percent with a maximum drawdown of 20.61 percent, reflecting both the durability and the inherent cyclicality of large-scale systematic programs. The CAGR rose from 5.60 percent at the close of August, its second consecutive monthly improvement. The maximum drawdown was unchanged for a fourth consecutive month. These managers benefit most when sustained trends persist in the direction of their positioning, and September offered sustained trends in Energy, Bonds and the precious metals.
Since its launch in 2000, the SG Trend Index has maintained its role as a core institutional benchmark for trend-following performance. Over the long run it sits between the higher-returning TTU Trend Following Index and the broader BTOP50 Index, capturing the central tendency of the industry’s largest managers. In September it led the monthly ordering. The two AUM-based benchmarks, which had finished a single basis point apart in August, separated by 123 basis points. Its high correlation of 0.95 with the TTU TF Index reinforces its usefulness as a barometer of collective institutional behaviour, even as its construction produces more moderated long-run returns relative to smaller or more aggressive trend-following composites.
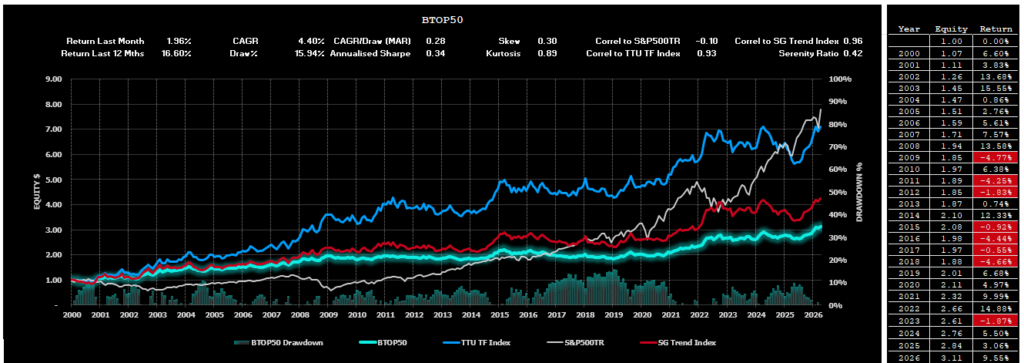
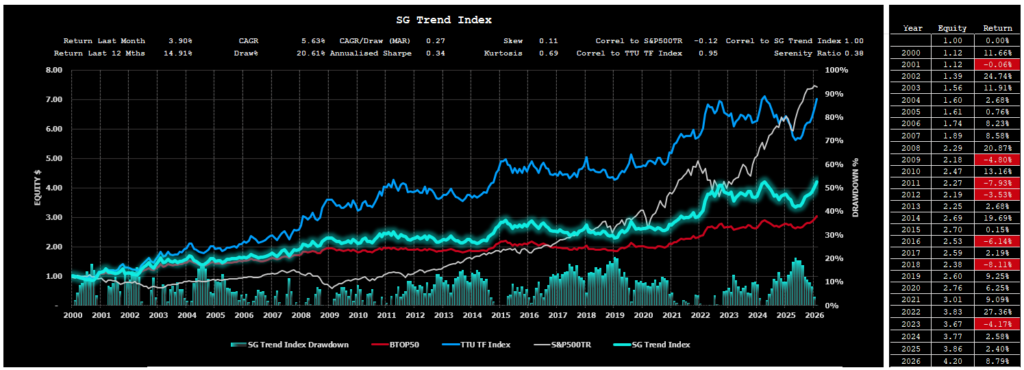
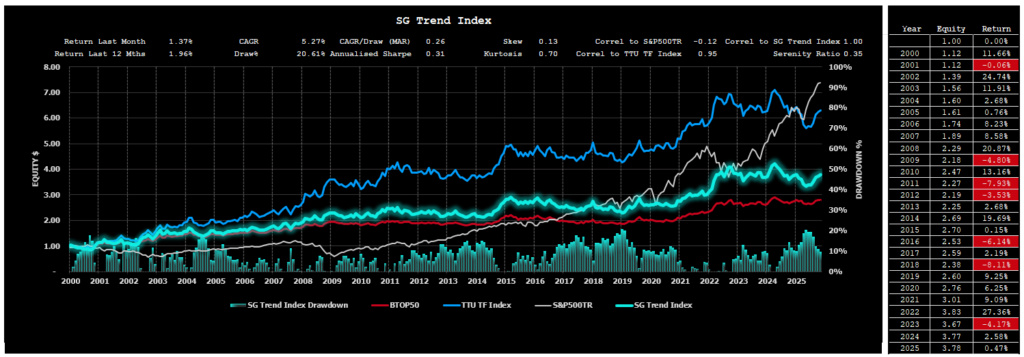
The performance of the SG Trend Index since 1st January 2000 to the end of last month is seen in the following chart:

You will notice how the SG Trend Index is highly correlated with the BTOP50 Index and the TTU TF Index and uncorrelated with the S&P500TR Index.
Despite the high correlation between the various trend following Indexes, the long-term performance of these three Trend Following Indexes in terms of CAGR is different. The SG Trend Index plots between the BTOP50 Index and the TTU TF Index.
BTOP 50 Index
The BTOP50 Index seeks to replicate the overall composition of the managed futures industry with regards to trading style and overall market exposure. Unlike the SG Trend Index and the TTU TF Index, the BTOP50 is not strictly a trend following Index and is more broadly representative of the entire managed futures segment of which a dominant style is trend following. We like to think of the BTOP 50 as a ‘quasi trend following Index' as opposed to a pure trend following Index.
Like the SG Trend Index, the BTOP50 Index is designed to track the performance of the largest Programs by AUM, however the Programs included may not be all Trend Following Programs.
Criteria for inclusion in the Index as determined by BarclayHedge is as follows:
- Must be a Program represented in the Barclay CTA Universe;
- In each Calendar year, the Programs selected must in aggregate be no less than 50% of the investable assets of the Barclay CTA Universe;
- The Programs must be open for investment;
- The Manager must be willing to provide Barclay Hedge with daily return performance;
- The Program must have at least two years of trading activity; and
- The Program's advisor must have at least three years of operating history.
The index currently is:
- Equally weighted;
- Rebalanced annually on 1st January; and
- Reconstituted annually on 1st January based on eligibility criteria.
The TTU TF Index is highly correlated with both BTOP50 and the SG Trend Index, yet its long-term performance has been materially stronger. The key distinction is the requirement that every constituent program brings a long, verified track record to the index.
AUM can tell us a great deal about market acceptance, but it tells us far less about durability. Popularity and long-term performance are not the same thing. By selecting on demonstrated longevity rather than asset size, the TTU construction asks a different question: which programs have actually survived and delivered across multiple market regimes?
That construction also gives us a useful view of ensemble diversification. As more independently implemented, long-tenured trend programs are combined, idiosyncratic manager outcomes are diluted. Historically, the result has been a stronger compound return alongside shallower portfolio drawdowns. There is nothing magical about it. It is diversification doing what diversification is supposed to do.
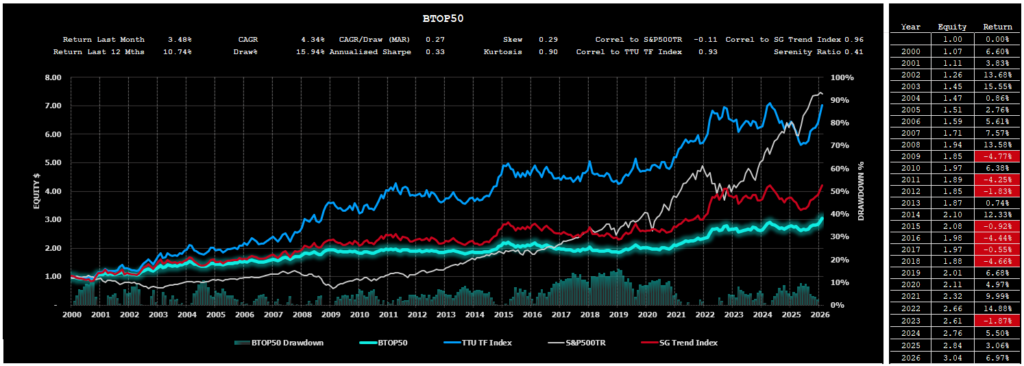
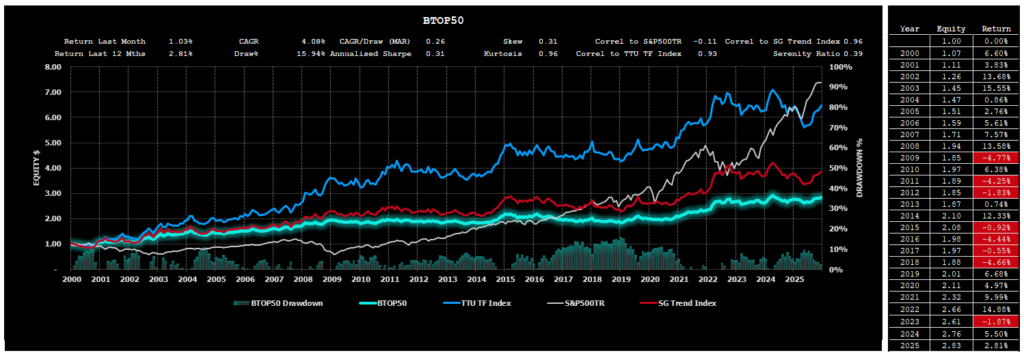
The BTOP50 Index gained 3.03 percent in September, a second consecutive positive month. It finished third among the three trend benchmarks, 74 basis points behind the TTU Trend Following Index and 123 basis points behind the SG Trend Index. In August it had finished second. Over the trailing twelve months the index now stands at 17.80 percent, down slightly from 17.96 percent in August, because the September 2025 observation leaving the window was marginally stronger than the month that replaced it. The year-to-date figure stands at 14.81 percent. A month ago the broad managed futures composite led the three trend benchmarks on a year-to-date basis. It now sits second among them, 99 basis points behind the SG Trend Index, and remains 65 basis points ahead of the TTU TF Index and 206 ahead of the S&P 500 Total Return Index.
The long-term profile of the BTOP50 improved again on the month. Since inception it has produced a historical CAGR of 4.51 percent with a maximum drawdown of 15.94 percent, reinforcing its reputation for stability and drawdown moderation. The CAGR rose from 4.40 percent at the close of August, its second consecutive monthly improvement, as another gain well above the long-term compounding rate lifted the figure. The maximum drawdown was unchanged for a fourth consecutive month.
September extended the pattern that August began. In July the BTOP50’s broad construction worked as protection, because the index committed less to the trends that broke and so gave back less. In August and September the trends in place persisted, and the same broad construction gained less from them. In August the shortfall was against the TTU TF Index alone, and the BTOP50 matched the SG Trend Index almost exactly. In September it trailed both pure trend benchmarks. The month’s largest persistent moves were in Energy, Bonds and the precious metals, and the two benchmarks built entirely from trend-following programs gained more. Across the three months, the index lost least when persistence failed and lagged the TTU TF Index when persistence held. That pattern is consistent with a broad managed futures composite, and with the lowest long-run return of the three.
The index’s high correlation of 0.96 with the SG Trend Index and 0.93 with the TTU TF Index confirms that its performance remains closely aligned with its trend-following peers, even as its broader mandate produces more moderated long-term returns. The correlation of minus 0.10 with the S&P 500 Total Return Index remains an important structural feature of the index over the long run. In September the two moved apart. The S&P 500 lost 0.35 percent while the BTOP50 gained 3.03 percent, a difference of 338 basis points. That follows August, when the two rose together, and July, when they moved independently. Three consecutive months have now shown each of the relationships a correlation near zero allows.
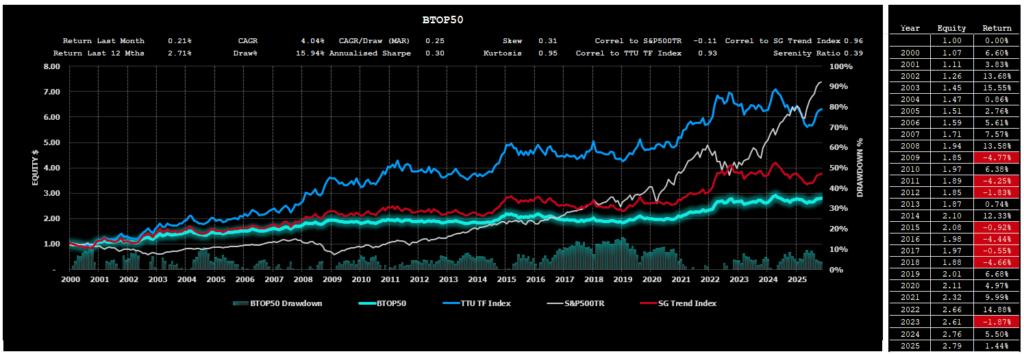
The performance of the BTOP 50 Index since 1st January 2000 to the end of last month is seen in the following chart:

The BTOP 50 Index is highly correlated with the trend following Indexes of the SG Trend Index and the TTU TF Index, however its long-term performance is the lowest of the 3 Trend Following Indexes. While there is a significant representation of Trend Following Programs within the Index, the non-trend following Programs contribute to this diluted long-term performance.
TTU TF Index
The TTU TF Index has been developed by Top Traders Unplugged to provide a performance measure of the trend-following programs with a long-term track record.
At TTU, we recognize the importance of a robust trading approach to these uncertain markets and feel that AUM is not a good robustness measure when it comes to assessing performance of the trend-following industry. It is our strong opinion that the ultimate selection measure to apply in constituting a Trend Following Index is not AUM or a proxy risk metric such as the Sharpe, Sortino, MAR ratio, Ulcer Index or Serenity ratio. The superior metric to assess long-term performance is the long-term validated track record itself.
We have therefore developed a different method for constructing our TTU TF Index.
The criteria for inclusion into the TTU TF Index are as follows:
- Monthly performance results need to be captured in the Nilsson Hedge CTA database;
- Must be geographically diversified across asset classes;
- Must be fully systematic in nature using quantitative rules for entry and exit;
- Must possess at least a 15-year unbroken track record to the current reporting month;
- Must adopt trend following as their dominant investment strategy;
- Are currently active programs; and
- Must report performance monthly (net of fees).
The Index:
- Is Equally weighted;
- Is Rebalanced monthly;
- Is Reconstituted monthly;
- Has an inception date of 1st January 2000
As of 30 September 2026, the TTU Trend Following Index is composed of 52 active programs, each with a long-term, fully verified performance record. The roster is unchanged from the close of August, when it rose by one from 51. That addition was the first increase since the reconstitution that trimmed the index from 54 in May. The reconstitution interrupted a steady expansion from 43 programs at the close of 2025 through 47 in January, 49 in February, 51 in April and 54 in May. The count then held at 51 through June and July before August’s addition. The construction methodology is unchanged, continuing to require a fully verified 15-year track record. The composite retains the broad, long-tenured cross-section of systematic trend-following behaviour that defines it, with nine more programs than it carried at the close of 2025. The monthly index return reflects the equal-weighted average performance of all programs reporting for the period.
For September, 45 of the 52 programs submitted performance data by the reporting cut-off, with seven programs yet to report as highlighted in the table below. Three of the seven, Finaltis, Purple Valley Capital and Seven Capital Management, were also outstanding at the August cut-off. The other four, Eckhardt Trading Company, QQFund.com, Salus Alpha Capital and Winton Capital Management, were not outstanding in August. Coverage has slipped from August, when 48 of 52 programs had reported, and sits below the 49 recorded in each of May and June. It remains ahead of July, when 42 of 51 had reported. With seven programs outstanding against four a month earlier, the September equal-weighted return is drawn from a narrower base than August’s, and it is more likely to be revised as the remaining programs report.
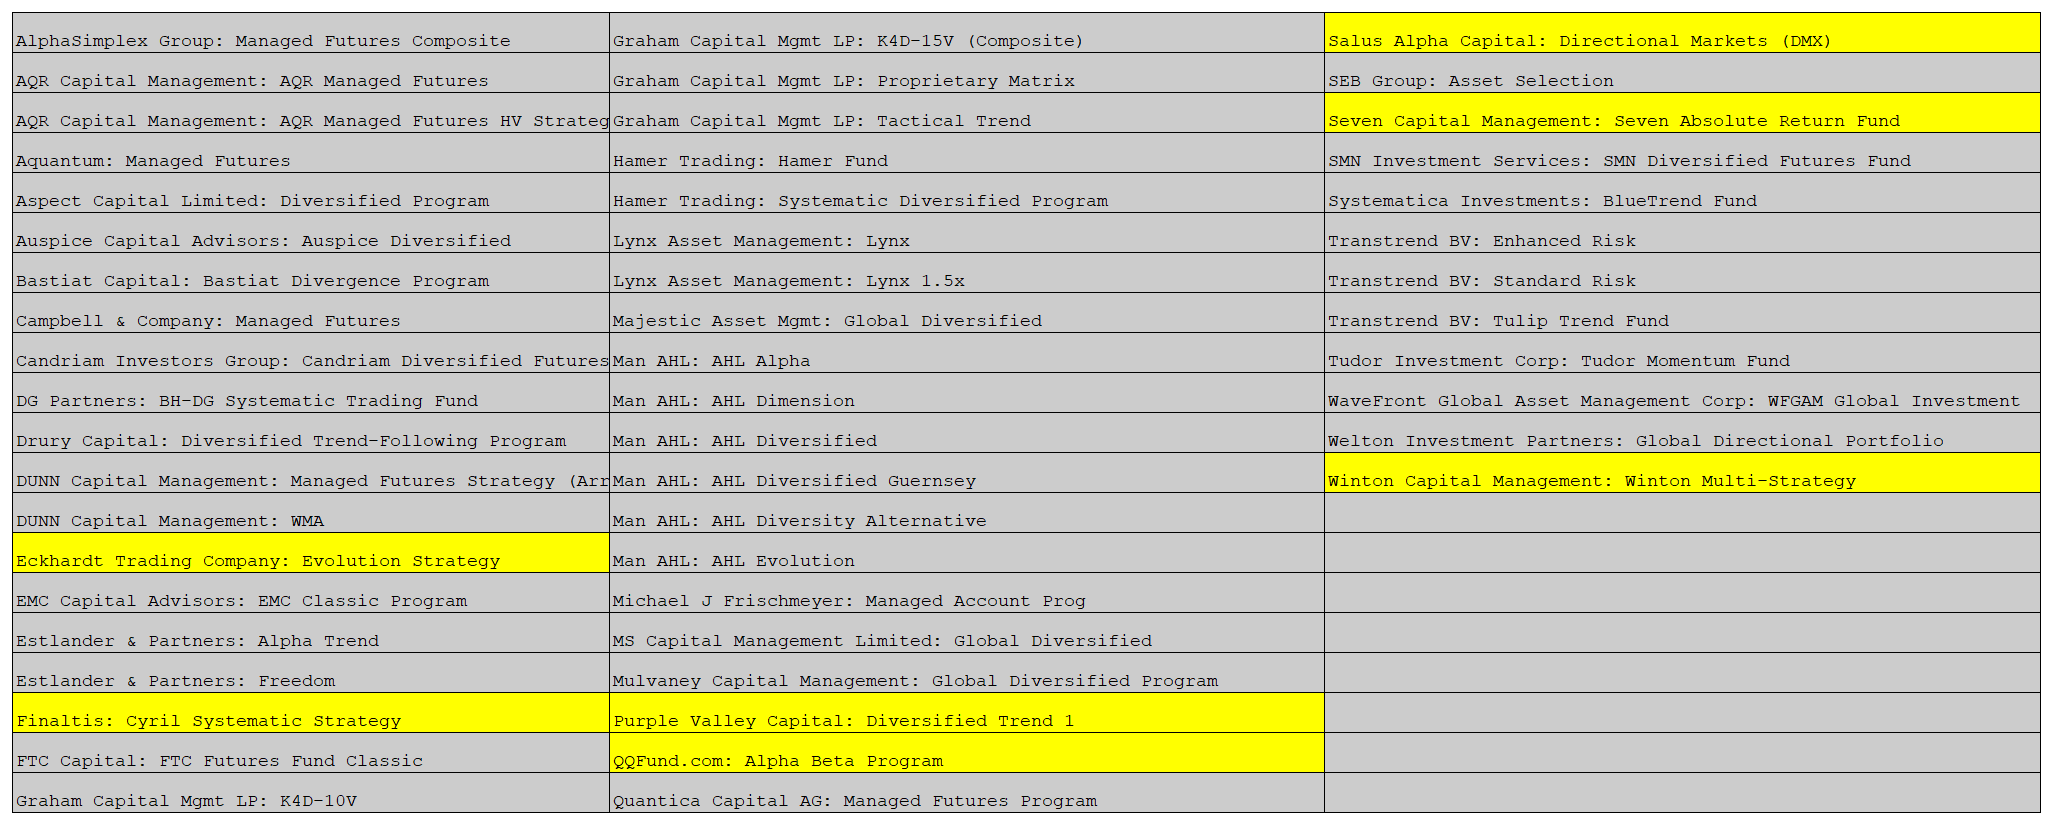
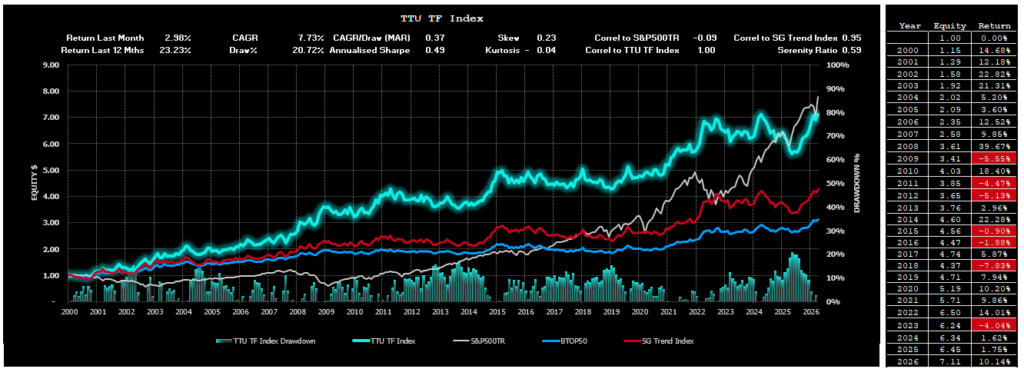
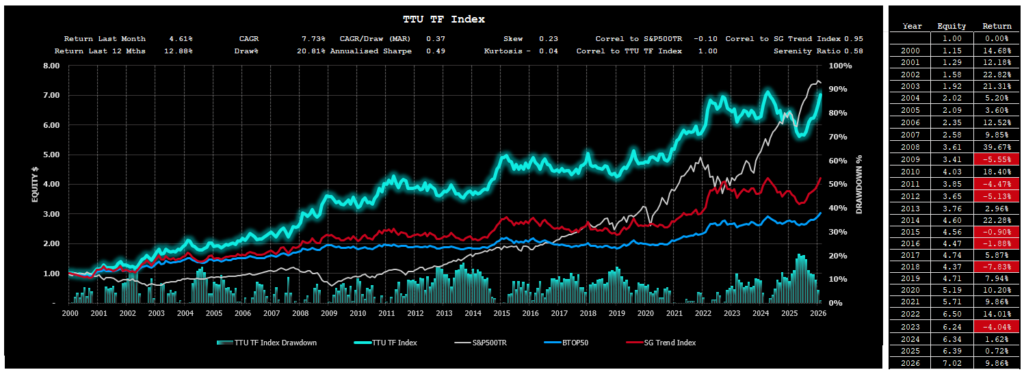
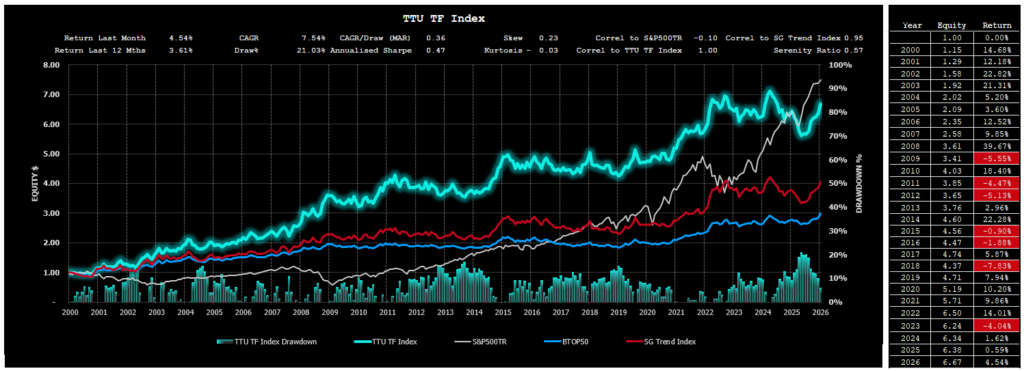
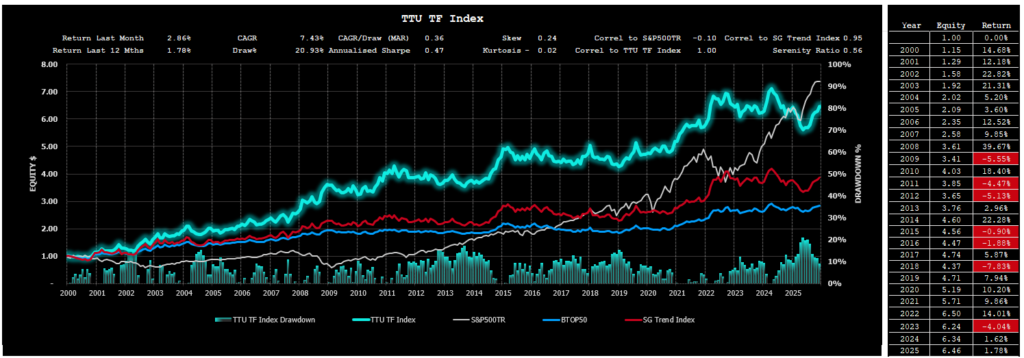
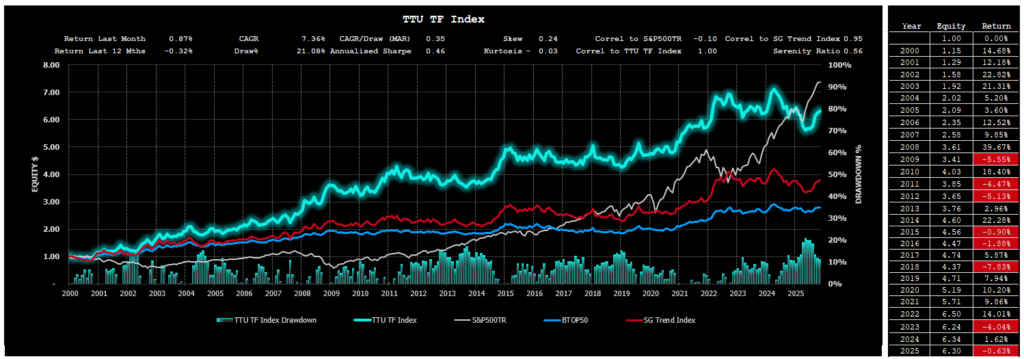
The performance of the TTU TF Index from 1st January 2000 to the end of last month is as follows:

Now you might be intrigued by the performance result of the TTU TF Index. While it is highly correlated with the BTOP 50 Index and the SG Trend Index, we can see that long term performance of the TTU TF Index clearly outstrips alternative Index measures.
We believe the main contributor to this outperformance is the requirement for any participating Program in the Index to have a long-term track record. Using AUM as a criterion for inclusion is not necessarily a useful selection criterion. While AUM reflects ‘market appeal’, it does not imply that this ‘market appeal’ is strongly correlated with ‘long term performance’.
Our process of Index construction also gives us an insight into how a diversified ensemble of trend following Programs with a long-term track record behaves as we increase the number of Programs in the Index. Historically, diversifying into a larger ensemble of Trend Following Programs with a long-term track record has improved the Index result, with a higher CAGR and shallower drawdowns.
This is the same diversification principle trend followers apply within their own programs. Greater diversification has historically improved both the maximum drawdown and the CAGR of an ensemble, which is why we seek maximum market and system diversification within individual programs. The TTU TF Index takes this diversification one step further and diversifies across many different TF Programs, with the aim of delivering a stronger return and drawdown profile.
TTU TF Index Performance
The TTU Trend Following Index, composed exclusively of long-tenured systematic trend programs, gained 3.77 percent in September, a second consecutive positive month. It finished second among the three trend benchmarks, 49 basis points behind the SG Trend Index at 4.26 percent and 74 ahead of the BTOP50 at 3.03 percent. In August it had led the three trend benchmarks. Over the trailing twelve months the index stands at 20.08 percent, down from 22.23 percent in August, because the September 2026 gain replaced a stronger September 2025 result in the rolling window. August’s return has been revised to 3.86 percent from the provisional 3.63 percent, which moves the year-to-date figure through August to 10.01 percent. From that revised base the year-to-date figure rose to 14.16 percent. The index is now 141 basis points ahead of the S&P 500 Total Return Index on the year, but it still trails the SG Trend Index at 15.80 percent and the BTOP50 at 14.81 percent.
The index’s position in September is consistent with how it is built. It is an equal-weighted average of long-tenured programs, so no single manager dominates the result. In July its full commitment to trend following made it the benchmark most exposed to the trends that broke. In August the same commitment left it best placed among the three to benefit from the trends that held. In September it gained more than the broader BTOP50 but less than the SG Trend Index, whose ten large managers finished 49 basis points ahead. The September figure is also provisional. It is drawn from 45 of 52 programs, and the last two months show that late reporters can move the result in either direction. July was revised down by 35 basis points and August up by 23.
The long-term profile of the TTU TF Index improved again on the month. Since its inception in 2000, the index has delivered a CAGR of 7.76 percent with a maximum drawdown of 20.72 percent. The CAGR rose from 7.62 percent at the close of August, its second consecutive monthly improvement, as another gain well above the long-term compounding rate lifted the figure. The maximum drawdown was unchanged for a fourth consecutive month. August and September together have more than recovered the 3.78 percent the index lost across June and July. We attribute these characteristics to the construction methodology, which prioritises the durability of verified track records over scale, popularity, or short-term risk statistics.
The TTU TF Index remains closely aligned with the institutional trend benchmarks, with correlations of 0.95 to the SG Trend Index and 0.93 to BTOP50. The important difference is in the long-run outcome. Its track-record-based construction has produced the strongest compound return of the three while retaining the broad behavioural signature of systematic trend following. The roster stands at 52 programs, unchanged on the month and nine more than at the end of 2025, with 45 reporting for September. Across the last three months the index has moved from the weakest of the three benchmarks to the strongest and then to second. The 20.08 percent trailing twelve-month return is more useful context than any single month’s ranking.
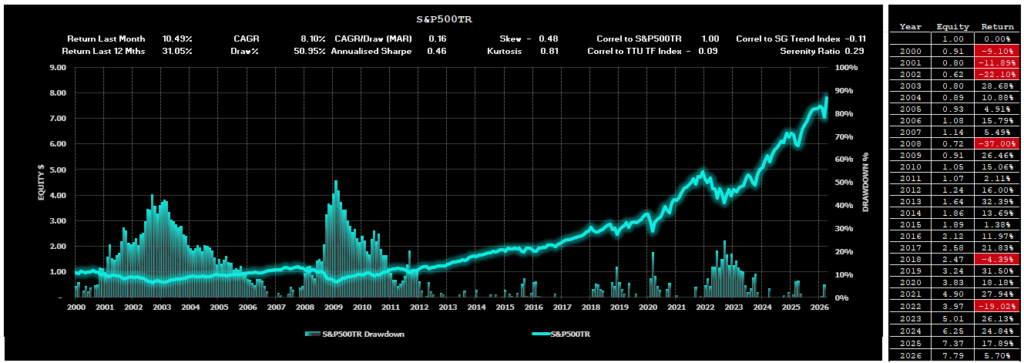
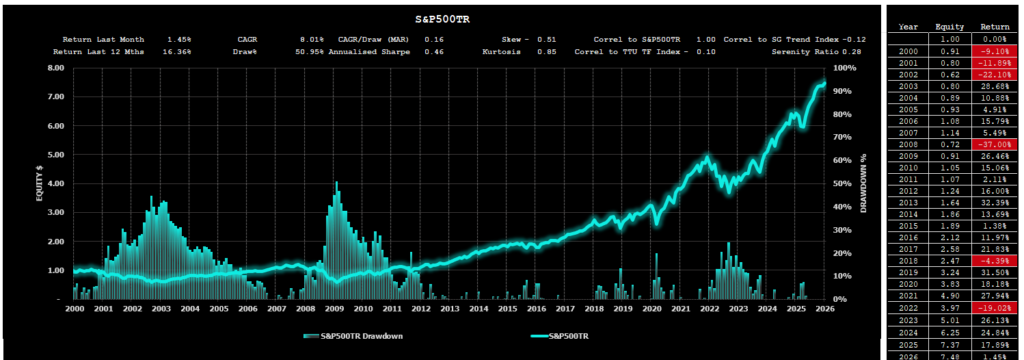
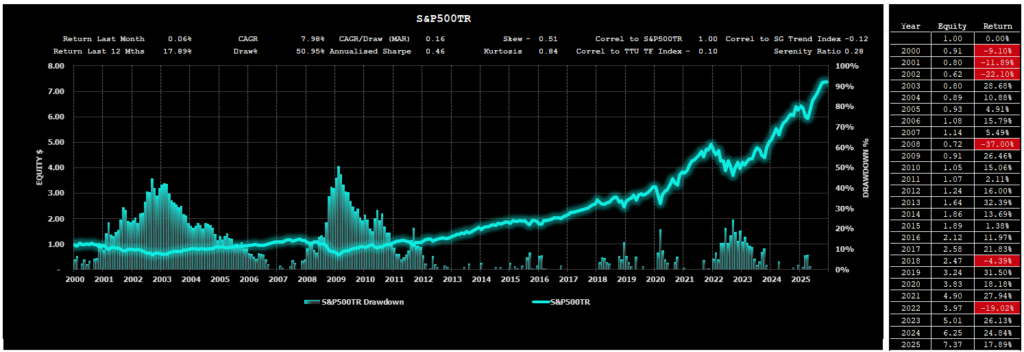
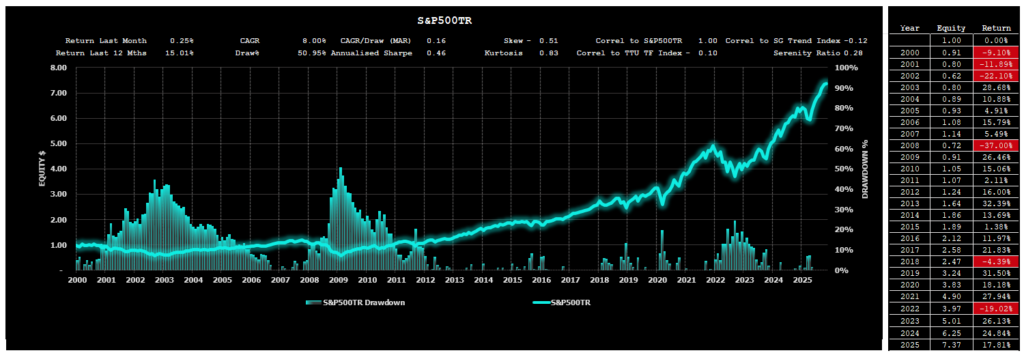
For comparison, the S&P 500 Total Return Index lost 0.35 percent in September and returned 15.74 percent over the trailing twelve months. Since 2000 it has compounded at 8.23 percent, but its maximum drawdown of 50.95 percent is far deeper than that of the trend benchmarks. In June equities and the TTU TF Index fell together. In July equities finished almost unchanged while trend following eased, and in August both rose. In September the two moved apart, with the TTU TF Index ahead by 412 basis points. Four months have produced four different relationships, consistent with a long-run correlation between the two indices of minus 0.09. Their return engines are different, and that independence is what allows trend following to play such a useful role inside a broader portfolio.

TTU Trend Barometer
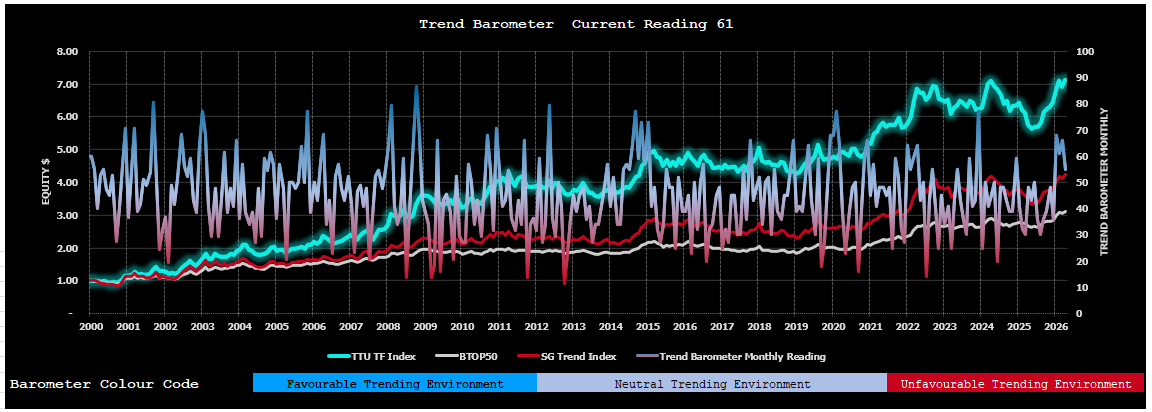
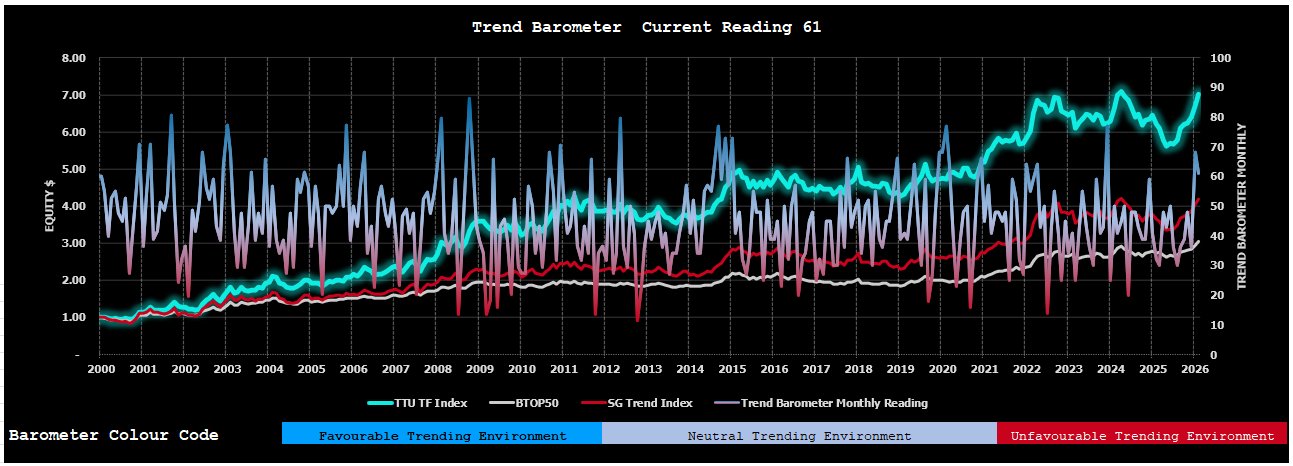
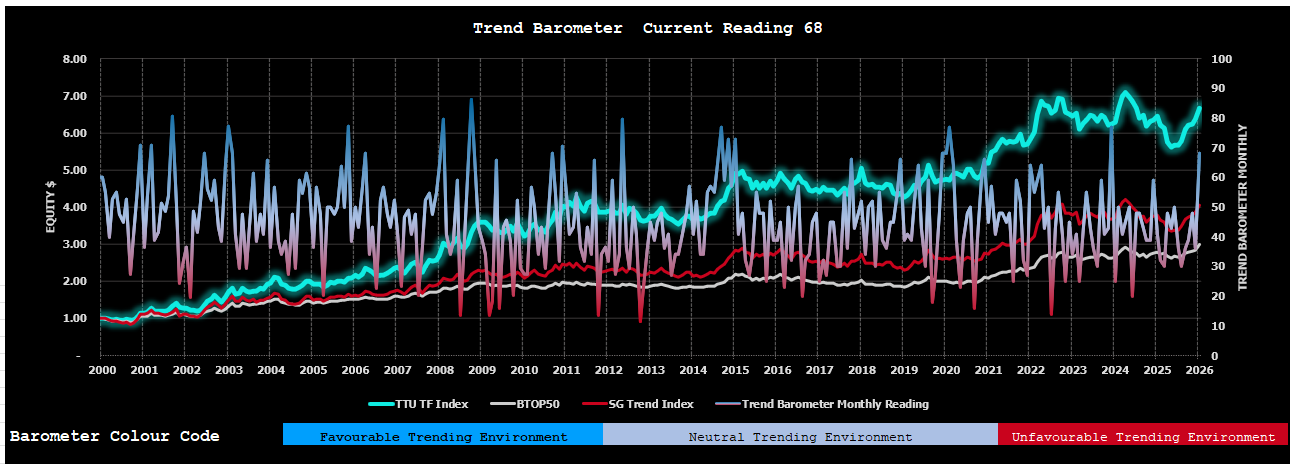
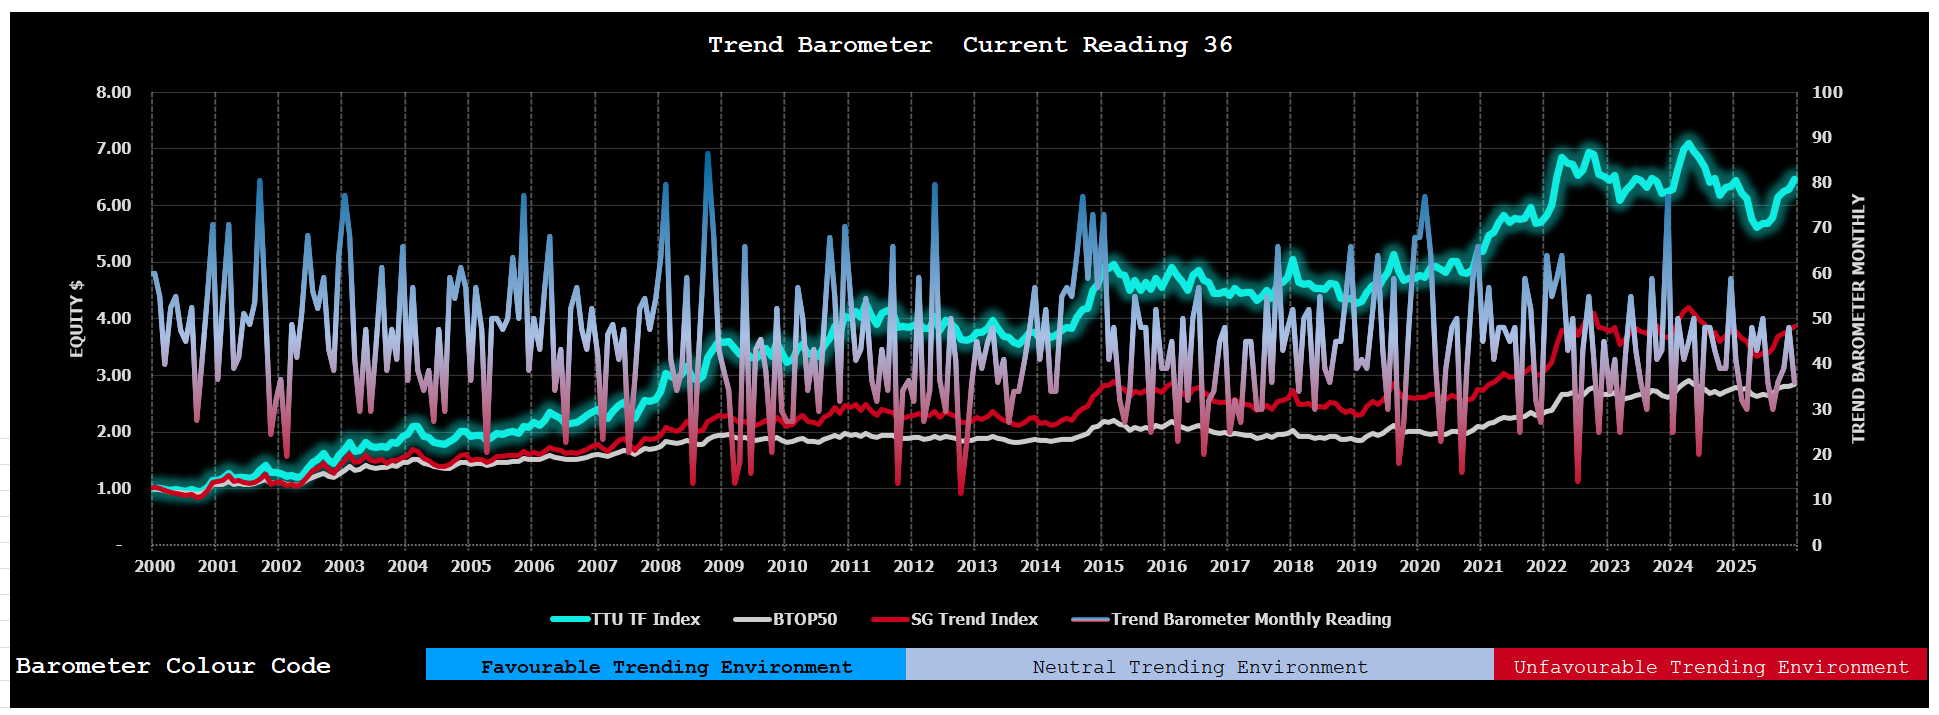
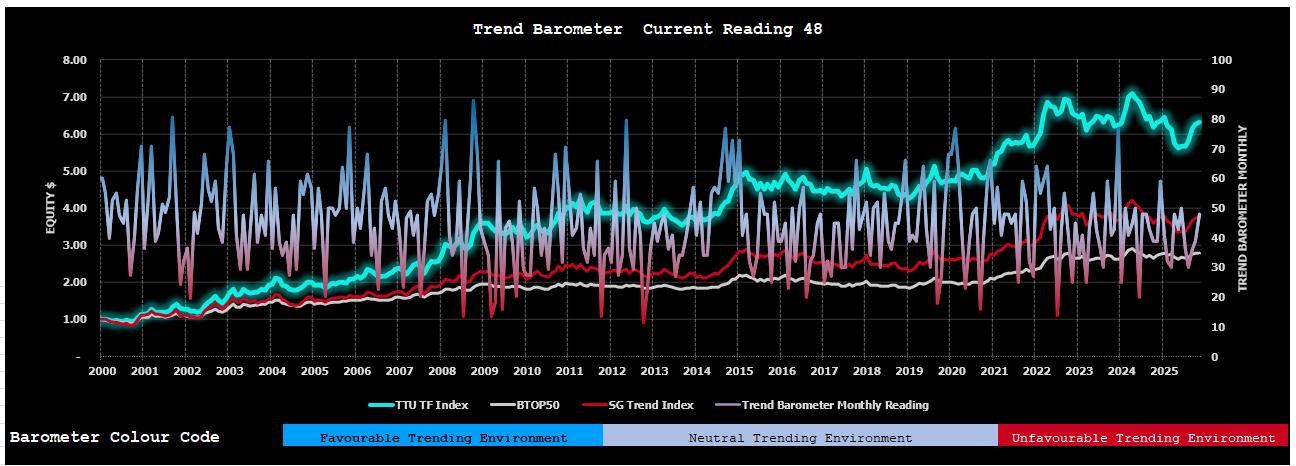
The TTU Trend Barometer closed September at 52, inside the Neutral band and three points below the boundary with a favourable regime. That is three points lower than August’s closing reading of 55 and 22 points above July’s low of 30. August rose in every week. September did not repeat that: the reading held, rose four points, fell 14 and recovered seven. In the second week it moved into the favourable band for the first time since the late July low, reaching 59. It gave back that gain and more the following week, falling to 45, then recovered half the fall by the last full weekly close, on 25 September. The reading held at 52 through the week that straddled the month end.
The Barometer measures the persistence of price trends across 44 global futures markets. The breadth figures quoted in this section come from the separate 49-contract weekly market review, so they describe a related but not identical universe. The first week left the reading at 55, its first week without a rise since the late July low, although the 10-day rate of change strengthened to “Rising Moderately” from “Rising Weakly.” Breadth barely moved, from 21 to 24 contracts higher, but the average move across the board rose more than fivefold, from 0.43 to 2.24 percent. Persistence strengthened in Energy, Bonds and Metals and weakened in Grains, the currency basket and the equity indices, and the reading held.
The second week added four points to 59, the highest reading since the late July low, in the week the fewest markets rose. Only 14 of 49 contracts finished higher, while the average move held at 2.16 percent. That combination is consistent with many of the 35 declines running in the direction of trends already in place. Sixteen contracts across Bonds, Metals and the equity indices moved as blocs, the most coherent configuration of the month, while the petroleum complex extended its advance. A count of markets rising said little about the trend environment that week.
The third week produced the largest fall of the month, 14 points to 45, with the rate of change at “Falling Moderately.” Breadth improved to 18 contracts higher, but the blocs of the previous week broke up, and only nine contracts, in Soft Commodities and Meats, moved in a single direction. Six of the ten largest moves on the board ran against the prevailing trend in their market. The week to 25 September recovered seven points to 52, with the rate of change at “Neutral.” Most of the previous week’s interruptions reversed, as the precious metals and Bonds resumed their declines and several Grains contracts reached new highs. Energy was the main exception, with Heating Oil down 7.72 percent from the highest level on its chart.
Read as a sequence, 55, 59, 45 and 52 is less orderly than August. Breadth moved against the reading in two of the four weeks, and the reading held while breadth edged up in the first. Contracts higher ran 24, 14, 18 and 24. The Barometer rose to its peak as breadth narrowed, fell sharply as breadth recovered, and only in the final week moved with it. The month also showed the Barometer and realised CTA returns moving closer together. In August the returns lagged the reading on the way up. In September the SG Trend Index added 0.59 percentage points in the week the reading held and 2.20 in the week it rose four points. It added only 0.44 when the reading fell 14 points and 1.24 when it recovered seven. The Barometer counts persistence without asking which way it runs. September’s best week came when much of that persistence was falling in markets where trend followers were likely to be short. The Barometer enters October at 52, 12 points above the Neutral floor and three below the favourable boundary, with its 10-day rate of change at “Neutral.” Level and momentum are both mixed after a month that touched 59 and 45. The clearest trends are in Bonds, where all four maturities sit at the lowest levels on their charts, and in the precious metals, which have resumed the declines running since February. Grains have several contracts at or near chart highs, the Nasdaq 100 is at a new high and the US Dollar Index is close to the top of its range. The picture elsewhere is less settled. The petroleum contracts have pulled back sharply from the highs they reached mid-month, while Orange Juice, Natural Gas and the cattle contracts produced large gains inside declines that remain intact. Copper is holding near its high as the other metals fall, and Bitcoin remains inside the decline from above 120,000.

The Trend Barometer is a proprietary tool we use at TTU to assess the trend strength of a diversified portfolio consisting of 44 markets across all sectors. We firstly subdivide the trend strength of each market of a hypothetical diverse portfolio into five ranges from strong up, medium up, neutral, medium down and strong down. We then aggregate these results into a single portfolio number which we use to describe the overall trend strength across a hypothetical Program portfolio.
We then arbitrarily divide this percentage range into 3 where a value of 0-30 is considered a very unfavourable market regime for trend following programs, a range between 30 to 55 is a somewhat neutral environment for Trend Following Programs (but not an environment where you could expect consistent performance) and values more than 55 are considered to be a favourable regime for trend following programs, where they should see good performance.
Aside from the occasional dispersed readings when compared to overall trend following performance, this method is surprisingly powerful in describing CTA monthly performance and can be used to connect market trading environments to resultant manager performance.
The Macro Environment
For a blow-by-blow macro wrap for the month, we recommend you listen to our weekly systematic investor series by clicking on the links below. It is also worthwhile listening to our past catalogue, as it provides you with an understanding of how these markets can shape the emotions of a trader and why it is therefore essential that trend followers adopt systematic rules-based processes to keep these emotions in check.
You can find all of our weekly conversations by clicking this link.
Top 10 Lists
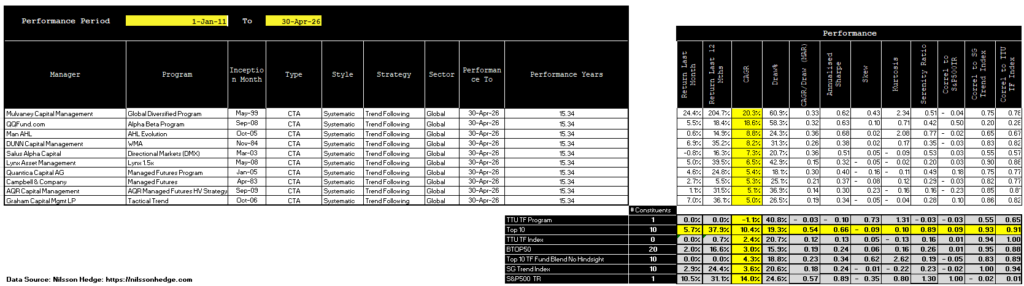
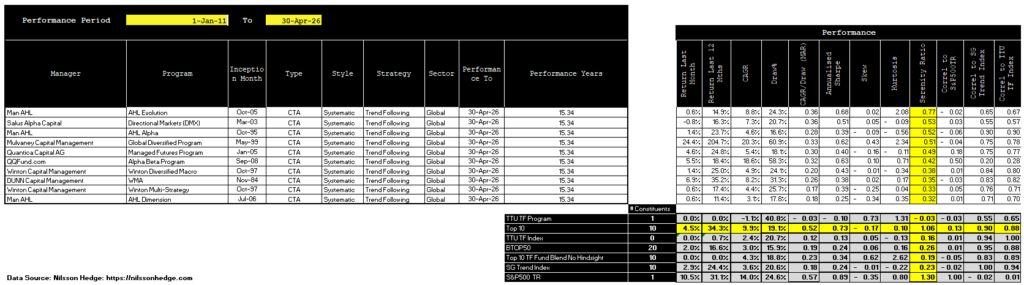
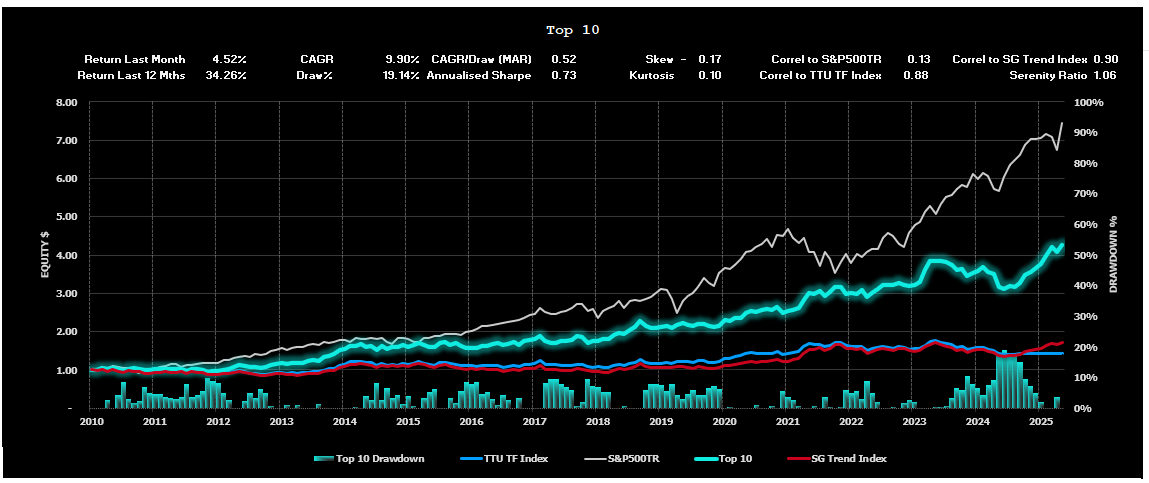
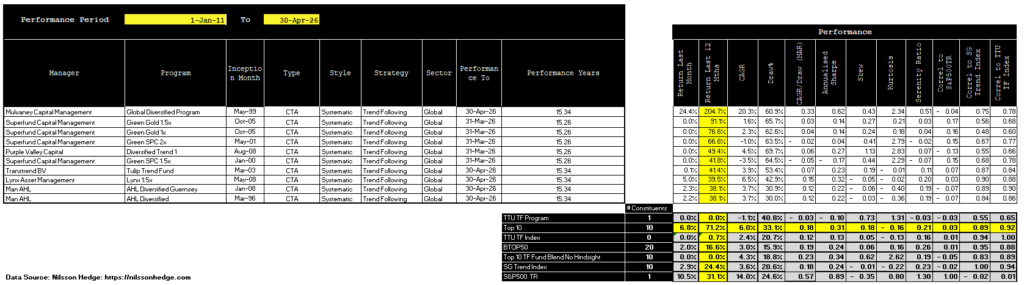
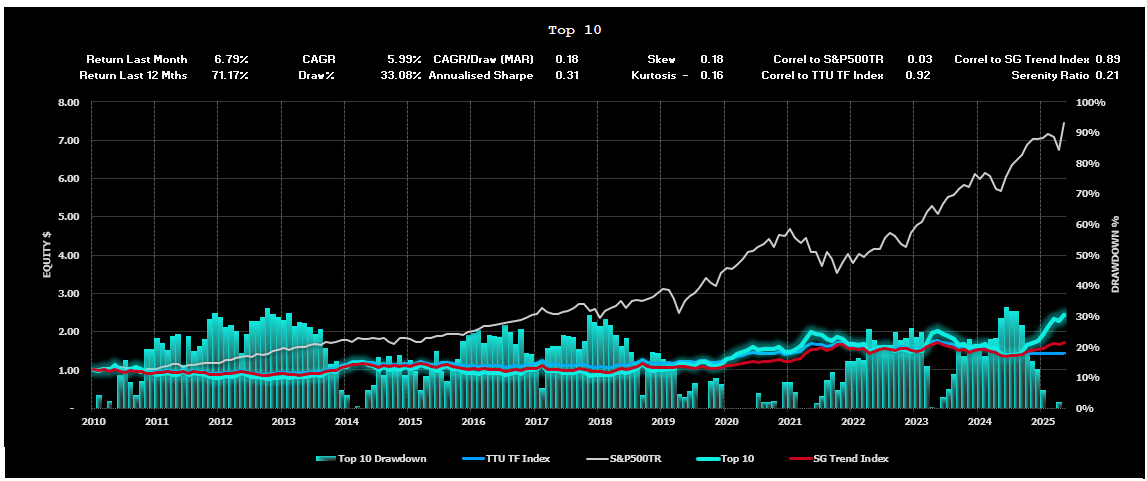
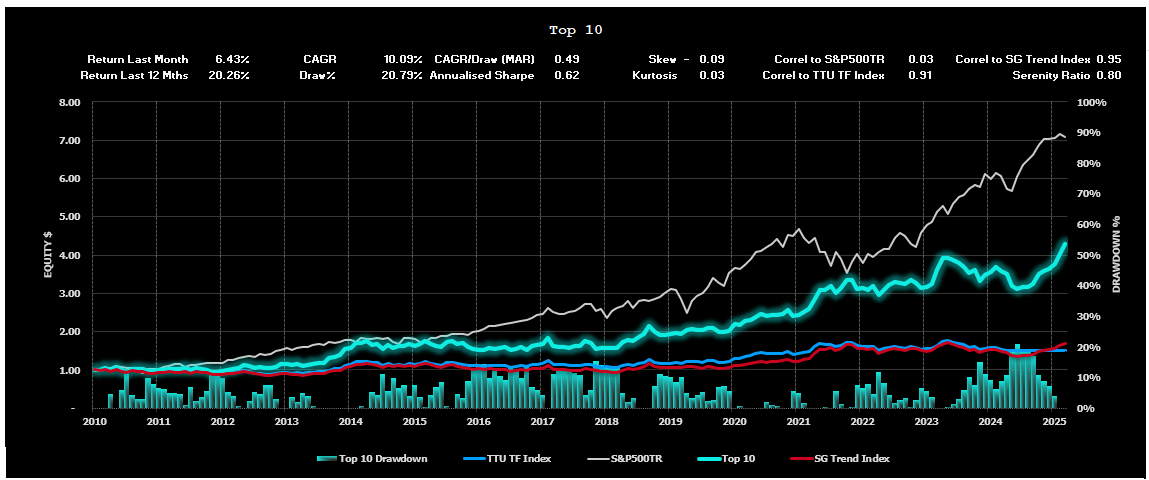
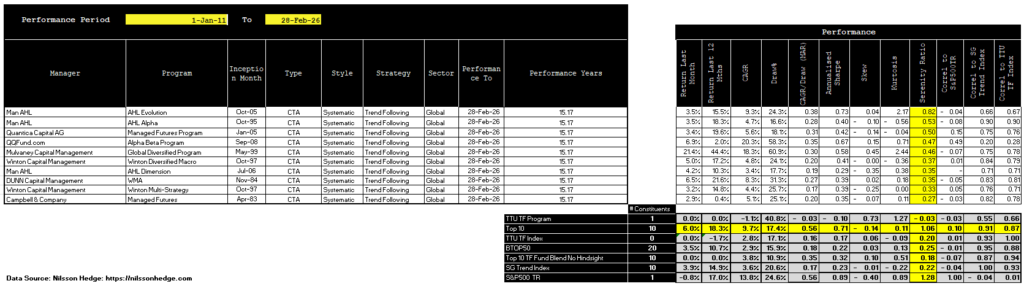
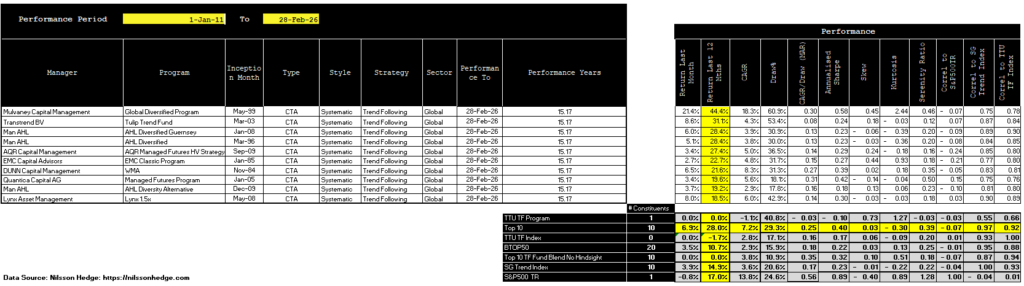
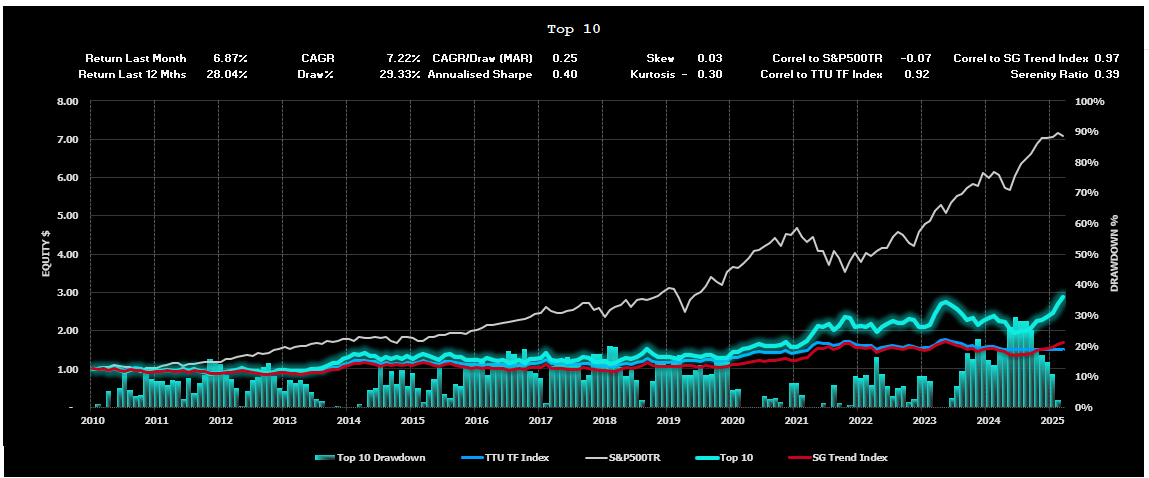
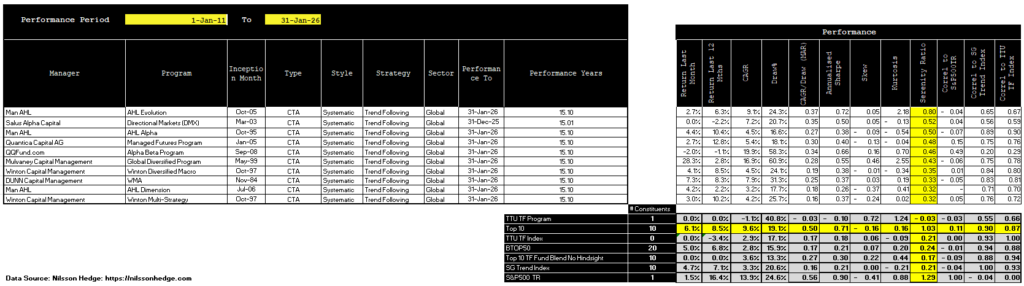
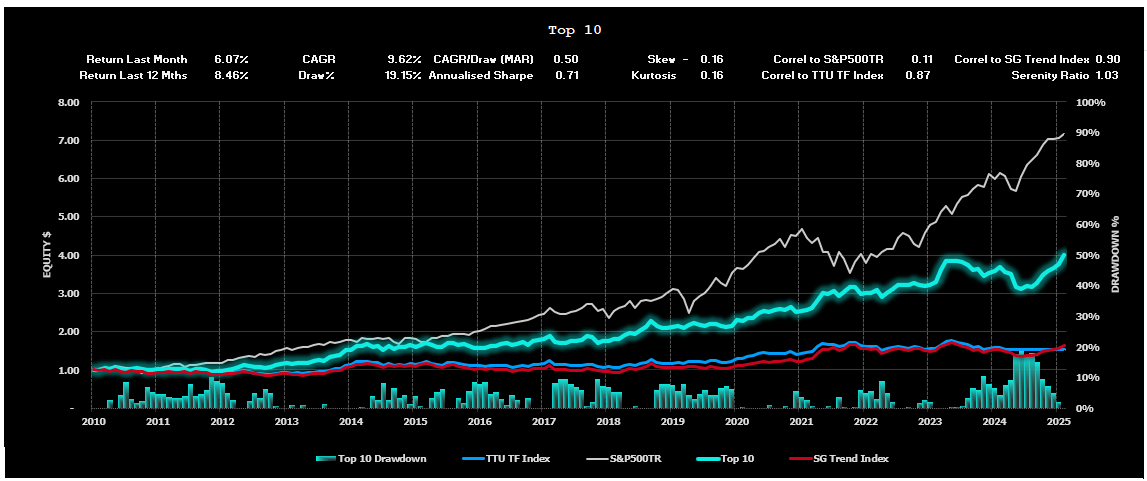
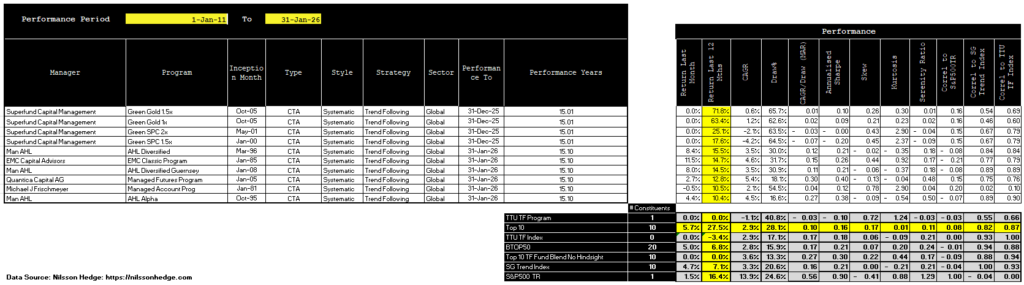
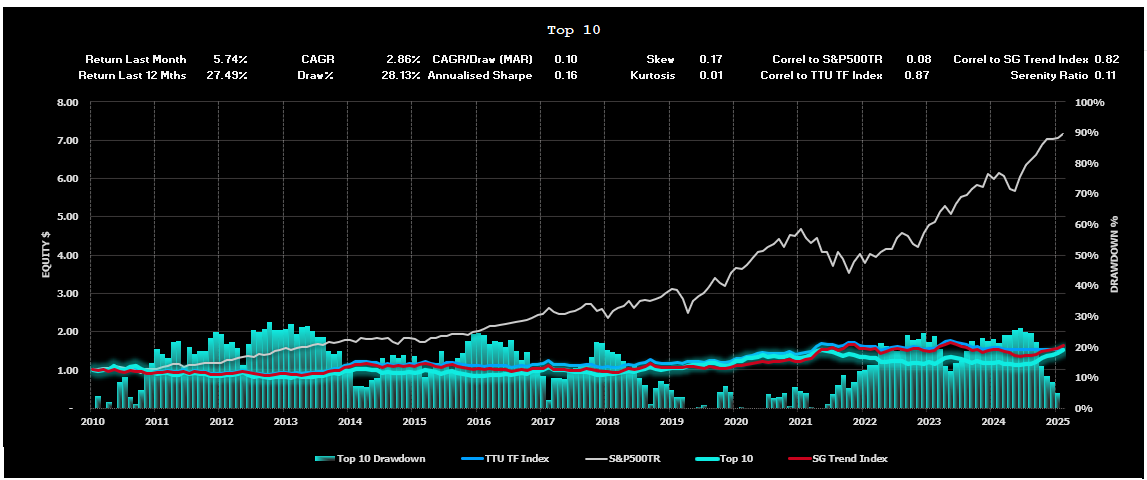
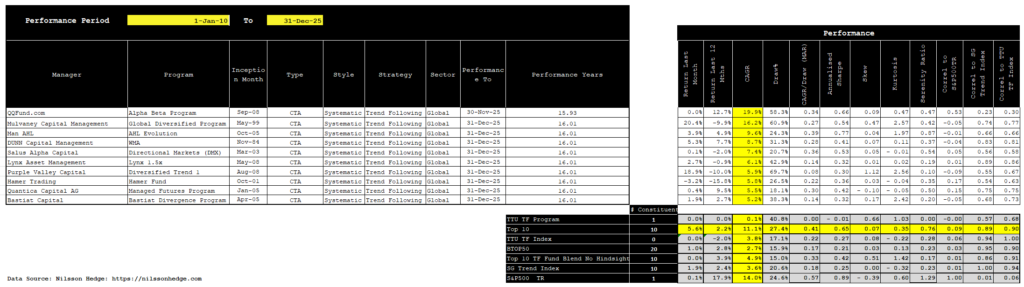
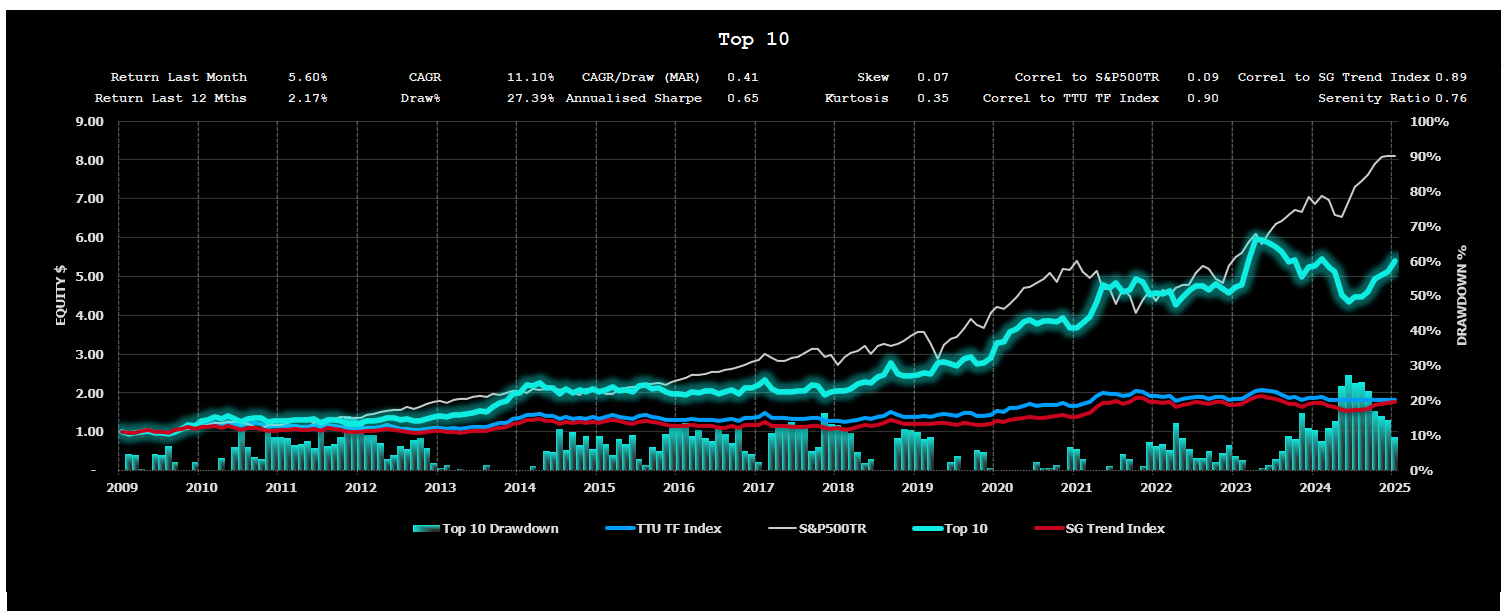
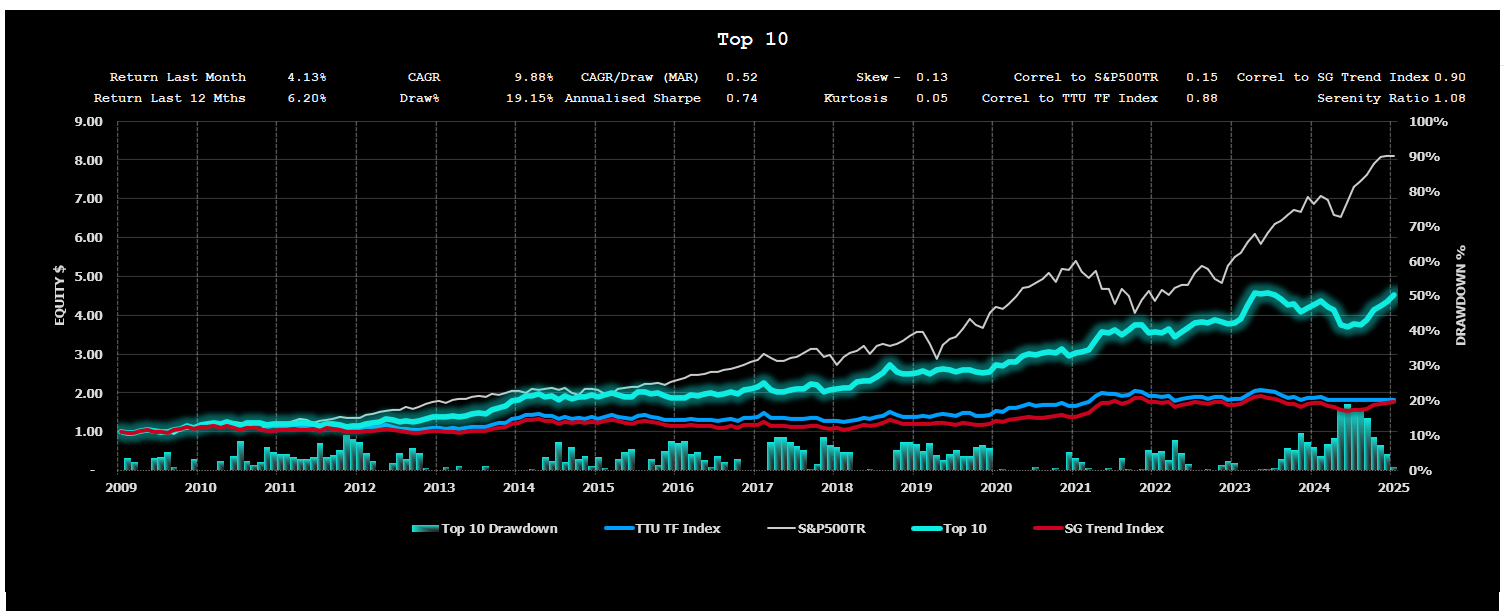
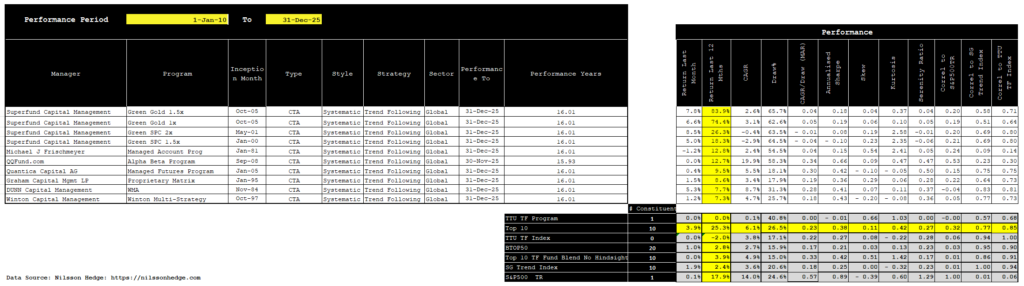
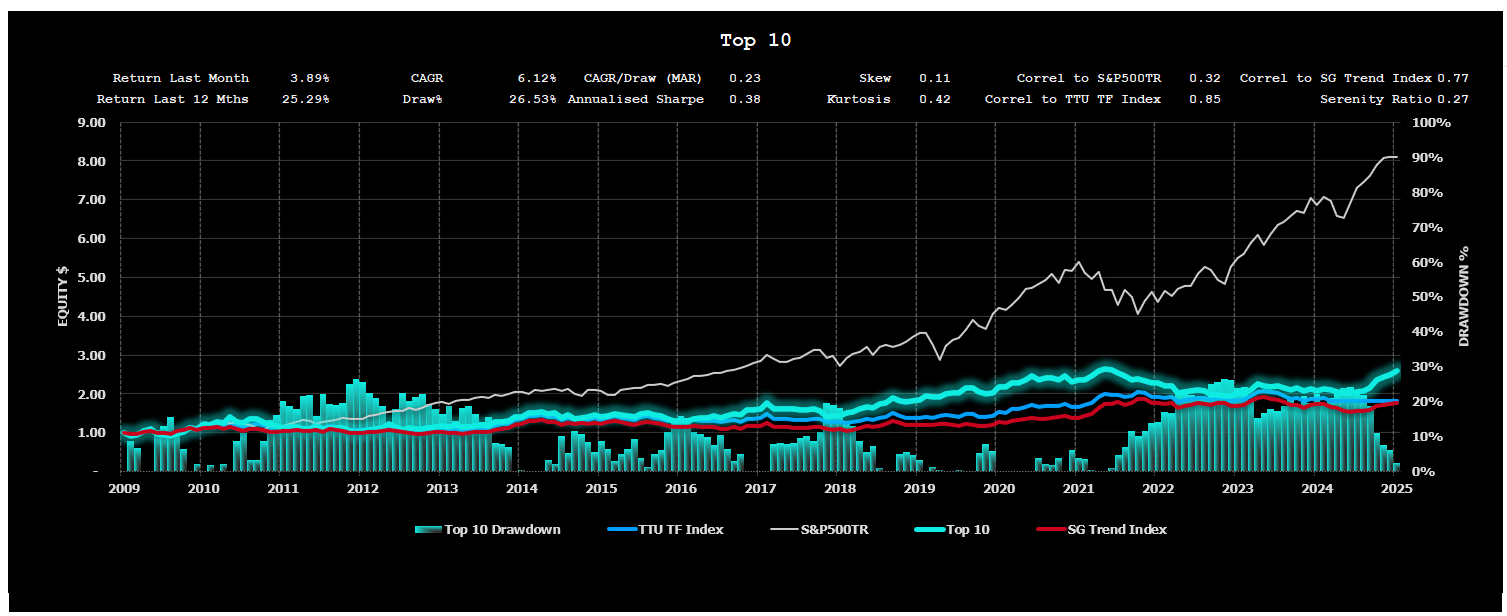
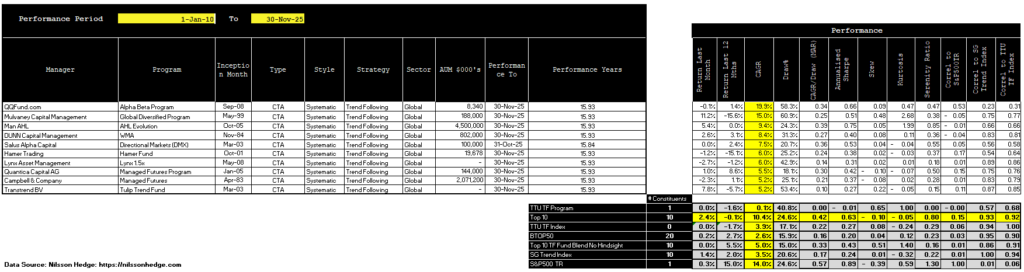
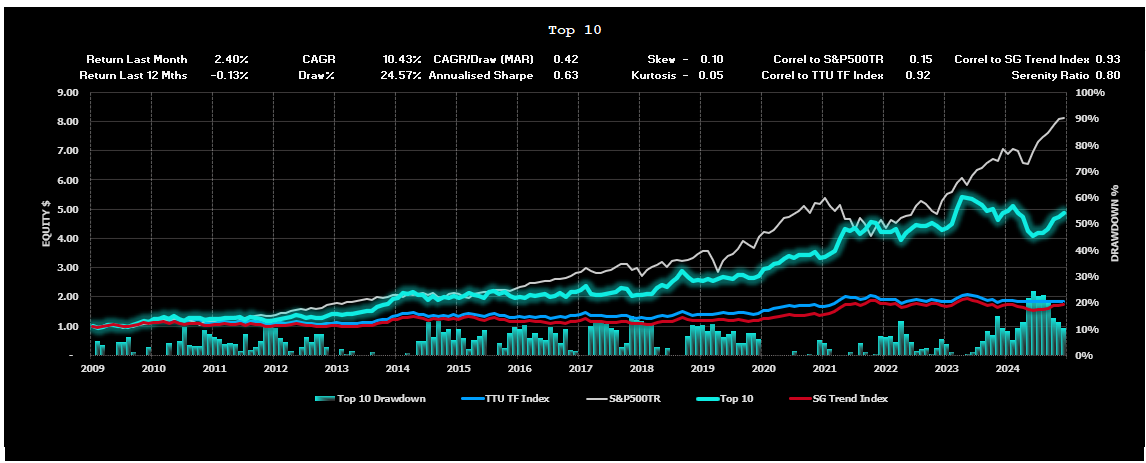
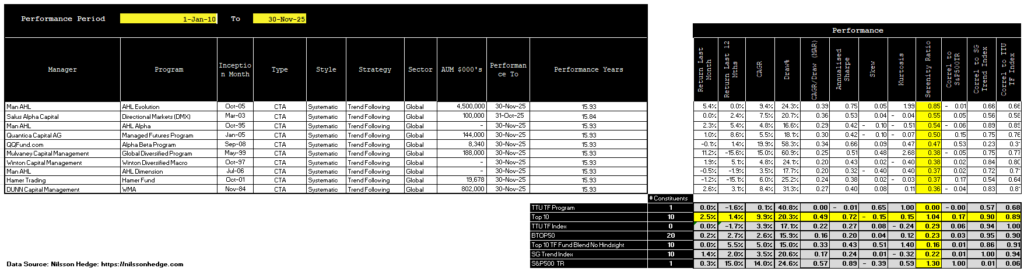
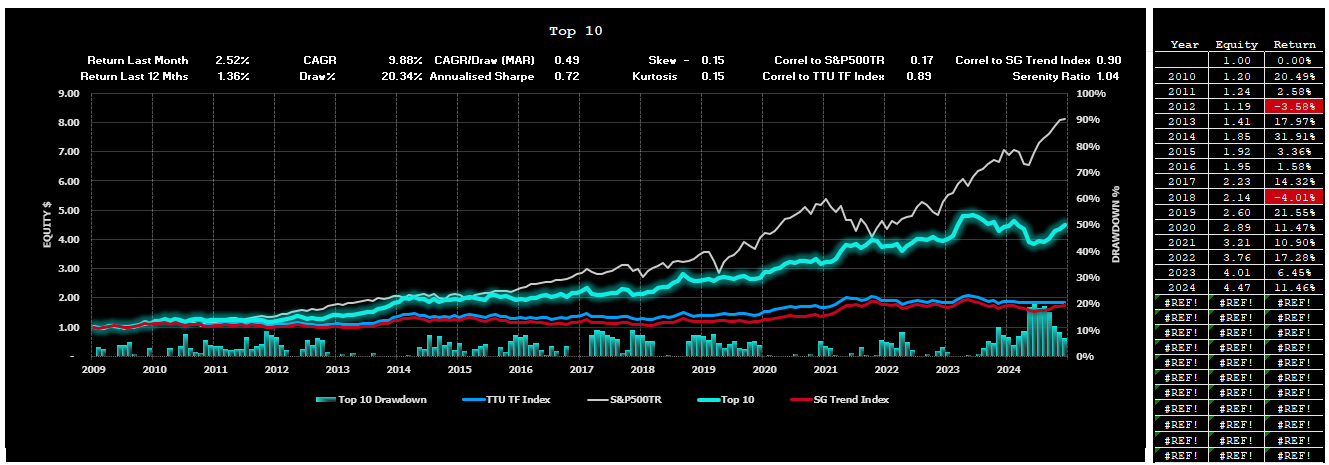
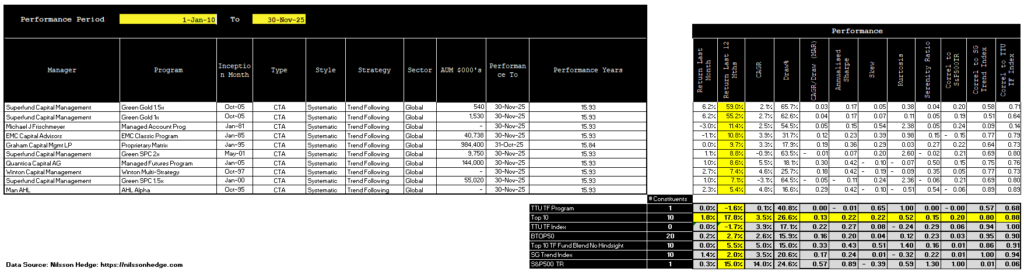
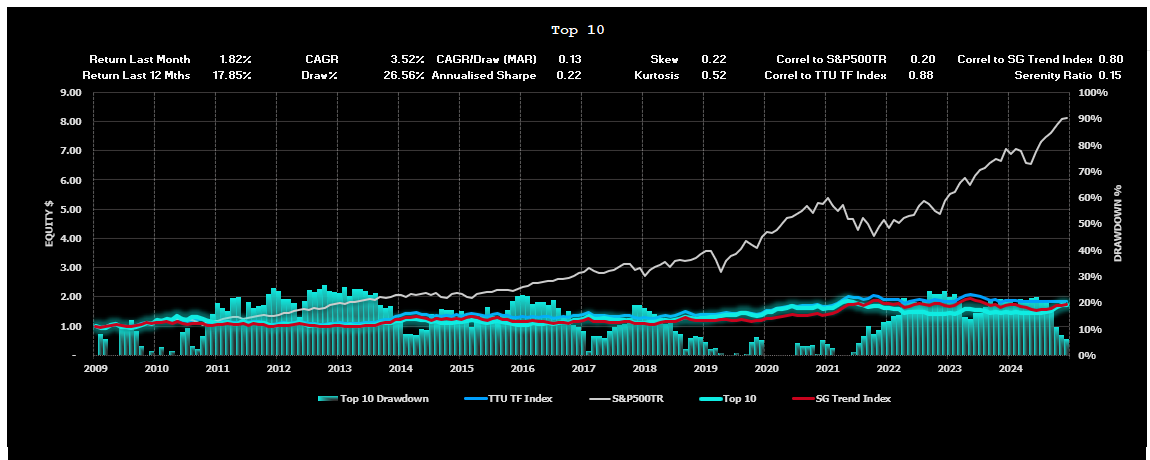
We have prepared the following Top 10 lists (excluding non-reporting programs) for various performance categories based on monthly performance returns for a 15-year period commencing 1st January 2011 to the current month.
Top 10 Listing – by Compound Annual Growth Rate


Top 10 Listing – by Risk-Adjusted Return (Serenity Ratio)


Top 10 Listing – by Last 12 months Performance


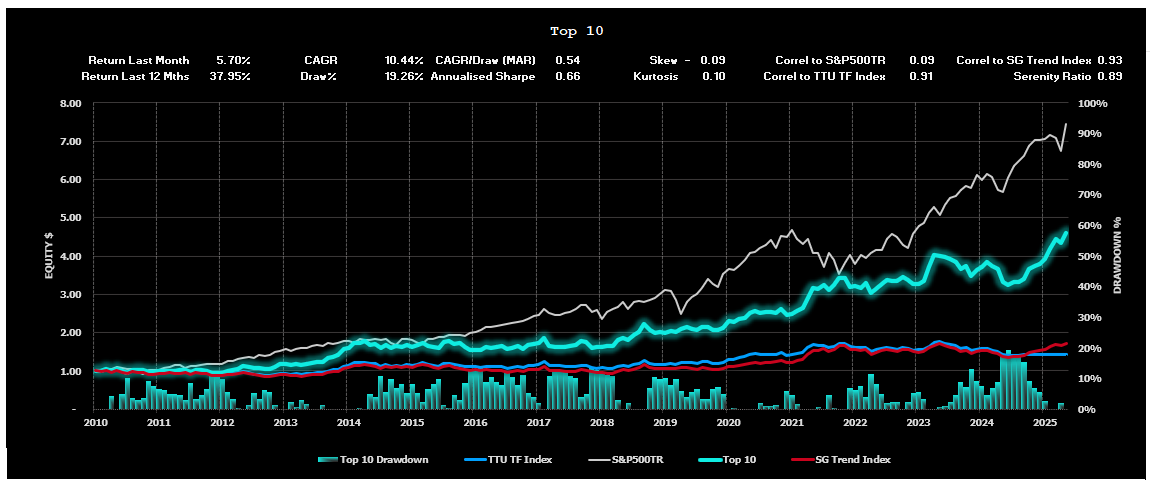
Performance Results for the TTU Top 5 by Serenity Ratio
In a research project we undertook at TTU, we examined three different allocation methods that could be deployed by an investor seeking to optimally allocate investment funds towards 5 of the top-ranked Globally Diversified Systematic Trend Following Programs with a long-term track record.
These three methods adopted 3 different forms of performance metric, namely:
- Top 5 performers by Compound Annual Growth Rate (CAGR) using a rolling lookback of 15 years.
- Top 5 performers by MAR ratio (CAGR/Max Draw%) using a rolling lookback of 15 years.
- Top 5 performers by Serenity Ratio using a rolling lookback of 15 years.
The findings of our project can be obtained by clicking on this link.
Our research determined that the optimal selection method was the Serenity Ratio method.
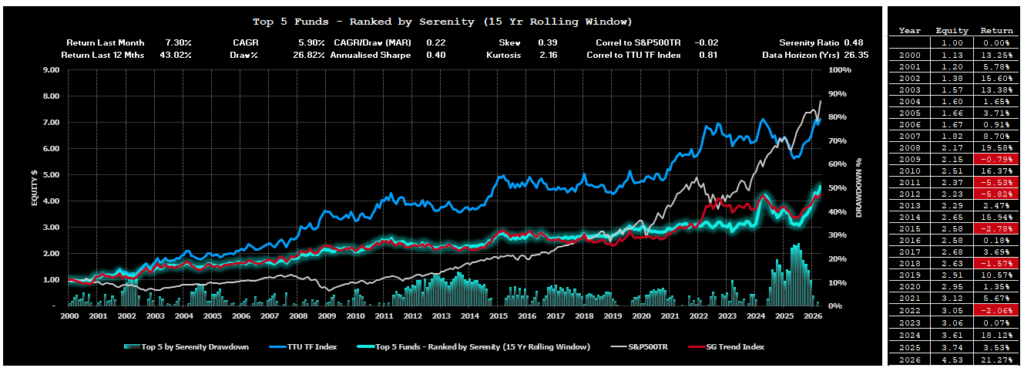
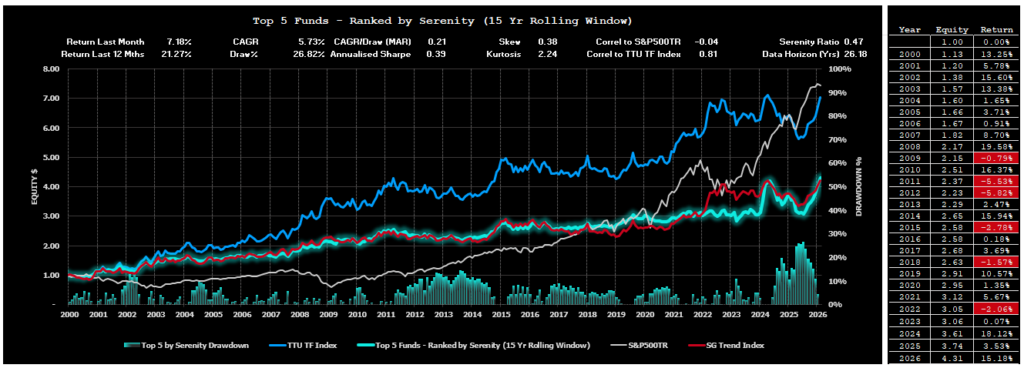
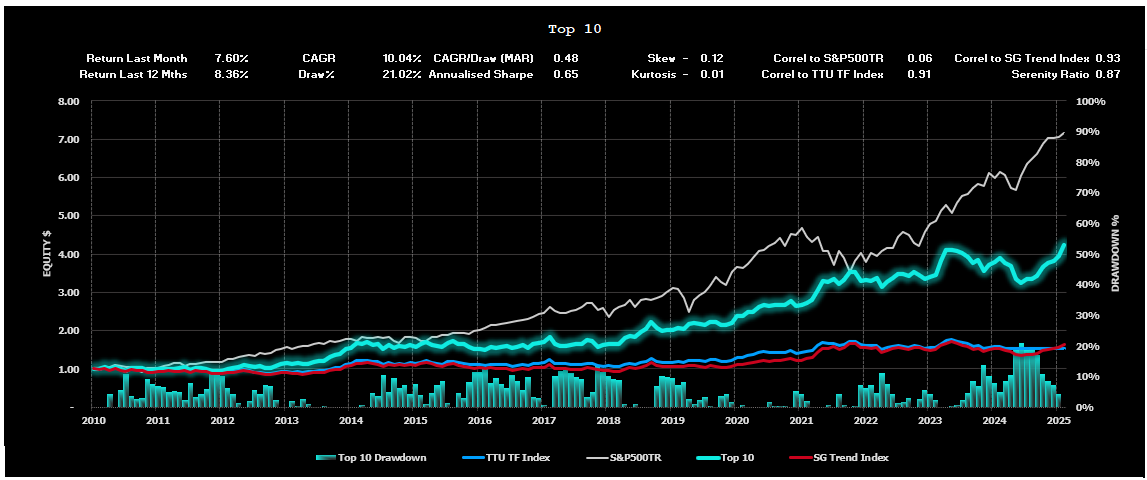
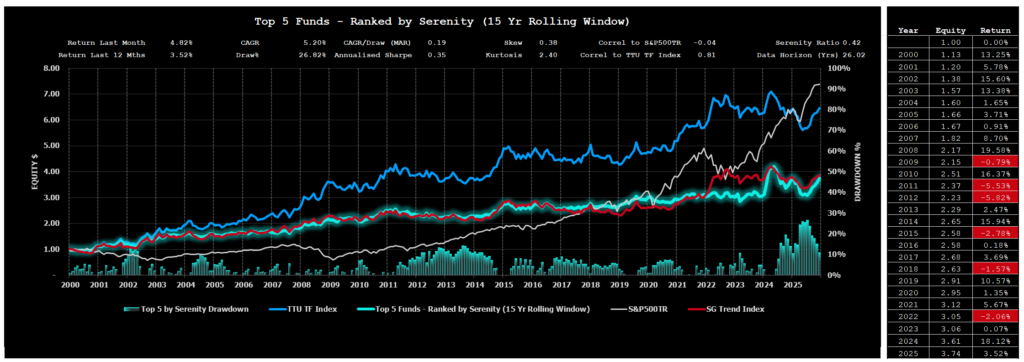
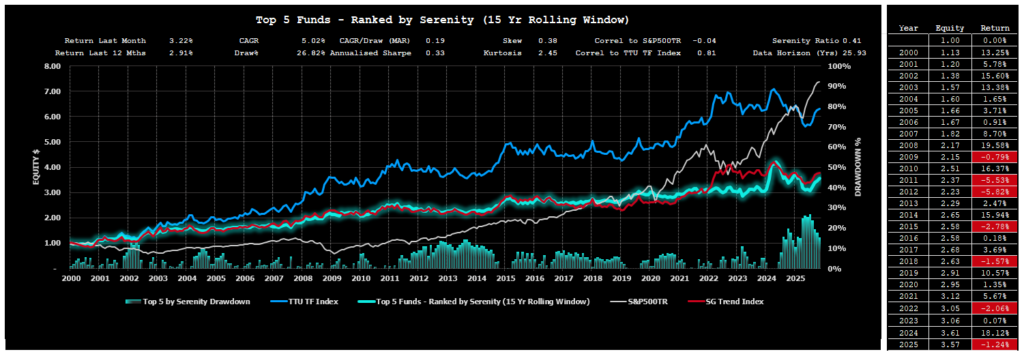
The Serenity Top 5 Selection Method gained 1.21 percent in September, a second consecutive positive month. It was the weakest result among the trend composites covered in this report. It finished 182 basis points behind the BTOP50 at 3.03 percent, 256 behind the TTU TF Index at 3.77 percent and 305 behind the SG Trend Index at 4.26 percent. In August the concentrated composite had finished well above the range of the broad trend benchmarks. In September it finished below that range, although still 156 basis points ahead of the S&P 500 Total Return Index. The trailing twelve-month return eased to 34.07 percent from 40.19 percent, as a much stronger September 2025 result left the rolling window. The year-to-date result rose to 21.64 percent, which remains the highest of the composites in this report and 584 basis points ahead of the SG Trend Index. All five constituents reported for September, so this month’s composite is struck on the full selection.
September tested the composite differently from August. A concentrated composite has less breadth to dilute its exposure than the 52-program TTU index, so its result depends heavily on how five programs were positioned in the markets that moved. In August that concentration worked in its favour. In September the composite gained less from the month’s trends than the broad benchmarks did. The interruptions of the third week and the reversal in the petroleum contracts in the last full week are plausible sources of the shortfall. The benchmark data alone cannot say which constituents bore the cost. A single month of underperformance after a 5.62 percent gain in August is within the range this composite has shown through 2026.
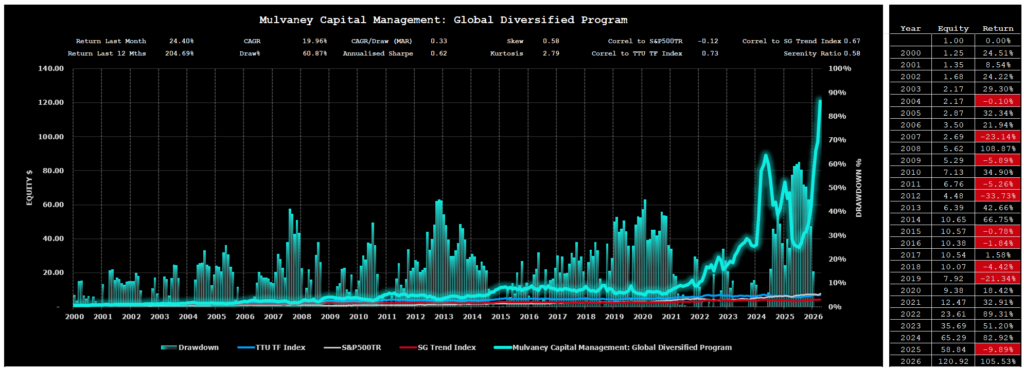
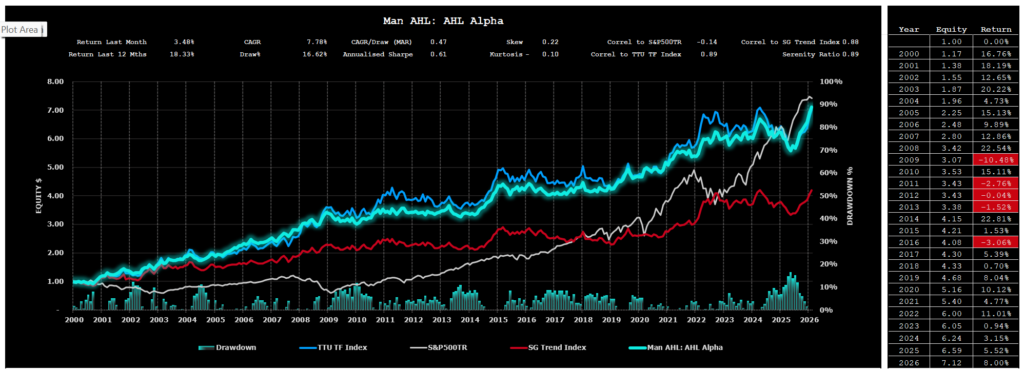
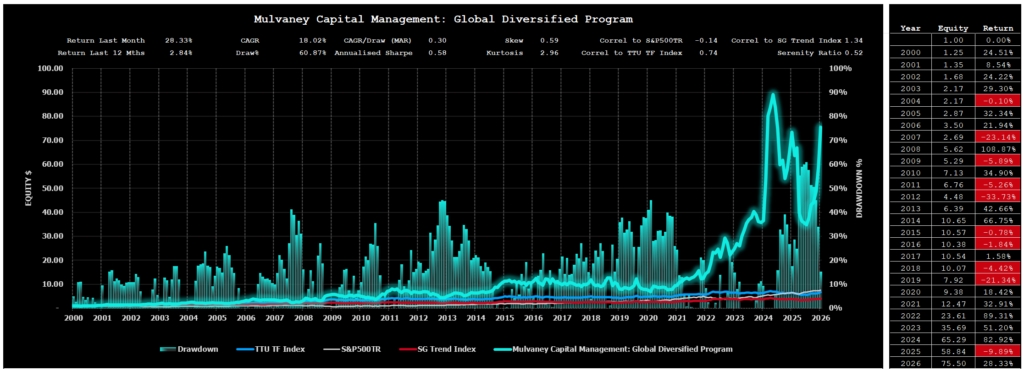
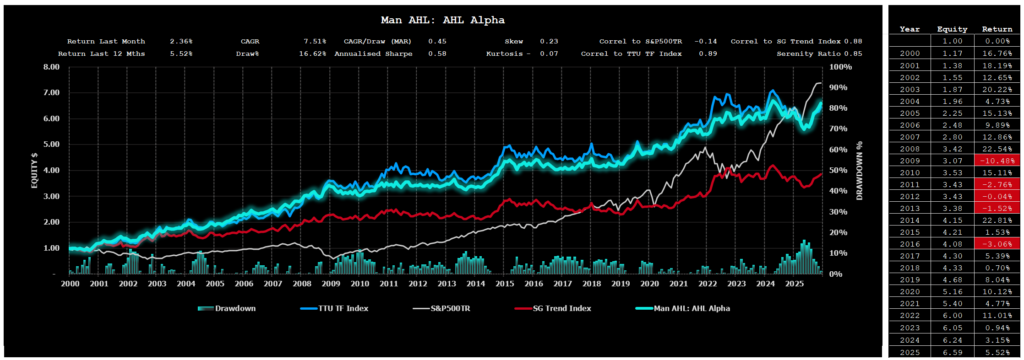
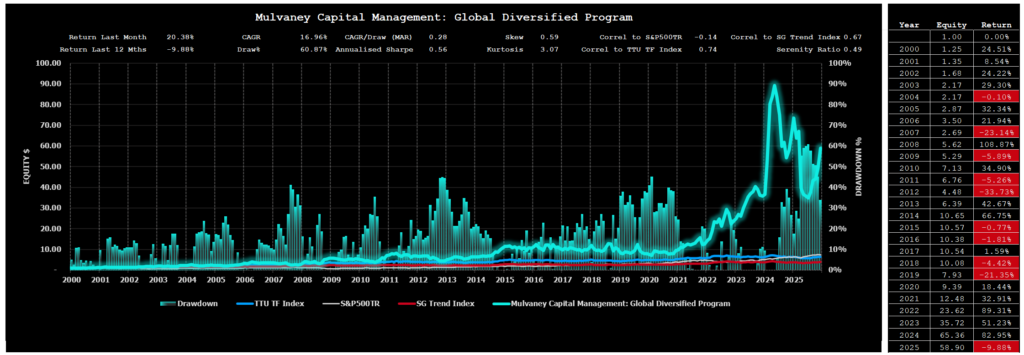
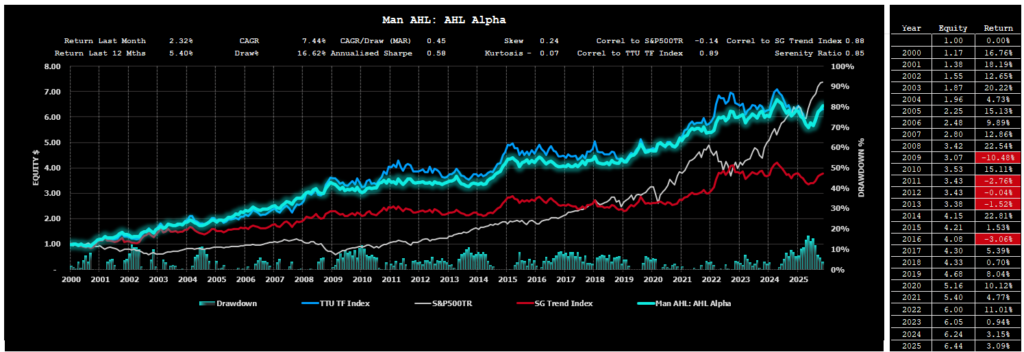
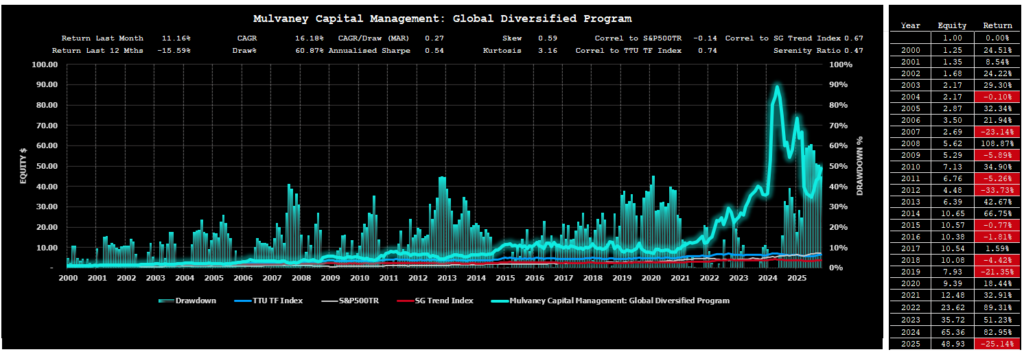
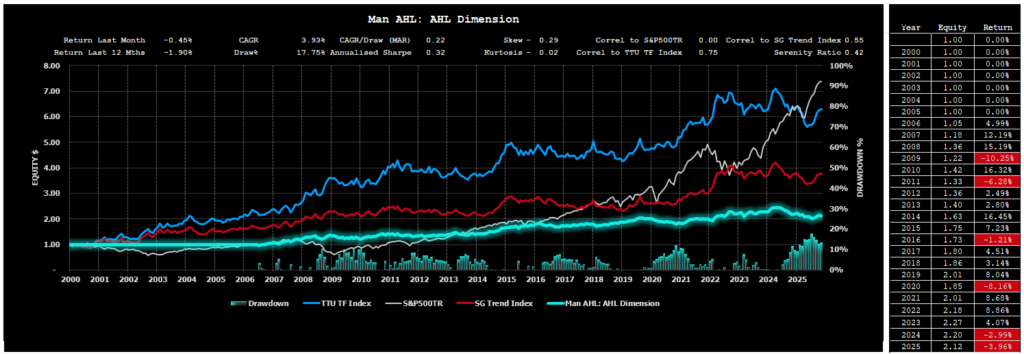
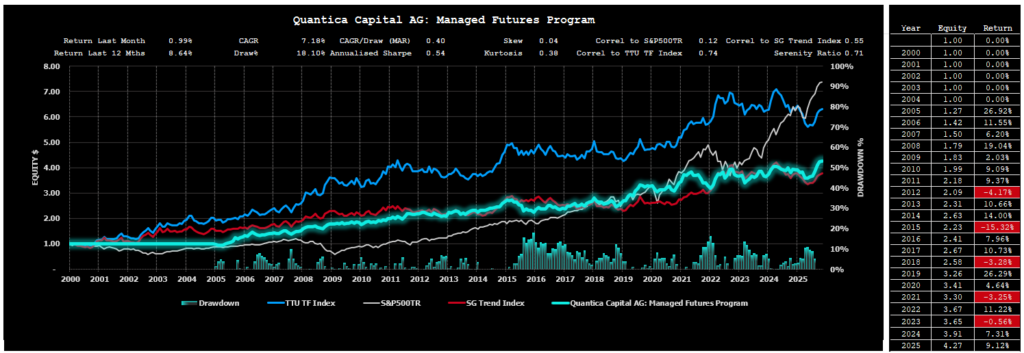
The 2026 Serenity selection retains the same five programs as 2025, with the revised ranking applying from 1 February 2026 to 31 January 2027. That continuity is consistent with the durability of the managers across the full 15-year evaluation window. Mulvaney Capital Management’s Global Diversified Program is known for a high-convexity profile that responds to persistent, expanding trends rather than to any preferred direction, which means it can amplify both gains and give-backs. A month in which the strongest trends were interrupted midway and a leading sector reversed late may have been less suited to that profile than August was. That variability is part of the asymmetry the selection is designed to retain.
The Serenity Ratio remains useful because it rewards durability, compounding and drawdown control across a long evaluation window rather than chasing recent returns. Across the full reporting history of 26.77 years, the Serenity composite has produced a CAGR of 5.82 percent with a maximum drawdown of 26.82 percent and a Serenity Ratio of 0.48. Its correlation is minus 0.02 to the S&P 500 Total Return Index and 0.81 to the TTU TF Index. The CAGR rose from 5.79 percent in August and the Serenity Ratio from 0.47, while the historical maximum drawdown was unchanged. September added a fifth version of the diversification relationship in five months. May saw opposite directions, June saw both negative, and July saw trend following down modestly against an almost flat equity market. In August both rose. In September the two moved in opposite directions again, with the composite gaining 1.21 percent while the S&P 500 lost 0.35 percent. The long-run near-zero equity correlation describes the relationship, and any single month can show any of these combinations.

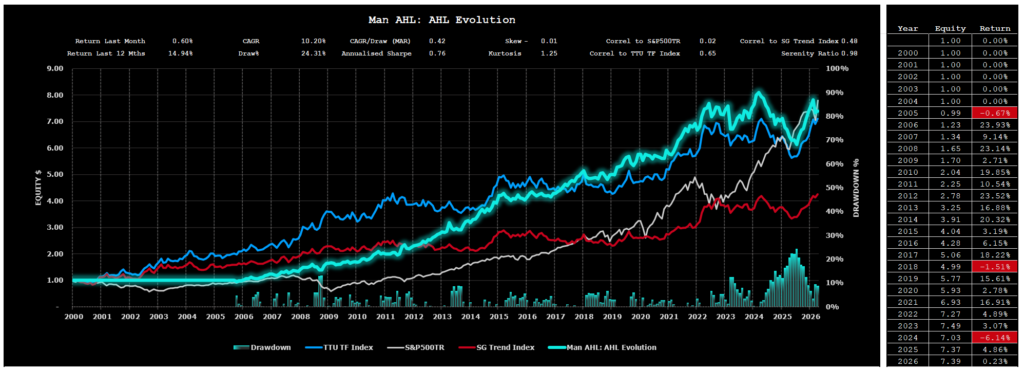
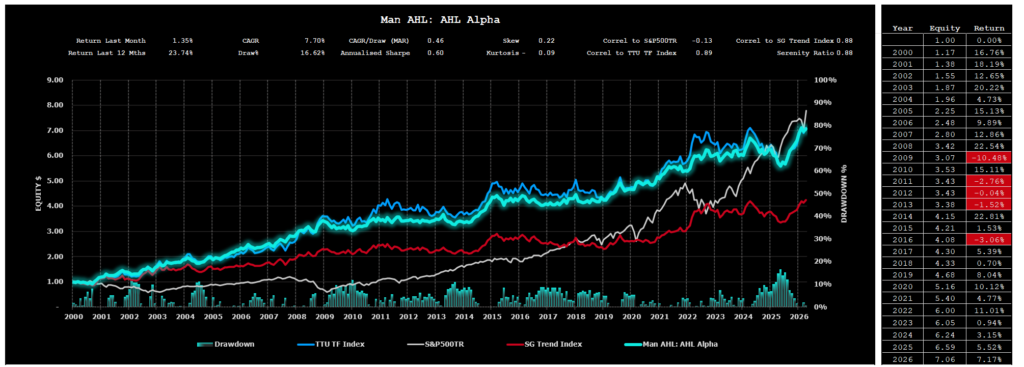
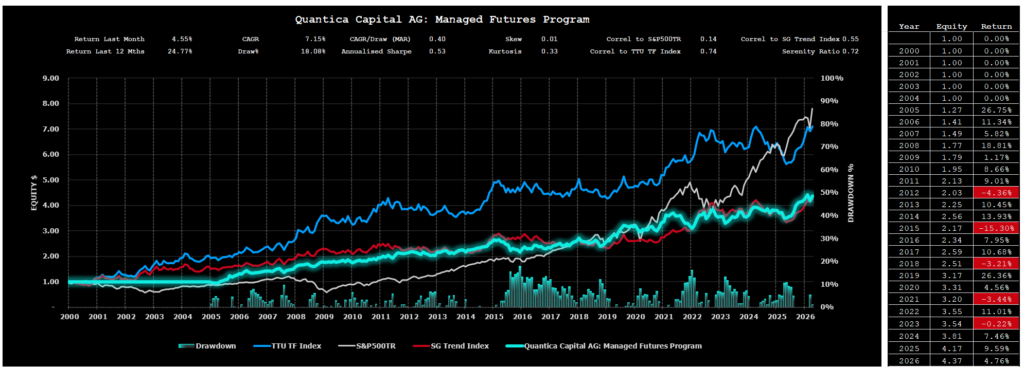
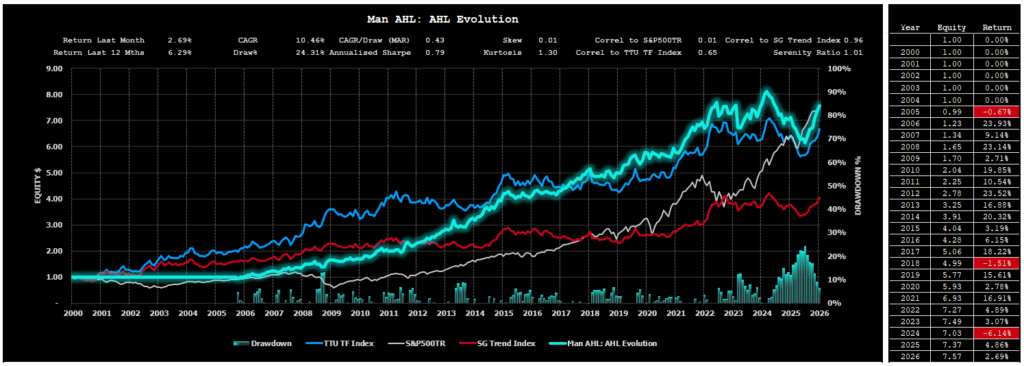
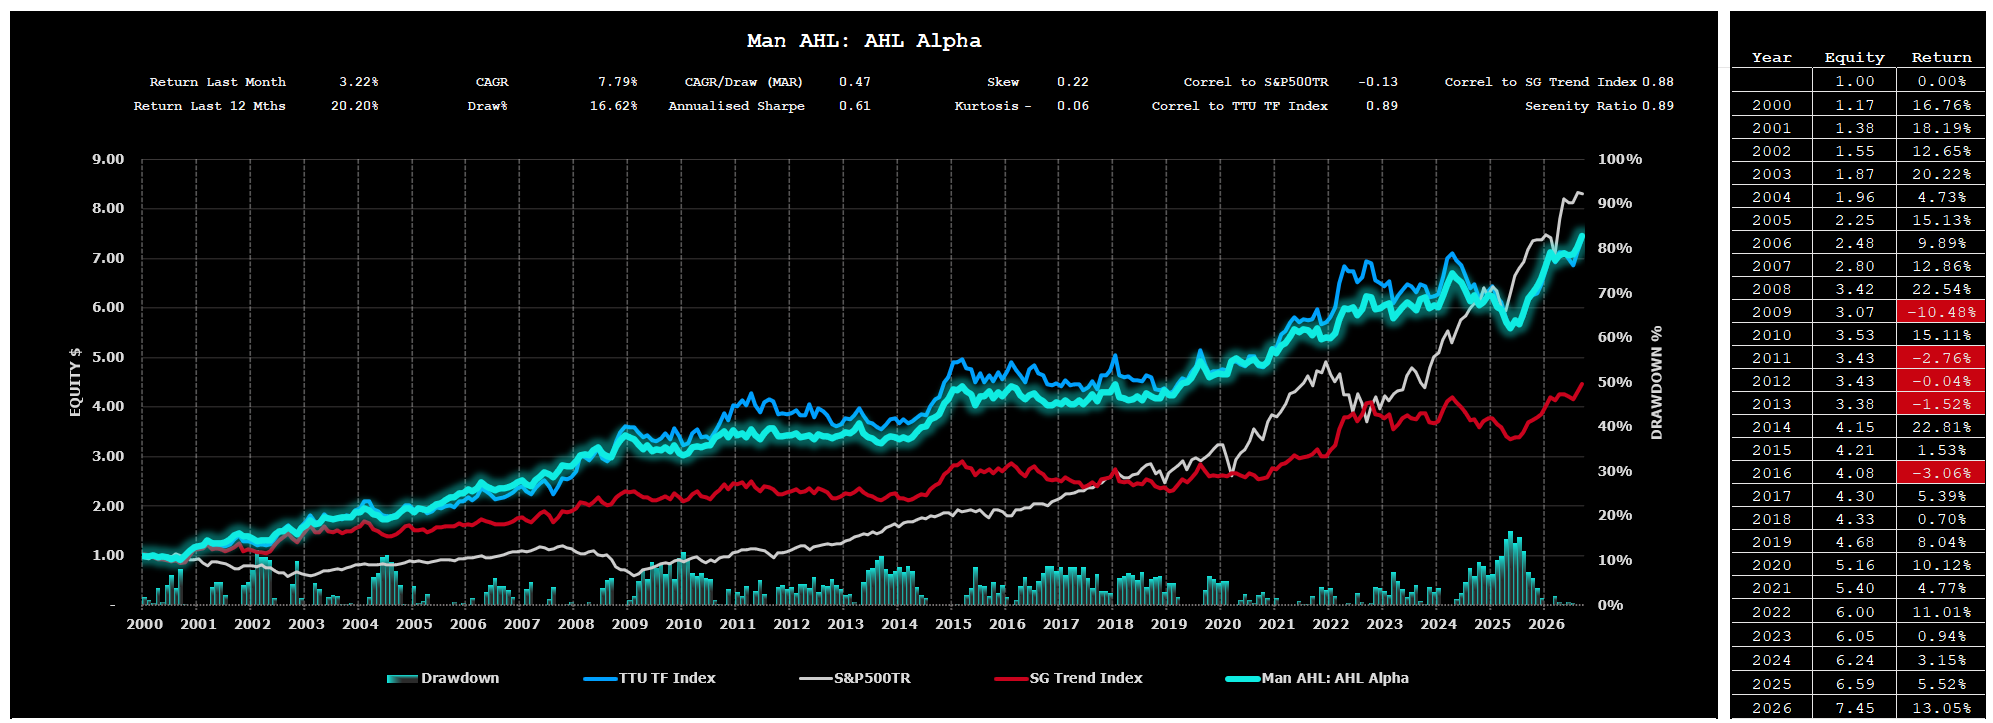
The 2026 Serenity selection is as follows and will be maintained for the investment period between 1st February 2026 to 31st January 2027:
- Man AHL: AHL Evolution;
- Man AHL: AHL Alpha;
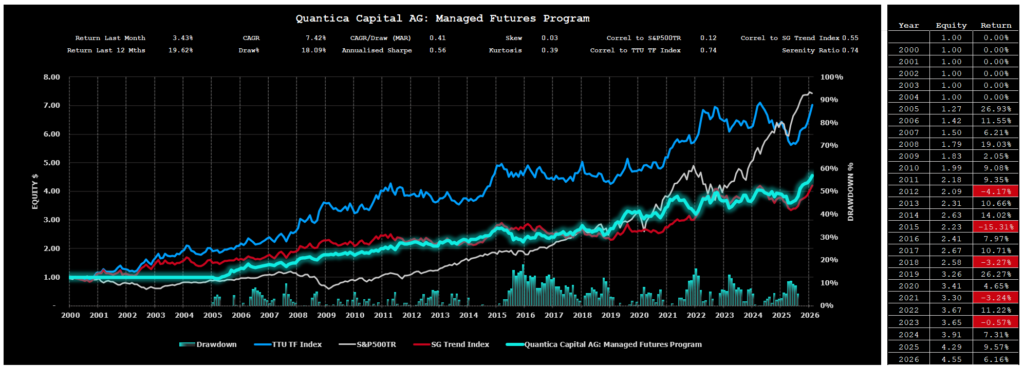
- Quantica Capital AG: Managed Futures Program;
- Mulvaney Capital Management: Global Diversified Program; and
- Man AHL: AHL Dimension.
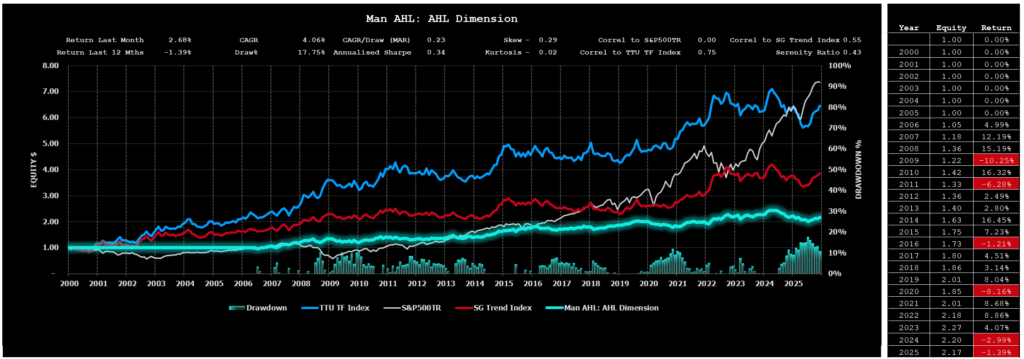
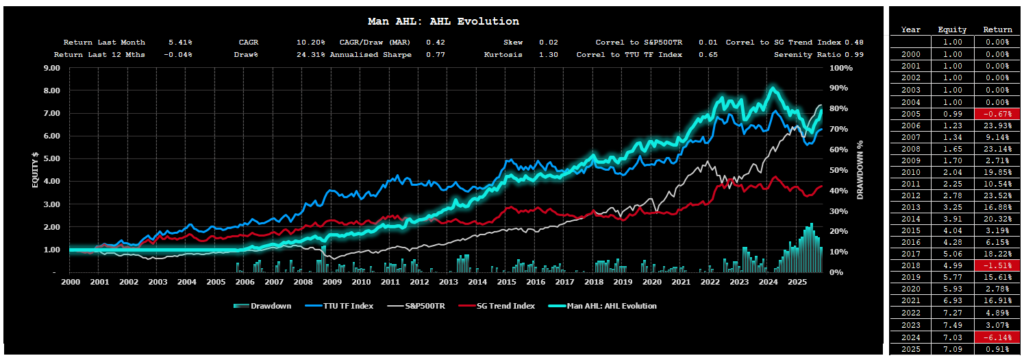
Individual Performance Results for the 5 Programs used for the Serenity allocation to the reporting month using the 2026 listing are as follows:



Performance Results for the Alternative 60/40 portfolio using the TTU Top 5 by Serenity Ratio
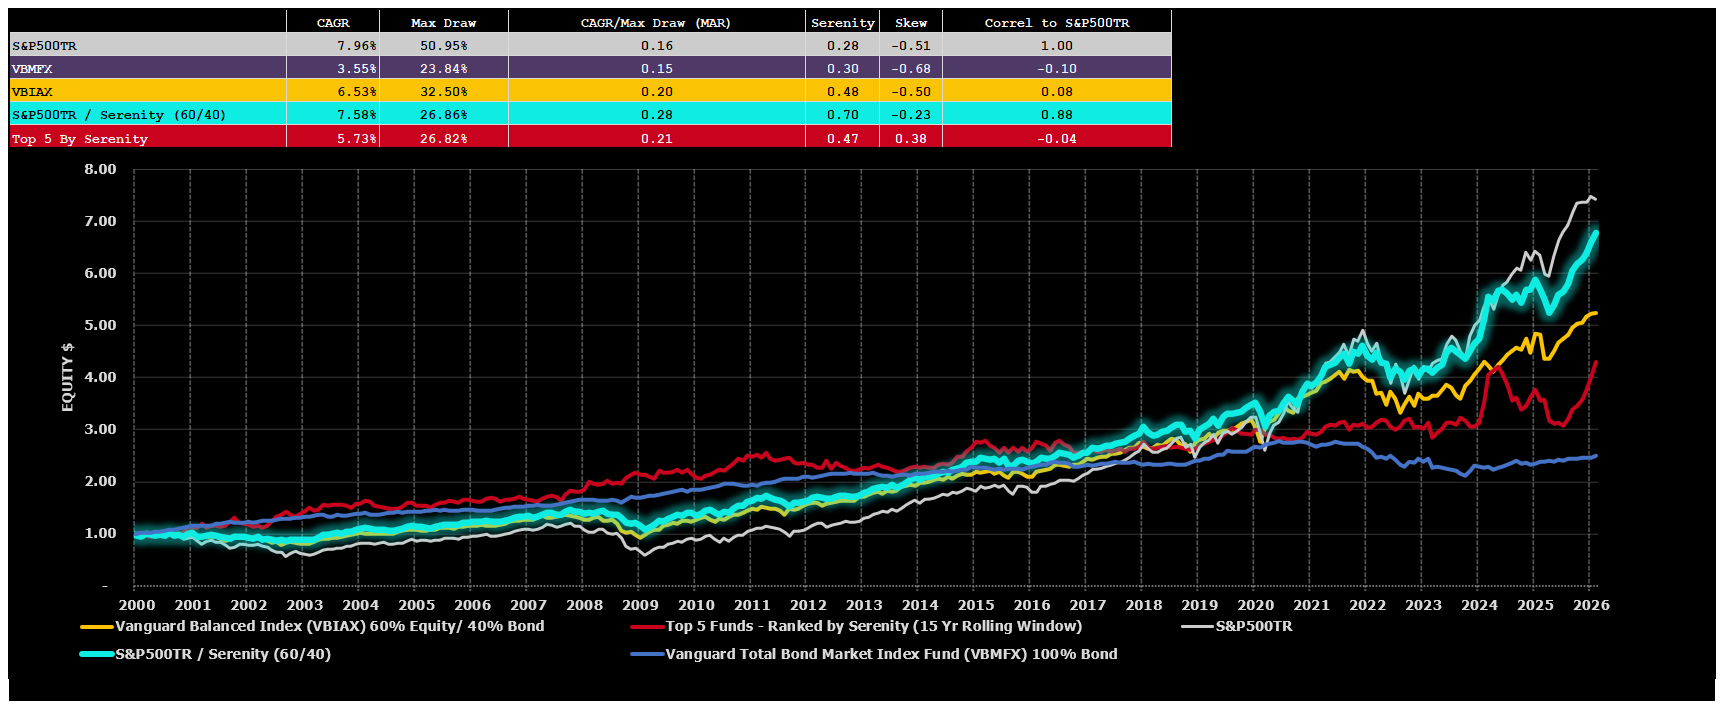
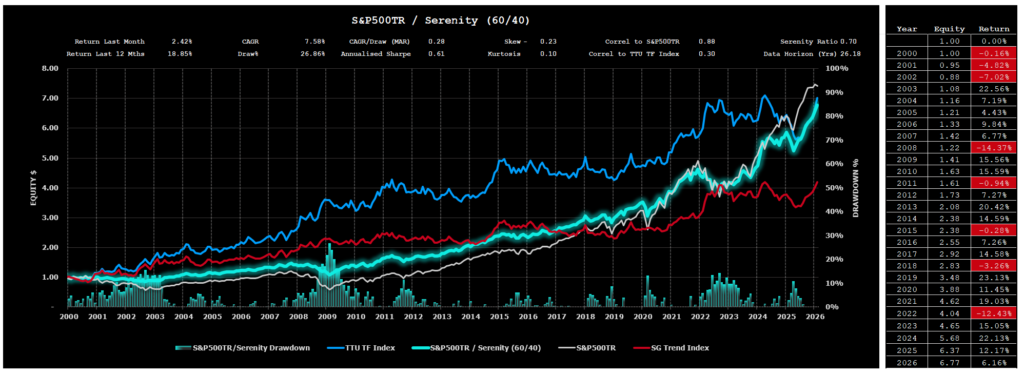
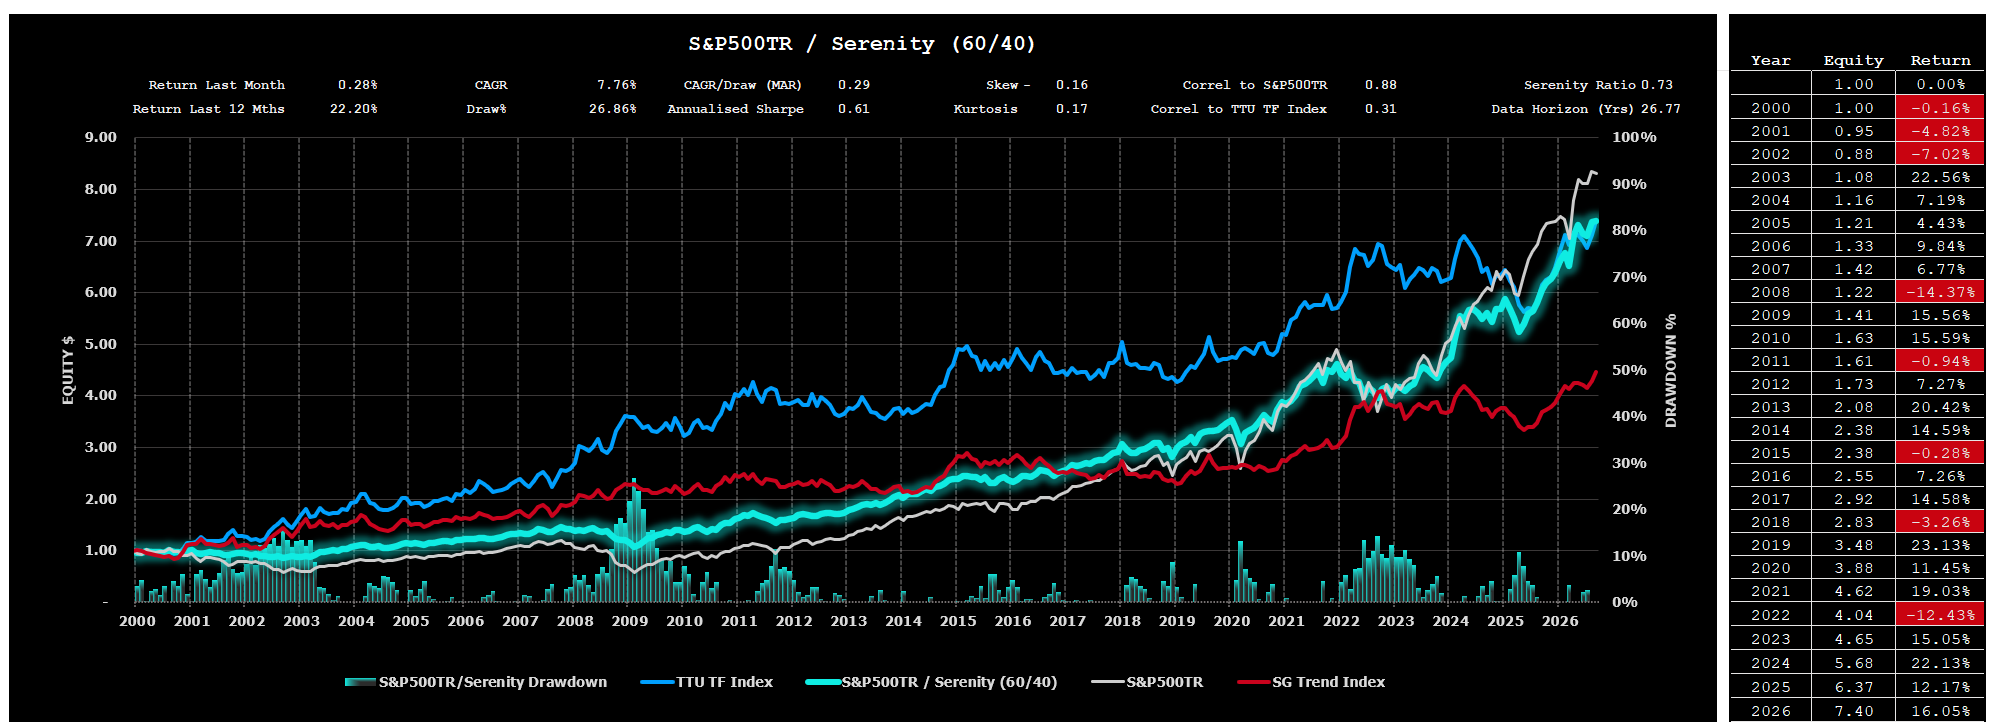
In our “How to Invest with the Best”blog post, we also highlighted the significant improved risk-adjusted performance results that could be achieved by replacing the 40% allocation to Bonds in the traditional 60/40 portfolio with an allocation of 40% towards the TTU Top 5 by Serenity ratio.
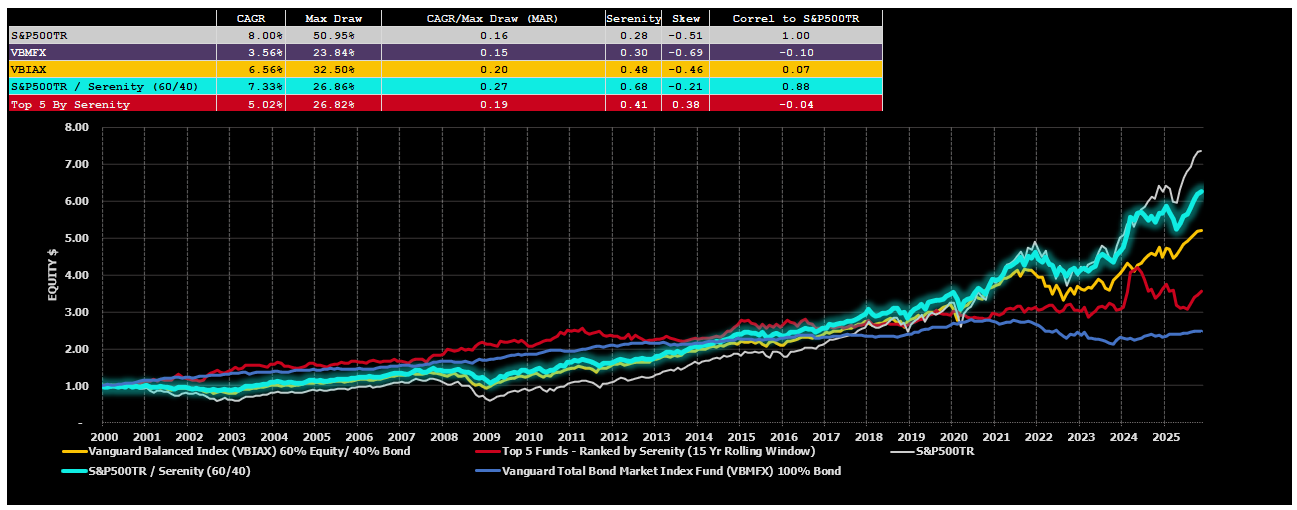
The evaluation compared the performance of a traditional 60% Equity/40% Bond portfolio against a 60% Equity/40% Serenity portfolio to highlight the uncorrelated historical nature of this Alternative 60/40 portfolio and demonstrate the benefits that a sizeable allocation towards the Serenity portfolio would bring to an investor if equity and bond markets go back to their historic relationship and become more positively correlated in the future. There is no guarantee that correlations remain static over time and it is possible that bond markets and equity markets may lose their uncorrelated relationship that has existed in the last 20 years or so. It is far less likely that the TF managers within the Serenity Grouping will ever be strongly positively correlated to the Equities market, over the long run, given the extensive global diversification and ability to go long and short, that is present within the constituents of the Serenity Grouping.
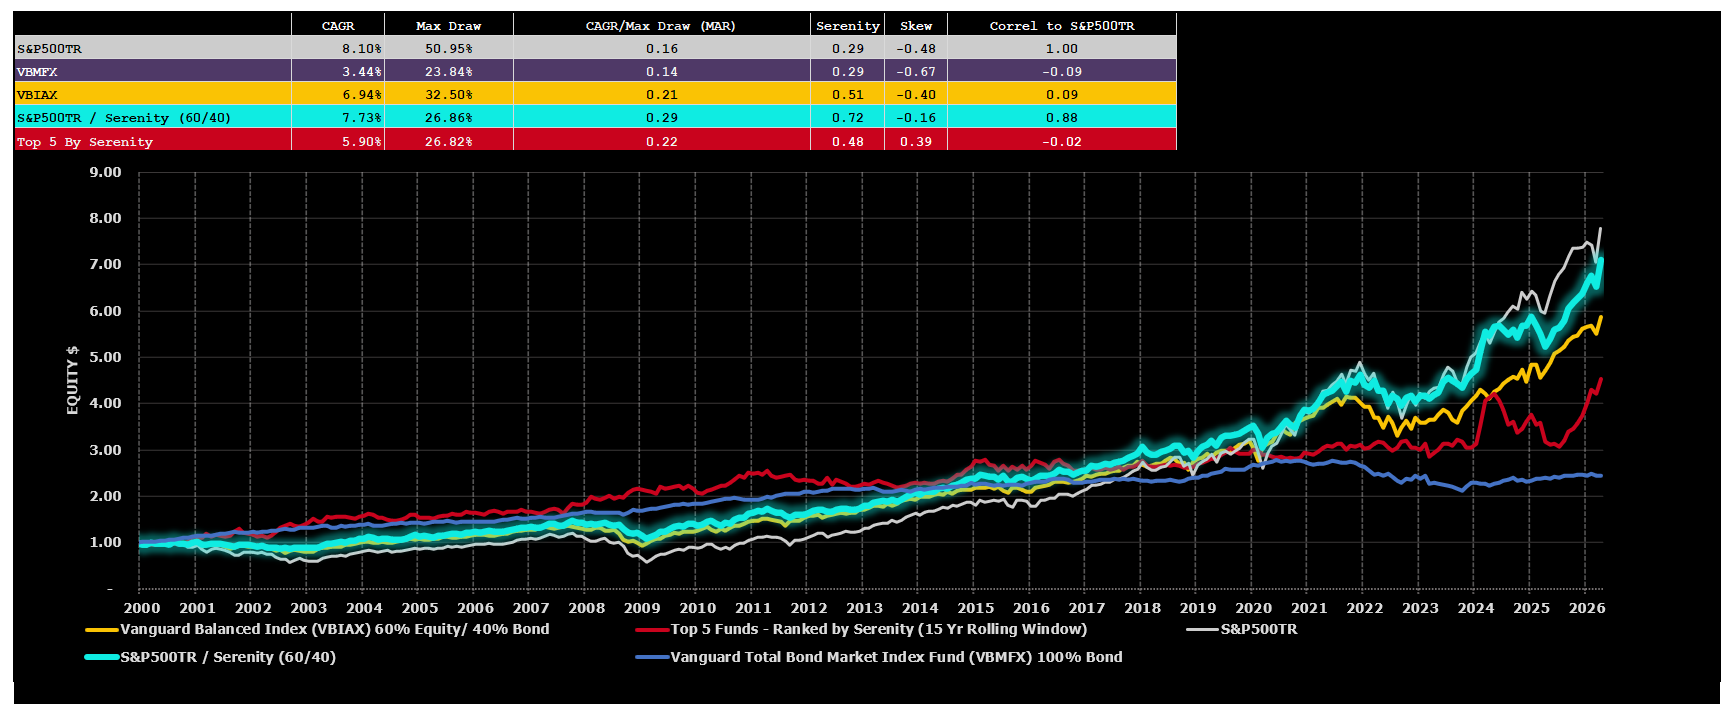
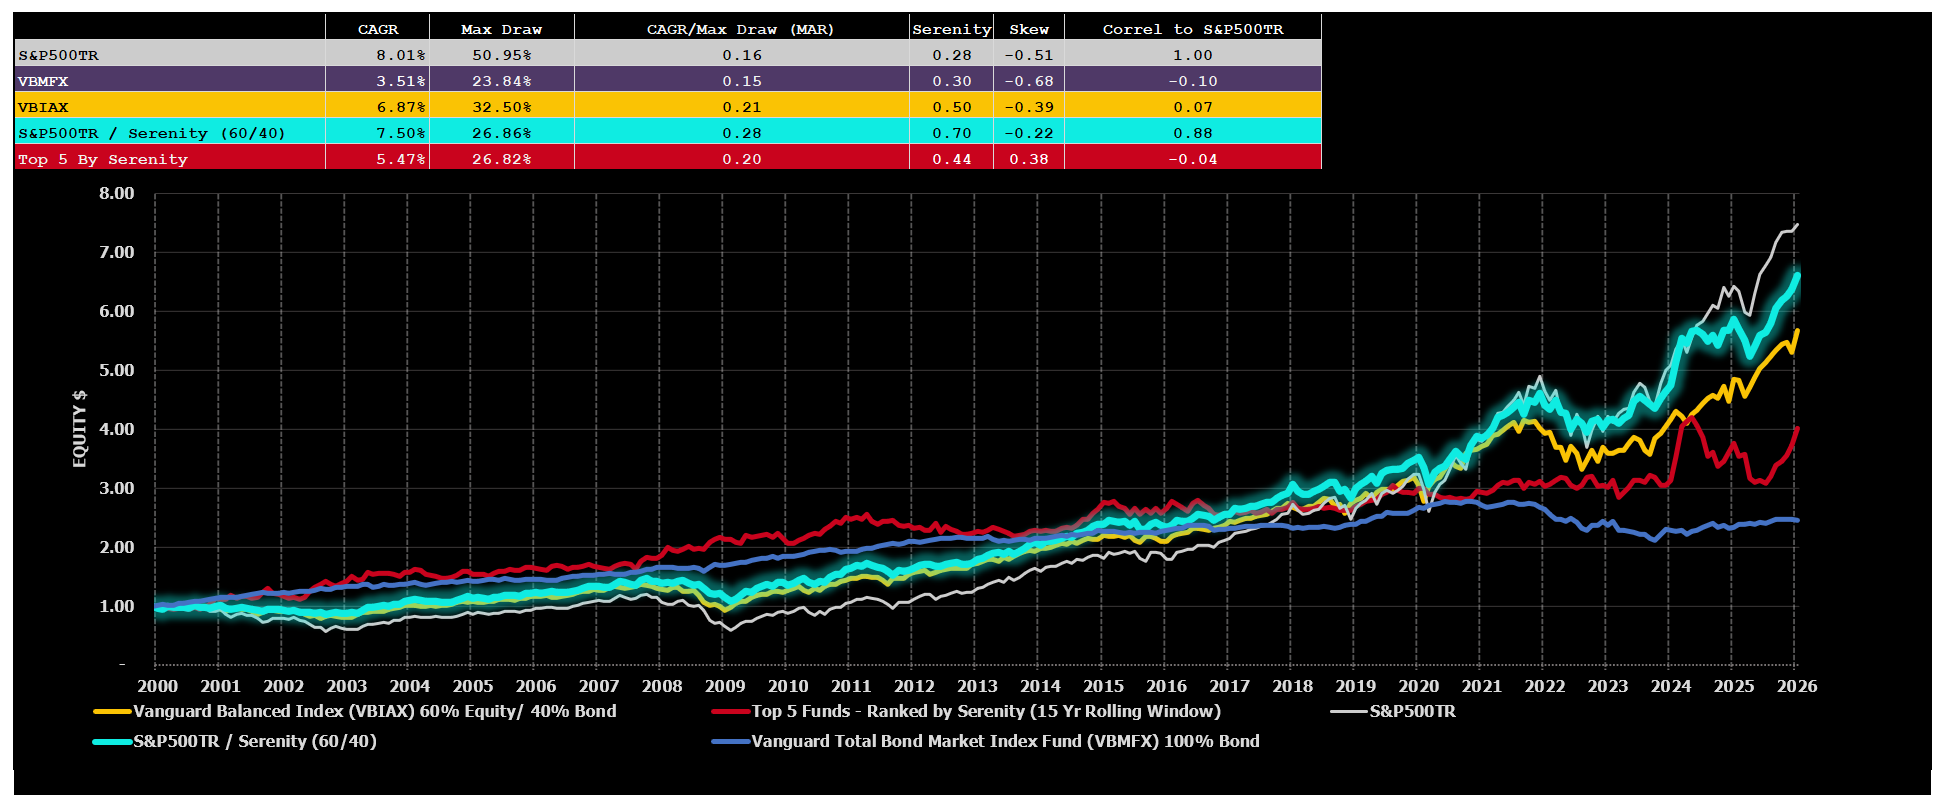
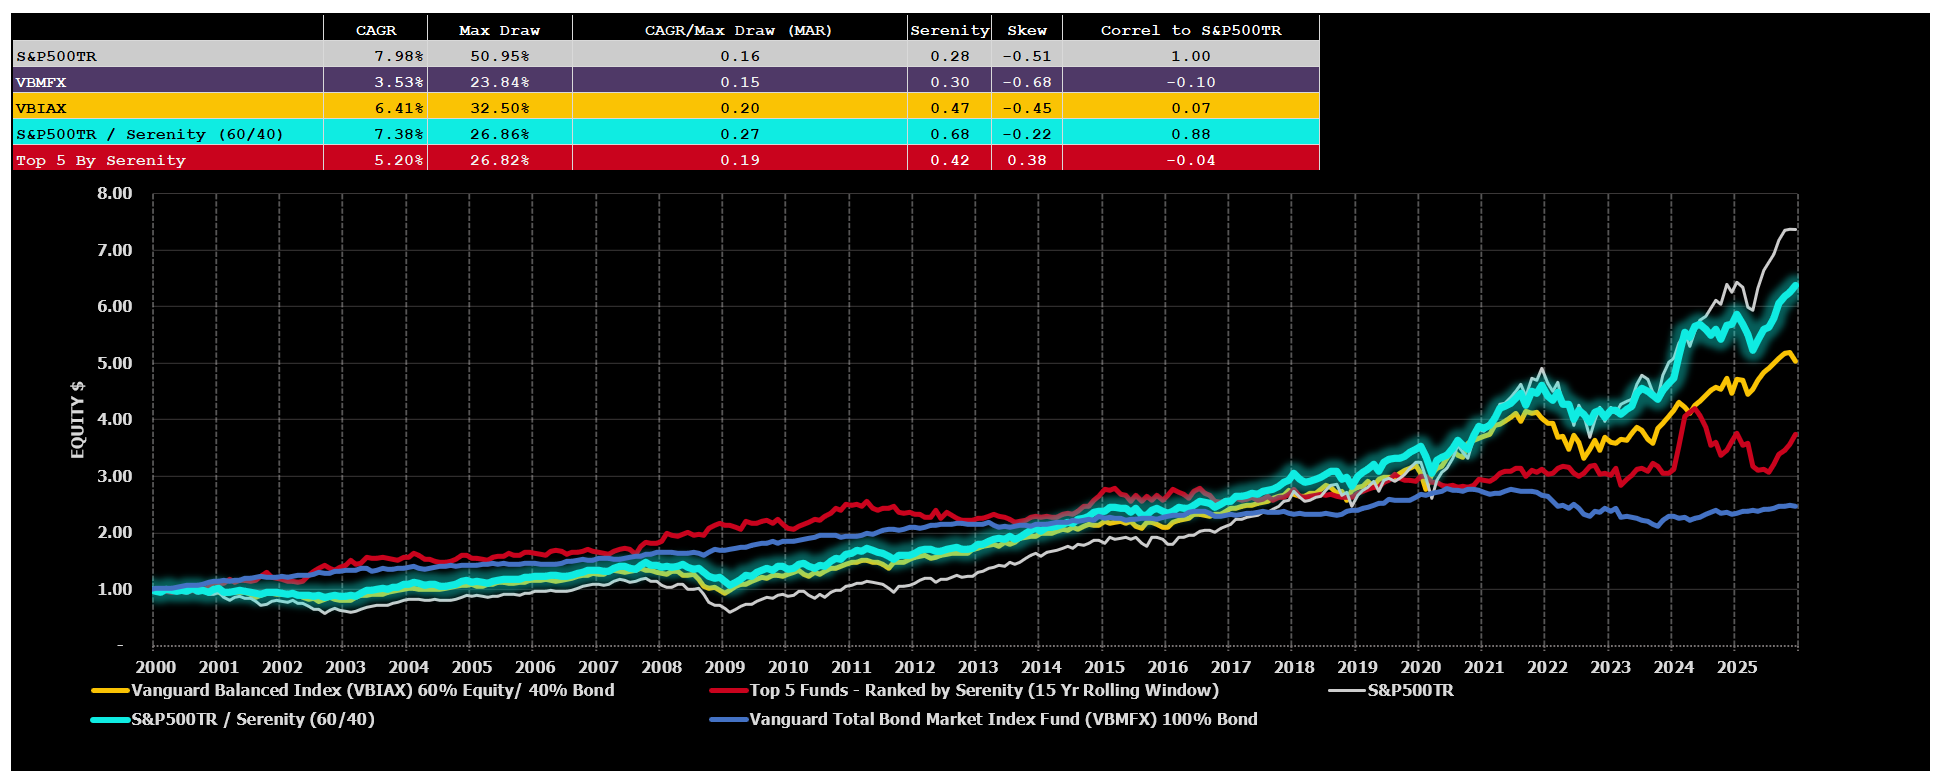
Chart 21 below showcases the comparative performance results for the period 1 January 2000 to the end of last month:
- A 100% investment in the S&P500TR portfolio;
- A 100% investment in the VBMFX which is a proxy for the bond market;
- A 100% investment in the VBIAX which is a suitable proxy for the classic 60% Equity/40% Bond portfolio;
- A 100% investment in a 60% S&P500TR 40% Serenity portfolio; and
- A 100% investment in the Serenity Portfolio.

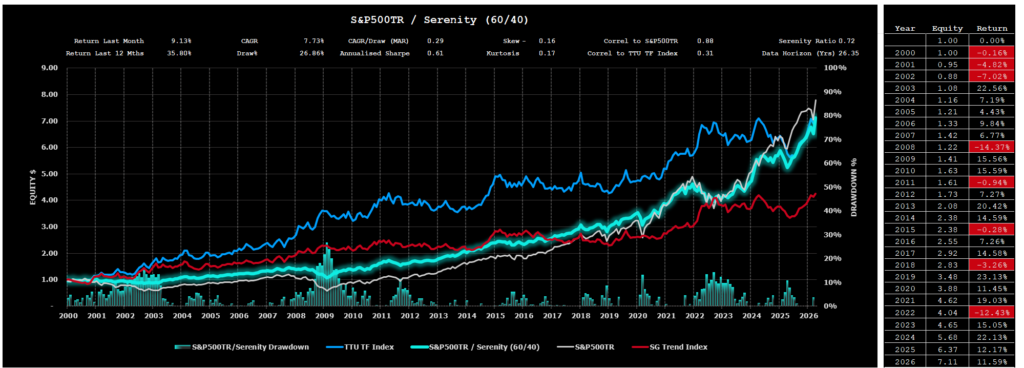
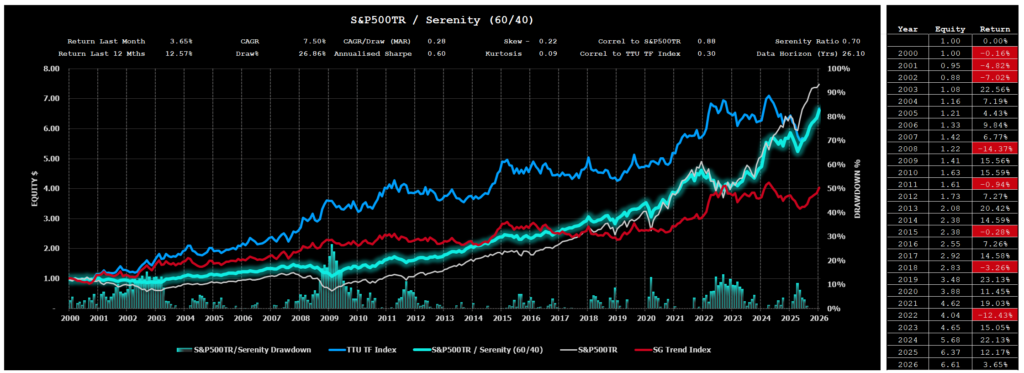
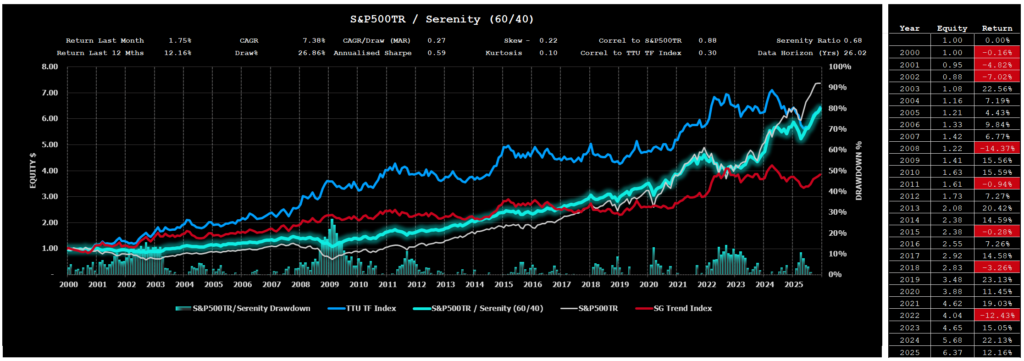
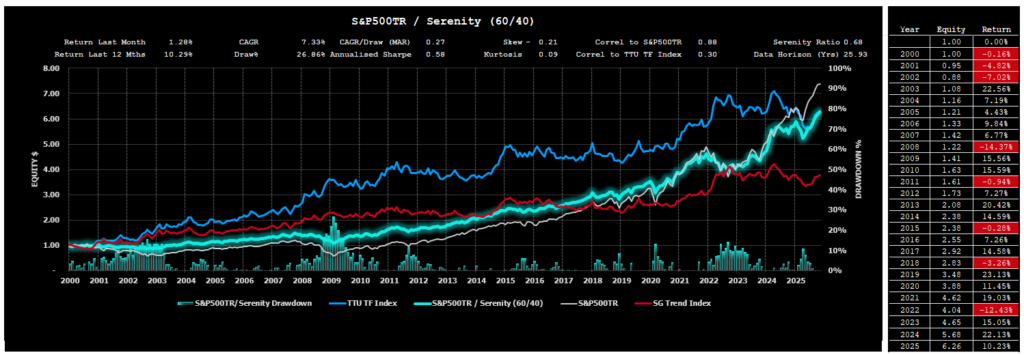
The comparison above shows the historical behaviour of the alternative allocations, including the 60 percent S&P 500 Total Return / 40 percent Serenity composite. The relevant observation is not simply the return number. It is the combination of compounding, drawdown and a return stream whose long-run drivers have been materially different from equities.
Chart 16 looks more closely at the historical performance of that alternative 60/40 construction.
Important Disclaimers
This document is directly solely to Accredited Investors, Qualified Eligible Participants, Qualified Clients and Qualified Purchasers. No investment decision should be made until prospective investors have read the detailed information in the fund offering documents of any manager mentioned in this document. This document is furnished on a confidential basis only for the use of the recipient and only for discussion purposes and is subject to amendment This document is neither advice nor a recommendation to enter into any transaction. This document is not an offer to buy or sell, nor a solicitation of an offer to buy or sell, any security or other financial instrument. This presentation is based on information obtained from sources that TopTradersUnplugged (“TTU”) (“considers to be reliable however, TTU makes no representation as to, and accepts no responsibility or liability for, the accuracy or completeness of the information. TTU has not independently verified third party manager or benchmark information, does not represent it as accurate, true or complete, makes no warranty, express or implied regarding it and shall not be liable for any losses, damages, costs or expenses relating to its adequacy, accuracy, truth, completeness or use.
All projections, valuations, and statistical analyses are provided to assist the recipient in the evaluation of the matters described herein. Such projections, valuations and analyses may be based on subjective assessments and assumptions and may use one among many alternative methodologies that produce different results accordingly, such projections, valuations and statistical analyses should not be viewed as facts and should not be relied upon as an accurate prediction of future events. There is no guarantee that any targeted performance will be achieved Commodity trading involves substantial risk of loss and may not be suitable for everyone
TTU is not and does not purport to be an advisor as to legal, taxation, accounting, financial or regulatory matters in any jurisdiction. The recipient should independently evaluate and judge the matters referred to herein. TTU does not provide advice or recommendations regarding an investor’s decision to allocate to funds or accounts managed by any manager (“or to maintain or sell investments in funds or accounts managed by any manager, and no fiduciary relationship under ERISA is created by the investor investing in funds or accounts managed by any manager, or through any communication between TTU and the investor
In reviewing this document, it should be understood that the past performance results of any asset class, or any investment or trading program set forth herein, are not necessarily indicative of any future results that may be achieved in connection with any transaction. Any persons subscribing for an investment must be able to bear the risks involved and must meet the suitability requirements relating to such investment. Some or all alternative investment programs discussed herein may not be suitable for certain investors This document is directed only to persons having professional experience in matters relating to investments. Any investment or investment activity to which this document relates is available only to such investment professionals. Persons who do not have professional experience in matters relating to investments should not rely upon this document.
This document and its contents are proprietary information of TTU and may not be reproduced or otherwise disseminated in whole or in part without TTU’s prior written consent.
This document contains simulated or hypothetical performance results that have certain inherent limitations AND SHOULD BE VIEWED FOR ILLUSTRATIVE PURPOSES. Unlike the results shown in an actual performance record, these results do not represent actual trading. HYPOTHETICAL PERFORMANCE RESULTS HAVE MANY INHERENT LIMITATIONS, SOME OF WHICH ARE DESCRIBED BELOW. NO REPRESENTATION IS BEING MADE THAT ANY ACCOUNT WILL OR IS LIKELY TO ACHIEVE PROFITS OR LOSSES SIMILAR TO THOSE SHOWN IN FACT, THERE ARE FREQUENTLY SHARP DIFFERENCES BETWEEN HYPOTHETICAL PERFORMANCE RESULTS AND THE ACTUAL RESULTS SUBSEQUENTLY ACHIEVED BY ANY PARTICULAR INVESTMENT ACCOUNT.
ONE OF THE LIMITATIONS OF HYPOTHETICAL PERFORMANCE RESULTS IS THAT THEY ARE GENERALLY PREPARED WITH THE BENEFIT OF HINDSIGHT IN ADDITION, HYPOTHETICAL TRADING DOES NOT INVOLVE FINANCIAL RISK, AND NO HYPOTHETICAL TRADING RECORD CAN COMPLETELY ACCOUNT FOR THE IMPACT OF FINANCIAL RISK IN ACTUAL TRADING FOR EXAMPLE, THE ABILITY TO WITHSTAND LOSSES OR TO ADHERE TO A PARTICULAR TRADING PROGRAM OR OTHER ASSET.
There are numerous other factors related to the markets in general or to the implementation of any specific trading program which cannot be fully accounted for in the preparation of hypothetical performance results and all of which can adversely affect actual trading results. No representation is being made that any investment will or is likely to achieve profits or losses similar to those being shown.