


Trend Following: Week in Review - June 26, 2026

"Risk-Off Rotation: the Petroleum Complex and Metals Lead a Broad Decline, the Equity Uptrend Pauses Near Records, and the Barometer Firms to 55% at the Favourable Boundary as the SG Trend Index Slips"
This Week in Trend – 26 June 2026
Welcome to This Week in Trend, your weekly view into the evolving structure of global futures markets and the behaviour of systematic trend following. This edition covers conditions through the close of US markets on Friday, 26 June 2026.
The week turned lower across most of the board, the declines led by the petroleum complex and the metals while the long equity uptrend paused near record territory. Energy was among the heaviest sectors, Crude Oil Brent down 10.65% and Crude Oil WTI 8.73% as the petroleum band extended its breakdown, and Metals was weakest of all at -5.54%, Silver off 10.63% as the precious complex deepened its pullback. The equity indices gave back ground after last week’s broad advance, averaging -1.63% as the Nasdaq 100 fell 4.40% and the Nikkei 225 3.21% from records, while the VIX firmed 3.06% off its lows. Against the weakness, Cocoa surged 20.25% for a second strong week and Rough Rice rose 8.32%, the two largest gains on the board. Contract-level breadth held at 19 of 49 contracts higher, with 30 lower and none unchanged, against 19 higher, 28 lower and 2 unchanged the week before.
Inside the complex the leadership sat almost entirely on the downside. Energy carried lower as the petroleum complex extended a decline now in its third week, with only Natural Gas firmer at +0.28% and Heating Oil higher at +2.10% against the move. Metals eased across the board on the precious side, Silver, Palladium and Platinum all down sharply while Copper held near the top of its range despite a 3.75% slip. The equity indices split as they paused, the Nasdaq 100 and the Nikkei 225 pulling back hardest from records while the DJIA firmed 0.39% and the Russell 2000 0.75%. Soft Commodities led the few gains, Cocoa’s 20.25% surge carrying the sector average to +1.96% even as Orange Juice fell 6.74%, and Grains firmed on a sharp bounce in Rough Rice. The dollar firmed again, the USD index up 0.51% as the only gainer in its basket, Bonds rose across the curve with the long end leading, and Bitcoin extended its decline, slipping 4.91%.
Trend Indicators: Barometer Firms to 55% at the Favourable Boundary, SG Trend Index Slips

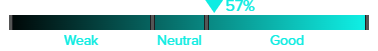
TTU Trend Barometer: 55%, up from 45% last week, with the overall trend strength classification moving from Neutral up to Strong as the reading reached the 55% threshold, the line where Neutral gives way to a favourable environment. The 10-day rate of change reads Rising Weakly, firming from last week’s Falling Weakly pace as the weekly level rose. The five-week sequence now reads 32, 43, 43, 45, 55: the reading rose 10 points this week, lifting from the Neutral band it had held for the prior three weeks up to the favourable boundary.
The 10-point rise came as trend strength built on the downside rather than through a broad advance. The petroleum complex extended its breakdown, the precious metals deepened their decline, the equity indices rolled over from record territory and Bitcoin pressed lower, a set of sharp, persistent moves that lifted the share of markets generating medium-to-strong trends. The barometer measures whether markets are trending, not whether those trends match the ones a portfolio already holds or whether they point higher, so the rise reflects more markets moving with force, most of them lower, rather than any broadening of gains. Cocoa and Rough Rice ran the other way with large counter-trend bounces, and a handful of currencies and grains chopped, but on balance the count of strongly trending markets rose. The Rising Weakly rate of change runs with the weekly level this week rather than against it, the 10-day momentum firming only weakly alongside the rise, so the near-term read points mildly higher: at 55% the level now sits right at the favourable boundary rather than pressing against the Neutral edge from below.

SG Trend Index: -1.25% month to date for June and +9.03% year to date as of 26 June, compared with -0.80% MTD and +9.53% YTD at last week’s close. The index gave back roughly 0.50 of a percentage point on the year, a deeper move than the 0.10 of a point it shed the week before, and the June month-to-date figure extended to -1.25%. The give-back fits the week’s shape: the equity indices pulled back from records and the precious metals deepened their decline, moves that would have cost books positioned long in those trends, while the largest gains, Cocoa and Rough Rice, came as counter-trend bounces that a continuation book would not have fully held. The persistent short in the petroleum complex worked the other way and cushioned the net. This week the barometer firmed while the index slipped, the two pulling apart: the share of markets in medium-to-strong trends rose 10 points even as trend-follower performance edged lower. Rising trend strength sitting alongside a softer index is the divergence to note, and this week it is clear rather than mild, much of the new strength pointing in directions a long-biased continuation book was not carrying.
Weekly Asset Class Snapshot

Sector averages are simple equal-weighted means of the constituent contracts in each sector.
Equity Index (-1.63% | prev +2.15%)

The advance paused after last week’s clean sweep, only two of seven contracts higher. The Russell 2000 led at +0.75% and the DJIA rose 0.39%, while the Nasdaq 100 fell 4.40%, the Nikkei 225 3.21%, the S&P 500 2.23%, the DAX 1.43% and the Euro Stoxx 50 1.29%. The weekly charts keep the multi-month uptrend intact, the US indices and the Nikkei 225 still at or near record territory, so the week reads as a pullback from the highs rather than a turn. The split is worth noting: the megacap and Japanese indices gave back the most while the Dow and the small caps firmed, a rotation within the sector as it paused rather than a uniform retreat.
Energy (-3.18% | prev -3.65%)

The petroleum complex extended its decline for a third week, leaving Energy among the heaviest sectors on the board. Crude Oil Brent dropped 10.65% and Crude Oil WTI 8.73%, with Gasoline RBOB down 1.54% and Ethanol 0.53%, while Heating Oil rose 2.10% and Natural Gas 0.28% against the move. The weekly charts show crude pressing toward the lower part of its range as the spring spike unwinds in full rather than stabilising. The decline reads as a continuation lower, a move that has now run for three weeks and that a short position would have carried, with Heating Oil and Natural Gas the two contracts pulling the other way.
Metals (-5.54% | prev -2.48%)

The complex was the weakest sector on the board, all five contracts lower and the precious side leading. Silver fell 10.63%, with Palladium down 5.33%, Platinum 4.45%, Copper 3.75% and Gold 3.52%, the precious metals carrying the bulk of the decline. The weekly charts show the precious complex deepening the pullback that began in the spring: Silver has retraced a large part of its advance and Gold sits well off its winter high, so the move is starting to read as a sustained decline from the highs rather than a shallow pause, though both remain up on the year. Copper is the exception, holding near the top of its range despite the down week, its uptrend still the firmest in the sector.
Soft Commodities (+1.96% | prev +3.25%)

The sector led the board’s few gains, carried almost single-handedly by Cocoa. Cocoa surged 20.25%, with Sugar up 2.69% and Coffee 2.02%, while Lumber fell 2.34%, Cotton 4.13% and Orange Juice 6.74%. Three of six contracts rose, but Cocoa’s outsized move set the average. The weekly charts show Cocoa recovering a larger share of its long decline for a second week, a bounce now sizeable enough that it is beginning to look like more than a counter-trend pop, while Coffee and Sugar firmed modestly off lower levels. Orange Juice ran the other way, pressing toward new lows for its move, and Cotton and Lumber eased from firmer ground, so the split that has run through this sector held, with Cocoa carrying the weight on the upside.
Grains (+0.47% | prev -0.88%)

The sector firmed, the split flipping from the week before as the oilseeds and rice led and the cereals lagged. Rough Rice surged 8.32%, the largest move in the sector, with Soybean Oil up 2.03%, Canola 1.12%, Soybean Meal 0.96% and Soybeans 0.73%; on the other side Oats fell 4.63%, Wheat 3.95% and Corn 0.82%. The weekly charts show Rough Rice bouncing sharply off the lower end of a long decline, while the oilseeds firmed back toward the upper part of their ranges and Wheat and Oats eased after recent gains. The sector average of +0.47% sits on top of that two-way split, five contracts higher and three lower, Rough Rice and the firmer oilseeds outweighing the softer cereals.
Meats (+0.01% | prev +0.63%)

The sector finished essentially flat, the firmer Feeder Cattle offset by small declines elsewhere. Feeder Cattle rose 0.89%, while Live Cattle eased 0.32% and Lean Hogs 0.54%, the split that runs through this sector holding but tighter than the week before. The weekly charts keep both cattle contracts in the uptrends they have traced for months, Feeder Cattle near the top of its range, while Lean Hogs continued the decline that has pulled it well off its earlier highs. The sector average of +0.01% reflects the near balance between the firmer feeder cattle and the modest drag from live cattle and hogs, a quiet week that sits with the established trends in each.
Bonds (+0.47% | prev -0.07%)

The complex firmed across the curve, the long end leading. The 30 Year Bond rose 0.69%, the 10 Year Note 0.58%, the 5 Year Note 0.41% and the 2 Year Note 0.18%, a clean gradient with the long end firmer than the front and the sector average at +0.47%. That reverses the near-flat, mixed reading of the week before. The weekly charts show prices bouncing modestly off the lower part of the range the contracts have traced through the spring, a firming across the curve rather than a decisive turn, with the long end recovering the most.
Currencies (-0.64% | prev -0.86%)

The dollar firmed again while the non-dollar majors softened broadly, a continuation of the week before. The USD index rose 0.51%, the only gainer in the basket, while NZD led the decliners at -2.03%, with AUD down 1.71%, EUR 0.67%, CHF 0.66%, CAD 0.40%, JPY 0.10% and GBP 0.03%, leaving the sector average at -0.64%. The commodity-linked dollars took the heaviest losses, NZD and AUD the weakest, while GBP and JPY finished close to flat. The weekly charts show the USD index extending the recovery that began earlier in the spring, firming toward the upper part of its recent range, the majors giving back ground across the basket rather than through any single cross.
Volatility, Crypto: The VIX rose 3.06% as the equity indices pulled back from records and implied volatility firmed off its recent lows, the index ticking up after weeks of drifting lower while equities climbed. Bitcoin fell 4.91%, extending the decline that has run for months and pressing toward the lower part of its range. The weekly chart keeps Bitcoin inside that downtrend, the contract tracking its own path rather than the equity tape: where the indices still sit near record territory despite this week’s pause, Bitcoin remains well below its late-2025 high and closer to its lows for the move. The weekly drop reads as a continuation of the established decline rather than a fresh break, the contract pressing lower within a trend already in place.
Top Movers

Top five up and top five down by single-week percentage move.
The two lists run in opposite directions by sector. The upside is scattered rather than concentrated this week, Cocoa and Sugar from Soft Commodities, Rough Rice from the grains, the VIX as volatility firmed, and Heating Oil the lone gainer in an otherwise falling energy complex. The downside is concentrated in Energy and Metals: Crude Oil Brent and Crude Oil WTI from the petroleum band and Silver and Palladium from the precious metals take four of the five places, joined by Orange Juice from the softs. Cocoa’s 20.25% gain was the largest single move in the dataset in either direction, a second strong week recovering a long decline, while Crude Oil Brent’s 10.65% drop led the downside as the petroleum band extended its breakdown and Silver fell almost as far. The contrast is the week in miniature: a handful of scattered, largely counter-trend gains against a heavy, persistent decline clustered in energy and the metals.
Portfolio View
The week was harder on continuation books than the prior one, and it cost more. The clearest directional contributor was again Energy: short exposure in the petroleum band was rewarded as crude extended its breakdown into a third week, and short crypto gained as Bitcoin slipped 4.91%. Against those, the equity indices pulled back from records, so long positioning that had ridden the uptrend gave back ground, and the precious metals deepened their decline, trimming long exposure that had carried the year’s advance, Silver and Palladium the heaviest. The sharp bounces in Cocoa and Rough Rice ran counter to the declines those contracts had been tracing, so any short held against them was hit, though Cocoa’s two-week surge is now large enough that a trend system may be turning long into it. The firmer dollar helped books positioned with the USD recovery. The net was a give-back of roughly 0.50 of a point on the year, deeper than the prior week, as the losses on the long equity and metals side outweighed the gains from the established energy and crypto shorts. The week favoured books holding short trends over those still positioned long for the equity advance.
Final Reflections
The defining feature of the week was a turn lower that lifted trend strength even as it cost trend followers. The heaviest, most persistent moves sat on the downside, the petroleum complex and the metals carrying lower and the long equity uptrend pausing from records, while the largest gains, Cocoa and Rough Rice, came as counter-trend bounces. The TTU Barometer firmed to 55%, reaching the favourable boundary after three weeks in Neutral, yet the SG Trend Index gave back roughly 0.50 of a point to +9.03% year to date and contract-level breadth stayed negative at 19 of 49 contracts higher against 30 lower, none unchanged. The market offered more trend strength than it did trend-follower reward this week: the new strength was real, but much of it pointed in directions a long-biased book was not yet carrying.
1. The barometer firmed even as most markets fell, a reminder that it measures the strength and persistence of trends, not the number of markets closing higher.
The five-week sequence (32, 43, 43, 45, 55) firmed to 55% this week, up 10 points and lifting from the Neutral band it had held for three weeks up to the favourable boundary, the 55% line where Neutral gives way to a favourable environment. It rose even as breadth stayed negative, just 19 of 49 contracts higher against 30 lower. The two measure different things: the barometer counts how strongly and persistently markets are trending, in either direction, not how many close higher, so a week with more decliners but sharper, more durable moves, Energy extending lower, the precious metals deepening their decline, the equity indices rolling over from records and Bitcoin pressing on, can lift the share of markets in medium-to-strong trends. The 10-day rate of change reads Rising Weakly, a modestly firmer momentum reading running with the higher weekly level, so the near-term tilt points mildly higher, with the level at 55% now sitting right at the favourable boundary.
2. The week’s largest gains were counter-trend, while its largest losses ran with developing or established trends, a distinction that shapes what is likely to persist.
Cocoa and Rough Rice produced the two biggest gains on the board, but both came against multi-month declines, counter-trend bounces rather than settled uptrends, though Cocoa’s second strong week is starting to look like more than a one-week pop. The crude complex and Silver produced the largest losses, and those moves ran with trends already in place or building: Energy has carried lower for three weeks, and the precious metals decline is deepening from the highs into something closer to a sustained move. For a trend follower the distinction is the point: a counter-trend bounce is the move most likely to fade, while an established or developing downtrend is the one more likely to continue. The clearest, most persistent trends this week sat on the downside, and that risk-off tilt, more than the breadth count, is what the week leaves behind.
One question frames the week ahead: Does the risk-off turn harden into a sustained trend as the equity indices roll over and the petroleum complex and metals extend lower, or does the long equity uptrend reassert itself and leave this week as a brief pause within it?

List of Resources used in the Week in Review
Important Disclaimers
This document is directly solely to Accredited Investors, Qualified Eligible Participants, Qualified Clients and Qualified Purchasers. No investment decision should be made until prospective investors have read the detailed information in the fund offering documents of any manager mentioned in this document. This document is furnished on a confidential basis only for the use of the recipient and only for discussion purposes and is subject to amendment This document is neither advice nor a recommendation to enter into any transaction. This document is not an offer to buy or sell, nor a solicitation of an offer to buy or sell, any security or other financial instrument. This presentation is based on information obtained from sources that TopTradersUnplugged (“TTU”) (“considers to be reliable however, TTU makes no representation as to, and accepts no responsibility or liability for, the accuracy or completeness of the information. TTU has not independently verified third party manager or benchmark information, does not represent it as accurate, true or complete, makes no warranty, express or implied regarding it and shall not be liable for any losses, damages, costs or expenses relating to its adequacy, accuracy, truth, completeness or use.
All projections, valuations, and statistical analyses are provided to assist the recipient in the evaluation of the matters described herein. Such projections, valuations and analyses may be based on subjective assessments and assumptions and may use one among many alternative methodologies that produce different results accordingly, such projections, valuations and statistical analyses should not be viewed as facts and should not be relied upon as an accurate prediction of future events. There is no guarantee that any targeted performance will be achieved Commodity trading involves substantial risk of loss and may not be suitable for everyone
TTU is not and does not purport to be an advisor as to legal, taxation, accounting, financial or regulatory matters in any jurisdiction. The recipient should independently evaluate and judge the matters referred to herein. TTU does not provide advice or recommendations regarding an investor’s decision to allocate to funds or accounts managed by any manager (“or to maintain or sell investments in funds or accounts managed by any manager, and no fiduciary relationship under ERISA is created by the investor investing in funds or accounts managed by any manager, or through any communication between TTU and the investor
In reviewing this document, it should be understood that the past performance results of any asset class, or any investment or trading program set forth herein, are not necessarily indicative of any future results that may be achieved in connection with any transaction. Any persons subscribing for an investment must be able to bear the risks involved and must meet the suitability requirements relating to such investment. Some or all alternative investment programs discussed herein may not be suitable for certain investors This document is directed only to persons having professional experience in matters relating to investments. Any investment or investment activity to which this document relates is available only to such investment professionals. Persons who do not have professional experience in matters relating to investments should not rely upon this document.
This document and its contents are proprietary information of TTU and may not be reproduced or otherwise disseminated in whole or in part without TTU’s prior written consent.
This document contains simulated or hypothetical performance results that have certain inherent limitations AND SHOULD BE VIEWED FOR ILLUSTRATIVE PURPOSES. Unlike the results shown in an actual performance record, these results do not represent actual trading. HYPOTHETICAL PERFORMANCE RESULTS HAVE MANY INHERENT LIMITATIONS, SOME OF WHICH ARE DESCRIBED BELOW. NO REPRESENTATION IS BEING MADE THAT ANY ACCOUNT WILL OR IS LIKELY TO ACHIEVE PROFITS OR LOSSES SIMILAR TO THOSE SHOWN IN FACT, THERE ARE FREQUENTLY SHARP DIFFERENCES BETWEEN HYPOTHETICAL PERFORMANCE RESULTS AND THE ACTUAL RESULTS SUBSEQUENTLY ACHIEVED BY ANY PARTICULAR INVESTMENT ACCOUNT.
ONE OF THE LIMITATIONS OF HYPOTHETICAL PERFORMANCE RESULTS IS THAT THEY ARE GENERALLY PREPARED WITH THE BENEFIT OF HINDSIGHT IN ADDITION, HYPOTHETICAL TRADING DOES NOT INVOLVE FINANCIAL RISK, AND NO HYPOTHETICAL TRADING RECORD CAN COMPLETELY ACCOUNT FOR THE IMPACT OF FINANCIAL RISK IN ACTUAL TRADING FOR EXAMPLE, THE ABILITY TO WITHSTAND LOSSES OR TO ADHERE TO A PARTICULAR TRADING PROGRAM OR OTHER ASSET.
There are numerous other factors related to the markets in general or to the implementation of any specific trading program which cannot be fully accounted for in the preparation of hypothetical performance results and all of which can adversely affect actual trading results. No representation is being made that any investment will or is likely to achieve profits or losses similar to those being shown.
Most Comprehensive Guide to the Best Investment Books of All Time

Most Comprehensive Guide to the Best Investment Books of All Time
Get the most comprehensive guide to over 600 of the BEST investment books, with insights, and learn from some of the wisest and most accomplished investors in the world. A collection of MUST READ books carefully selected for you. Get it now absolutely FREE!
Get Your FREE Guide HERE!