


Trend Following: Week in Review - November 13, 2026
“Dollar Broke Higher, Bonds Turned Lower. Trend Strength Jumped to 52%.”
This Week in Trend – 13 November 2026
Welcome to This Week in Trend, our weekly examination of the evolving structure of global futures markets and what that structure means for systematic trend followers. This edition covers market conditions through the US close on Friday, 13 November 2026. Market returns, the SG Trend Index and the TTU Trend Barometer reading are all as at that close.
Market breadth widened for a second week, and trend-following returns recovered with it. Twenty-three of 49 futures contracts finished higher, up from 17, the TTU Trend Barometer rose from 39% to 52%, a 13 point jump that carried it back above the 40% line and to within 3 points of the 55% threshold, and the SG Trend Index advanced from +9.74% to +11.25% year to date. For the first time in the five-week sequence, the Barometer and the index rose together. Two reversals set the tone. The US Dollar Index broke above its range to the highest level on its chart while the rest of the Currencies basket fell, and all four Bonds maturities turned lower, ending a five-week bounce that never produced a higher high. Of the ten largest moves on the board, six ran with the structures beneath them. Trend prevalence and portfolio returns rose together this week.
Last week’s report closed by asking whether the Barometer could recover the single point that separated 39% from the 40% line or would slip back toward 36%, and whether the 10-day rate of change would turn up. It recovered that point and twelve more, rising to 52%, and the 10-day rate of change turned from Falling Weakly to Rising Moderately. Five other questions were left open. Would the declines in WTI and Brent extend toward the lower parts of their ranges, or would the advances resume? Would Gold’s rebound above its July low near 4,000 become a higher high, or would the decline resume? Would the VIX hold above its range, and the Nikkei 225 below its own? Would the bounce in Bonds become a higher high? And how would the SG Trend Index build on its -4.07% start to November? WTI and Brent eased further, to near 88.9 and 96.3, with no sign yet of the advances resuming. Gold’s rebound did not hold: it fell back to near 3,887, below 4,000 and close to its late October low. The VIX fell back below 20 inside its range, and the Nikkei 225 recovered above 60,000, though it remains below its summer range. The bounce in Bonds ended without a higher high, with all four maturities lower. And the SG Trend Index recovered to -2.76% for the month.
Trend Indicators: Barometer Jumps to 52%, SG Trend Index Recovers
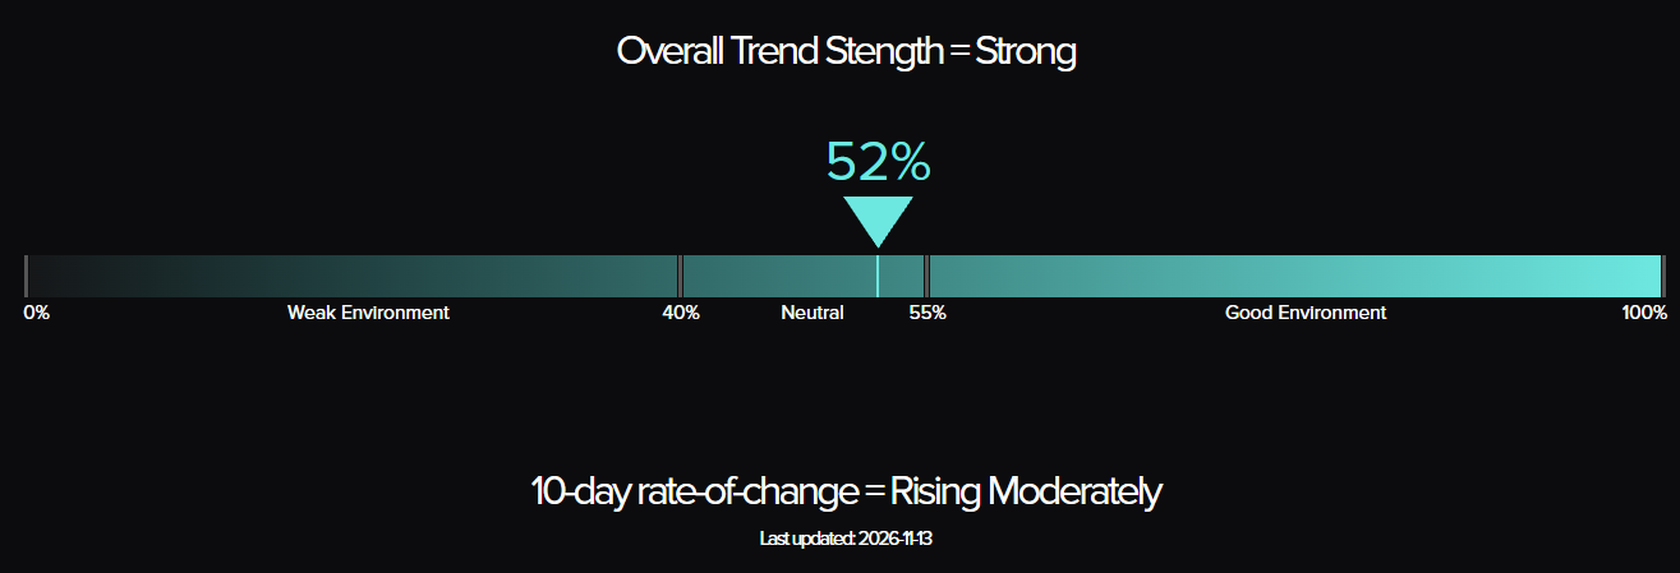
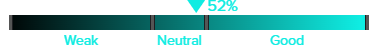
TTU Trend Barometer: 52%, up from 39% last week. TTU describes overall trend strength as Strong, up from Moderately Weak, and the reading has moved 12 points above the 40% line, out of the cold environment and into the Neutral band, 3 points below the 55% threshold for a favourable environment. The 10-day rate of change now reads Rising Moderately, compared with Falling Weakly a week ago, so TTU’s short-term measure has turned up. The five-week sequence, from 16 October to 13 November, now stands at 36, 41, 36, 39 and 52. The 13 point rise is close in size to the 14 point fall of 16 October, and it returns the reading to the 52% at which it stood on 2 October. The reading is 22 points above the late July low of 30% and 16 points above the 36% at which the sequence begins. The higher reading indicates that more markets met the Barometer’s medium-to-strong trend criteria. It does not, by itself, establish how trend-following portfolios performed or whether those trends were profitable to follow.
Set against the performance table, breadth and the reading rose together for a second week, while the moves themselves grew smaller. Twenty-three of 49 contracts rose, up from 17, and six of the ten categories in the snapshot fell, down from seven. The average absolute weekly move eased from 3.71% to 2.98%, and the spread between the largest gain and the largest loss narrowed from 29.70 to 27.59 percentage points, with Oats at one end and the VIX at the other. Without the VIX, the spread would be 17.22 points. The board was calmer than a week ago, and more of its movement followed existing structures. Breadth near the halfway mark alongside a much higher reading separates two counts that are easy to conflate: how many markets rose, and how many are trending. The Barometer measures the second, and a market trending lower is part of that count as much as one trending higher.
Because the reading counts trends rather than weighing weekly price changes, a week of smaller moves does not necessarily lower it, and this week the measured proportion of trending markets rose sharply even as the average move contracted. The ten largest moves on the board illustrate the mix without explaining the reading. Six ran with the structures beneath them, up from two of the eleven largest a week ago, when a tie for tenth place widened the group. Bitcoin fell below 70,000 inside the decline from above 120,000, Silver set another low, Gold fell back below 4,000 inside the decline from its late winter peak, Gasoline RBOB extended last week’s break below its range, Oats resumed its advance after four weeks of pullback, and the Nikkei 225 recovered toward the summer range of its advance. Three ran against: Natural Gas and Feeder Cattle rose inside their declines, and Lumber rebounded from below 500. The VIX, the largest move on the board, fell back inside the range it broke above a week ago. Outside the ten, the falls across the Currencies basket and in Bonds also ran with established structures, though a week of prices cannot confirm which markets entered the count.
The sector data is consistent with a trend environment that warmed sharply, with established structures reasserting themselves across several sectors. Running with their structures, the Dollar Index rose to a new high, EUR, CHF and NZD set new lows, CAD slipped back to its summer low near 0.70, all four Bonds maturities resumed their declines, Silver set another low, Gold fell back below 4,000, Bitcoin fell below 70,000, Rough Rice set another high, Oats and Soybean Meal resumed their advances, the DAX rose to a new high, and the other six equity indices lifted within the advances that have run since the spring. Running against them, Natural Gas rose inside its decline, all three Meats contracts bounced inside theirs, Lumber rebounded from its low, Corn and Wheat lifted slightly, Copper broke below its summer range against the advance it has held since last autumn, and AUD fell further below 0.70, deepening the break in its climb from last year’s lows. At 52%, the reading sits alongside a board on which established structures extended across Currencies, Bonds, the precious metals and the equity indices, while the bounces in Meats and the smaller agricultural markets ran against theirs.
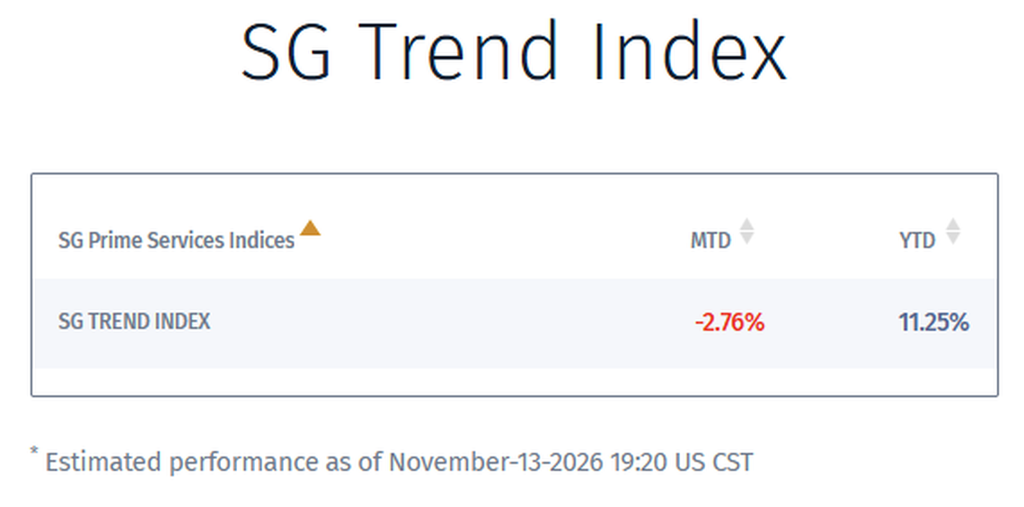
SG Trend Index: -2.76% month to date for November and +11.25% year to date as of 13 November, on SG’s estimated figure. The year-to-date figure has risen from +9.74% to +11.25%, a gain of 1.51 percentage points and the largest weekly gain in the five-week sequence, recovering close to three-tenths of last week’s 5.18 point decline. Set against the Barometer, the index rose with the reading, the first time in the sequence that both have risen in the same week. Over the last five weeks the Barometer has fallen 14, risen 5, fallen 5, risen 3 and risen 13, while the index has given back 1.17 percentage points, given back 0.66, added 0.61, given back 5.18 and added 1.51. The two moved in opposite directions in three of those five weeks. The Barometer counts trending markets, while the index records what institutional trend-following portfolios earned, and the two need not move together in any given week. The index’s recovery is consistent with an environment in which the dollar’s advance, the declines in Bonds, EUR and the precious metals, and the resumed advances in the equity indices ran with structures trend-following portfolios would typically have been following. Without the index’s underlying positions and return contributions, the precise sources of its improvement cannot be established. Across the five weekly changes since the 9 October close, the index has given back 4.89 percentage points to stand at +11.25% year to date.
Weekly Asset Class Snapshot
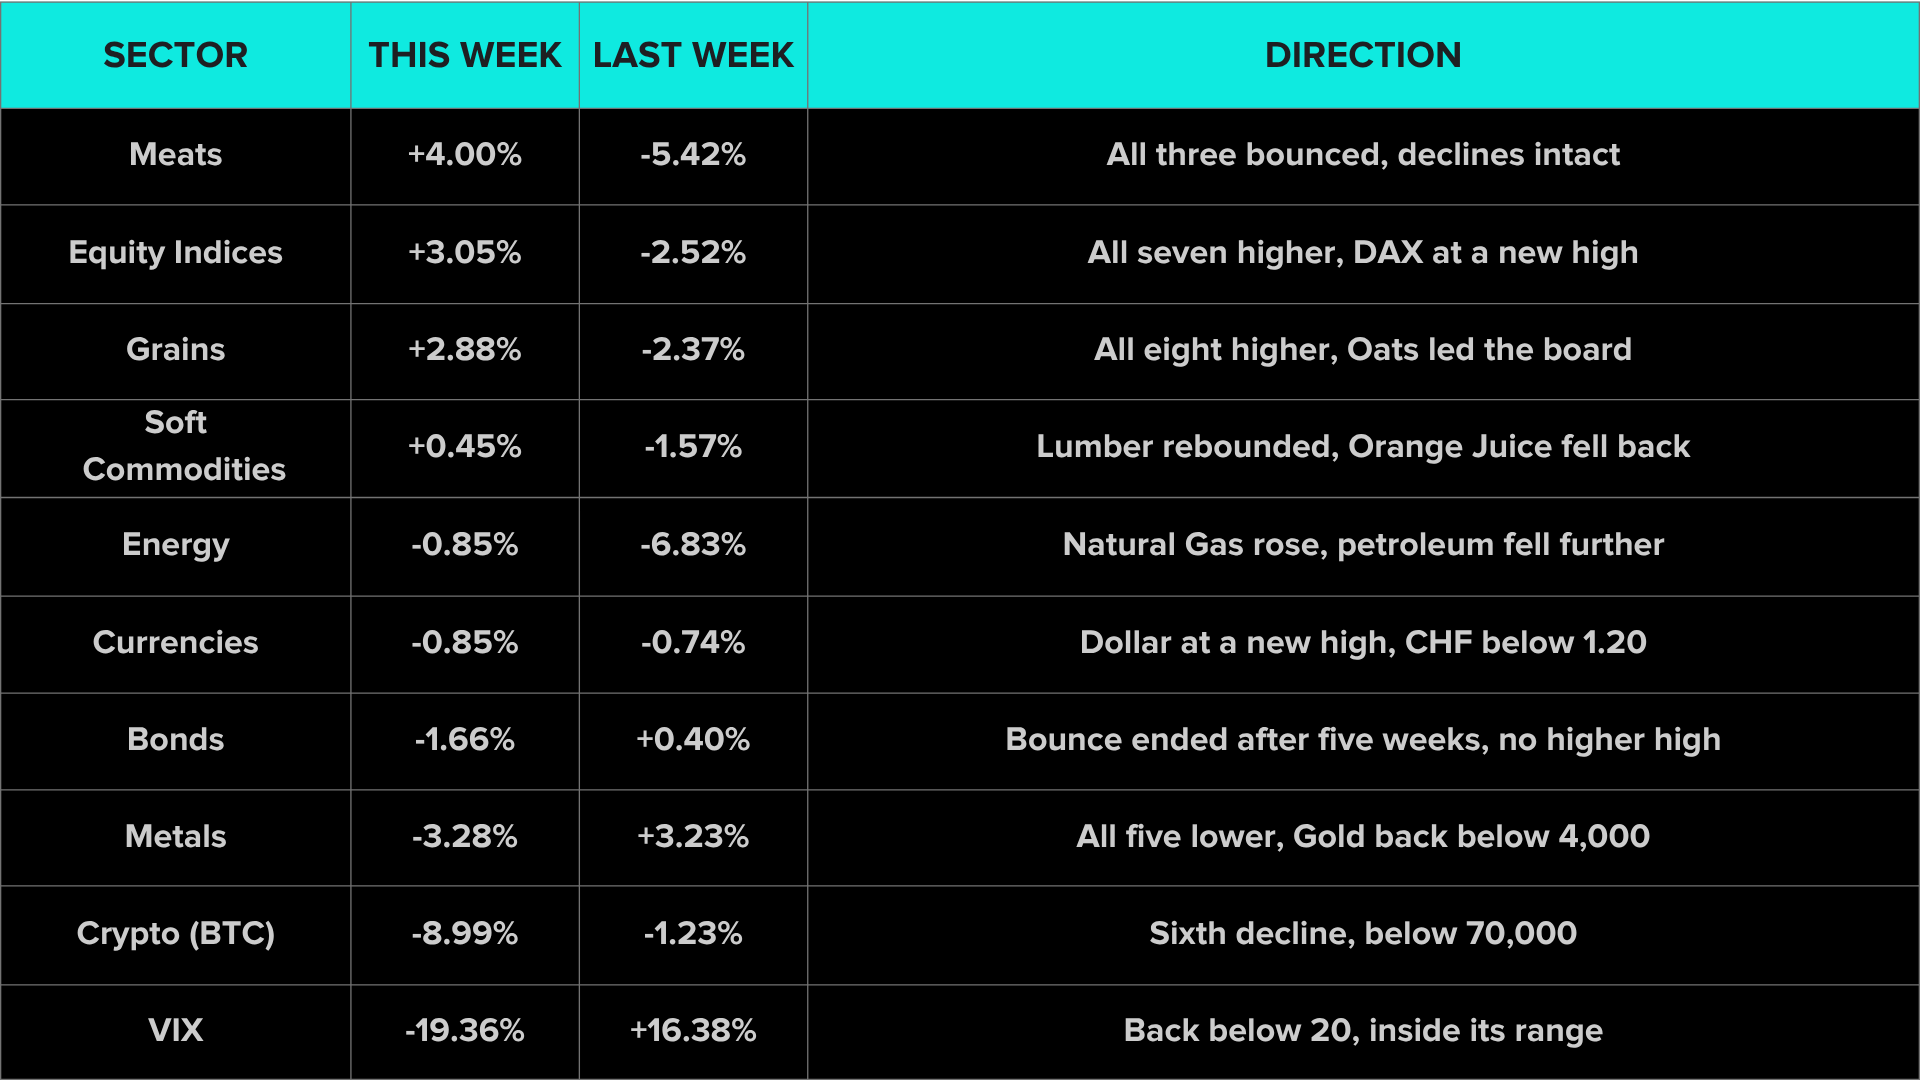
Sector averages are simple equal-weighted means of the constituent contracts in each sector.
Equity Indices (+3.05% | prev -2.52%)
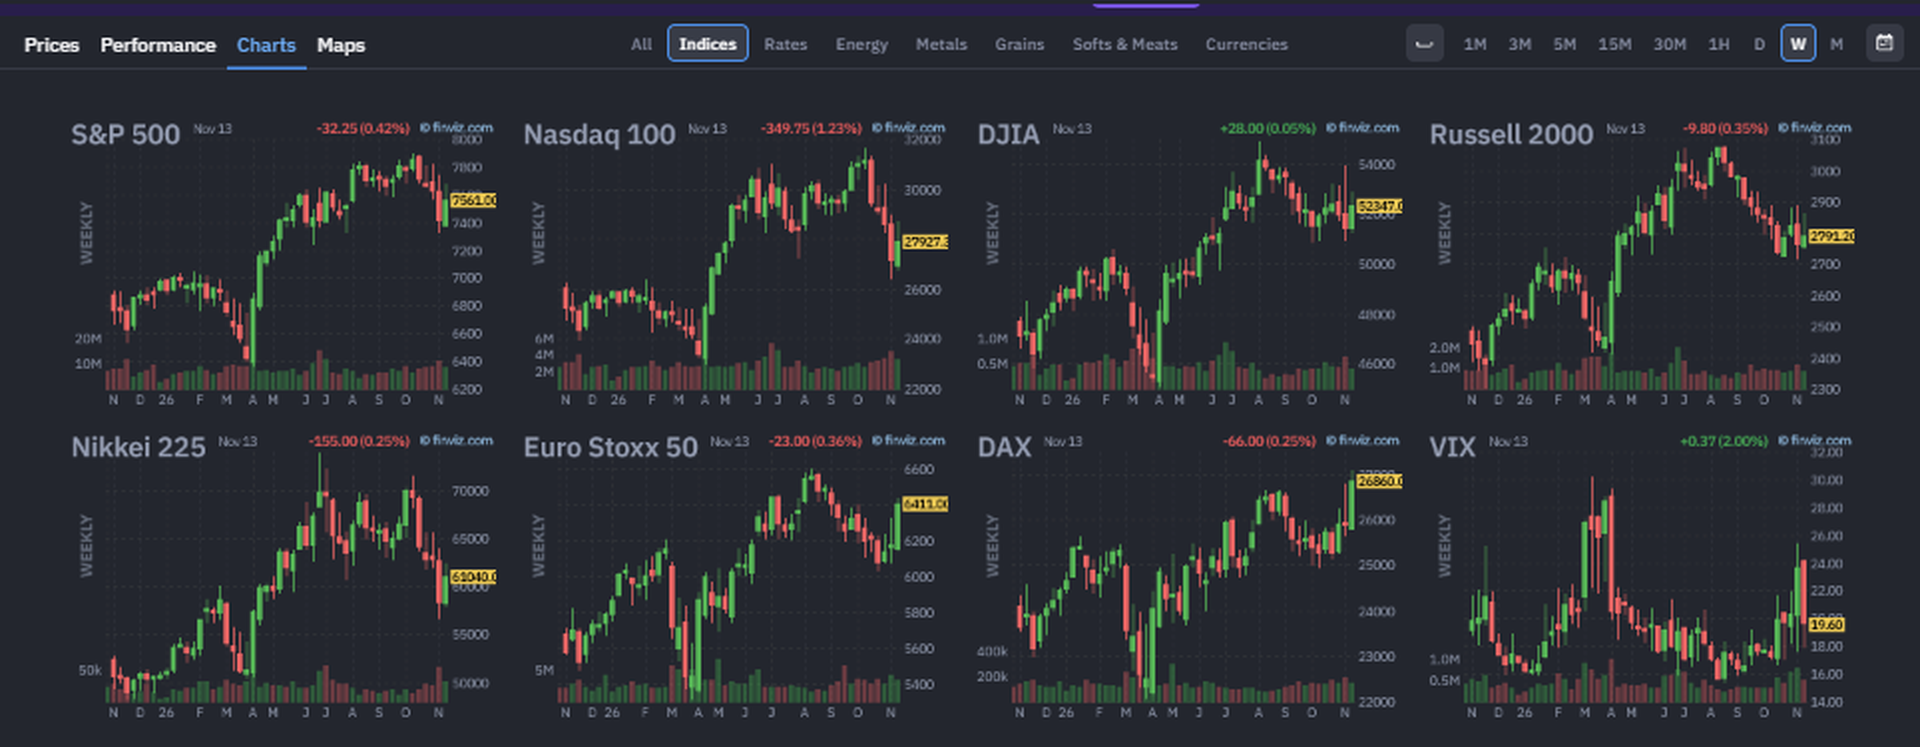
Equity Indices gained 3.05% with all seven contracts higher, reversing last week’s decline and finishing as the strongest sector on the board after Meats. The Nikkei 225 rose 4.85%, the eighth largest move on the board, the DAX 3.69%, Euro Stoxx 50 3.53%, the Nasdaq 100 3.51%, the S&P 500 2.45%, the DJIA 2.01% and the Russell 2000 1.34%. Last week Japan and US technology led a deepening pullback. This week they led the recovery, alongside Europe. The DAX near 26,860 rose above its August high to the highest level on its chart, and Euro Stoxx 50 near 6,410 climbed for a third week from the June levels to which its pullback had run, back toward its August high. The Nikkei 225 near 61,040 recovered above 60,000, though it remains below the summer range from which it fell last week. The Nasdaq 100 near 27,930 recovered part of last week’s fall, still well below its high near 31,500, and the S&P 500 near 7,560 moved back into the range it had held since July. The DJIA near 52,350 returned above 52,000, still under its August high near 54,000, and the Russell 2000 near 2,790 lifted from the lower part of its pullback from the summer high near 3,100. The advances that have run since the spring remain visible on all seven charts, and the DAX has now resumed its own, while the pullbacks in Japan and the US large caps have been interrupted rather than reversed.
Energy (-0.85% | prev -6.83%)
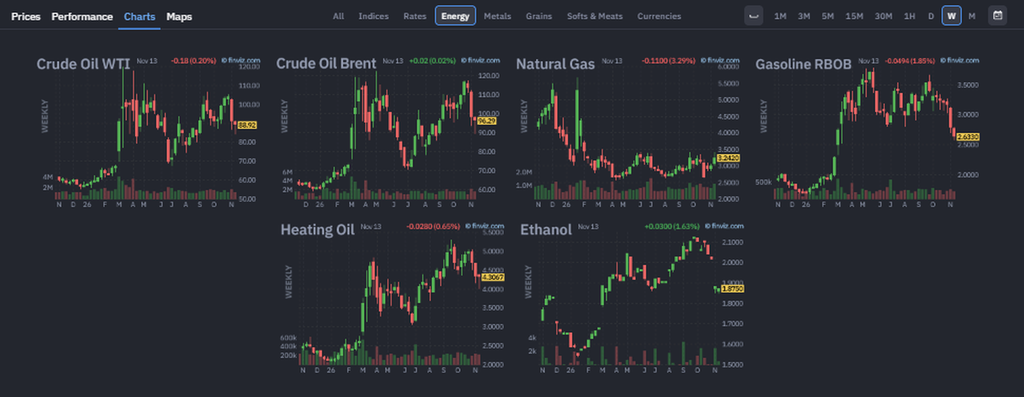
Energy fell 0.85% with one of six contracts higher, a fourth weekly decline and a much smaller one than last week’s. Natural Gas rose 7.74%, the fourth largest move on the board, while Ethanol fell 0.53%, Heating Oil 1.69%, Crude Oil WTI 2.50%, Crude Oil Brent 2.52% and Gasoline RBOB 5.59%, the fifth largest move. Without Natural Gas, the sector average would be close to -2.57%. WTI near 88.9 eased further below the middle of the range it has built since the spring, and Brent near 96.3 slipped again below 100. Gasoline RBOB near 2.63 extended last week’s break below its range, falling to the lowest level since the spring, and Heating Oil near 4.31 eased again from the area of its high. Ethanol eased slightly. Natural Gas near 3.24 rose to the upper part of the base it has held since the summer, a second weekly gain and a move against the decline that has run since February. Last week the petroleum contracts reversed sharply. This week they extended those falls at a slower pace, with no resumption of the advances, while Natural Gas again moved against its decline.
Metals (-3.28% | prev +3.23%)
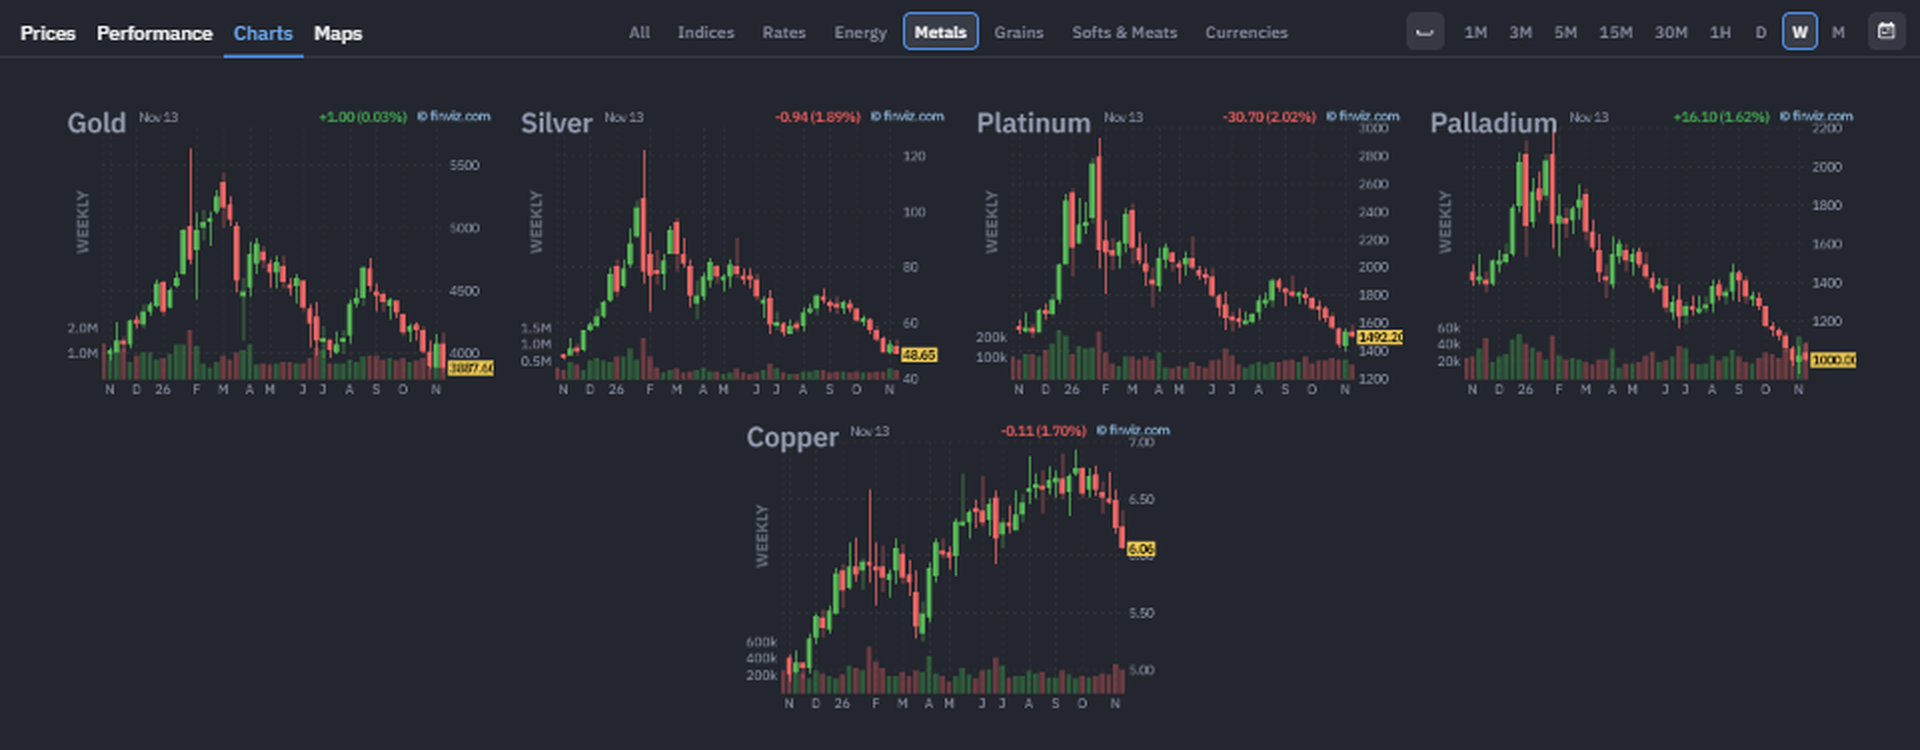
Metals fell 3.28% with all five contracts lower, giving back last week’s gain and finishing as the third weakest category on the board. Palladium fell 0.93%, Copper 2.36%, Platinum 3.07%, Gold 4.63% and Silver 5.43%, the sixth largest move on the board. Last week Gold reclaimed its July low near 4,000. This week it lost it again. Gold near 3,887 fell back below 4,000, close to its late October low, and Silver near 48.65 fell below 50 to another low, extending its decline to the lowest level since the winter. Platinum near 1,492 gave back most of last week’s rebound, and Palladium near 1,000 slipped back to the 1,000 level. Each of the four precious metals remains inside the decline from its late winter peak, and last week’s rebounds produced no higher high. Copper near 6.06 fell for a fifth week, below the lower edge of the range it held through the summer and autumn, putting under pressure the advance that has run since last autumn. For a portfolio maintaining short exposure to the prevailing declines in the precious metals, the week would have recovered much of last week’s cost, subject to position sizing and execution, while Copper’s break would have been a further cost to one following its advance.
Soft Commodities (+0.45% | prev -1.57%)
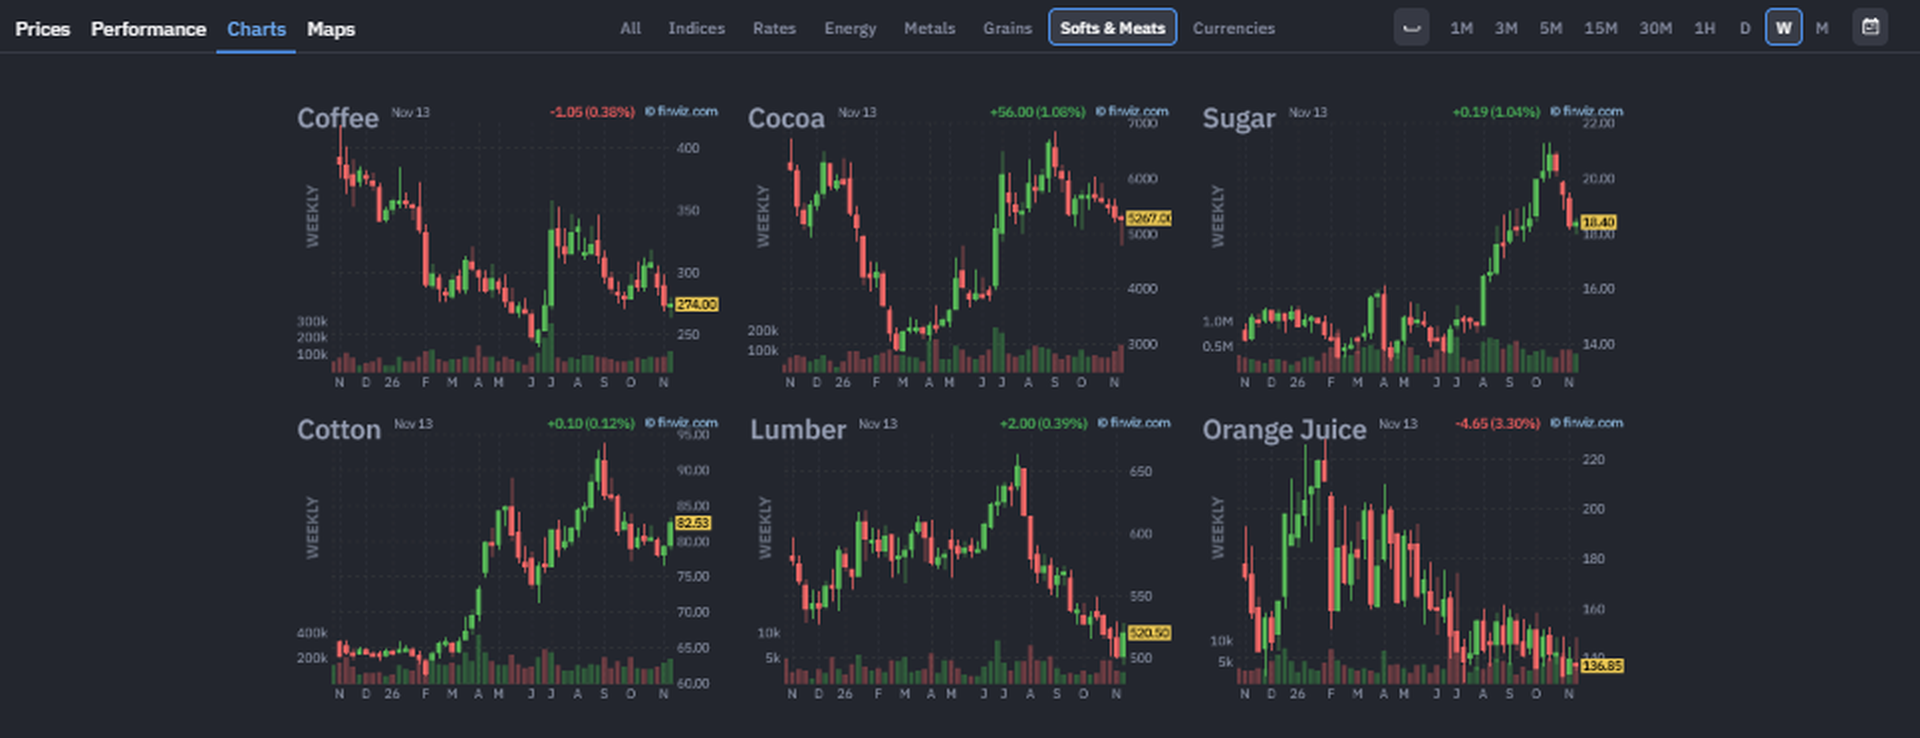
Soft Commodities gained 0.45% with three of six contracts higher, the sector’s first weekly gain in four weeks. Lumber rose 4.00%, the tenth largest move on the board, Sugar 0.93% and Coffee 0.68%, while Cocoa fell 0.13%, Cotton 0.39% and Orange Juice 2.40%. Lumber near 520 rebounded from below 500, a move against the decline that has run since its summer high. Sugar near 18.40 steadied after three weeks of pullback, still well above the area from which its breakout began, and Coffee near 274 lifted slightly inside the decline from its July spike. Cocoa near 5,270 held inside its rebound from the spring, below its September high. Cotton eased below its August high, and Orange Juice near 137 gave back part of last week’s rebound and fell back toward the lowest levels on its chart. Last week Orange Juice’s rebound and Sugar’s third pullback worked against the structures beneath them. This week Orange Juice ran with its decline again, while Lumber’s rebound was a cost to a portfolio positioned with its decline and Sugar’s pause offered little either way.
Grains (+2.88% | prev -2.37%)
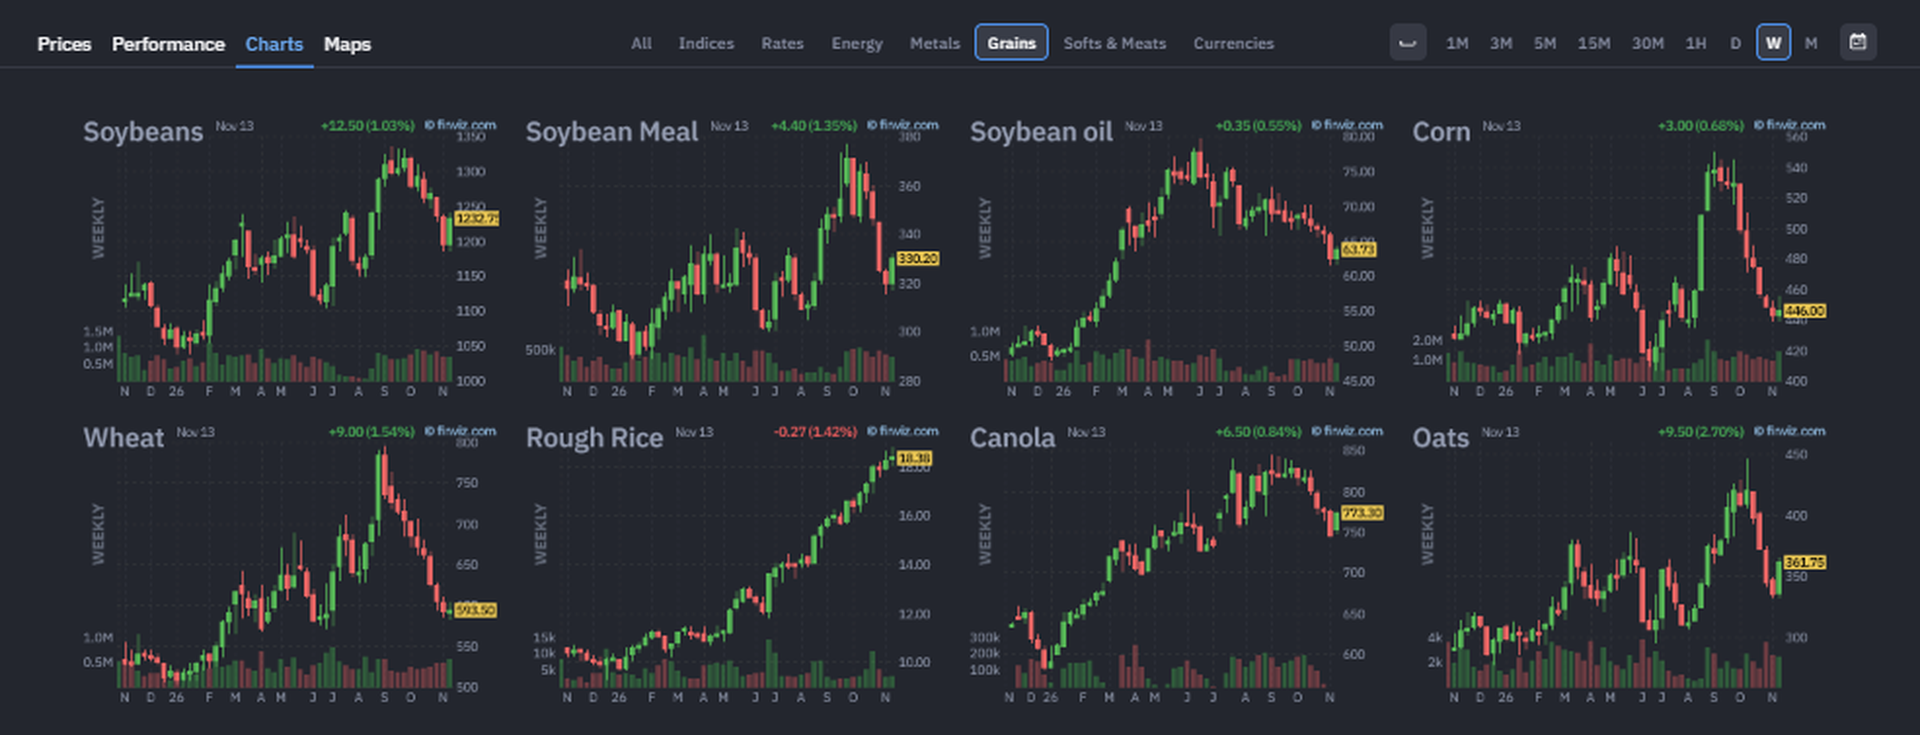
Grains gained 2.88% with all eight contracts higher, ending a run of four weekly declines and finishing as the third strongest sector on the board. Oats rose 8.23%, the largest gain on the board, Canola 3.94%, Soybean Meal 3.32%, Soybeans 3.16%, Soybean Oil 2.43%, Corn 0.91%, Rough Rice 0.74% and Wheat 0.34%. Last week Rough Rice was the only contract to rise. This week all eight did. Oats near 362 rebounded from near 334, recovering part of the four-week pullback from its October high, and Soybean Meal near 330 lifted from just above the area from which its September climb began, the level this report has flagged as the test of its advance. Canola near 773 and Soybeans near 1,233 recovered part of their falls from the top of their charts. Rough Rice near 18.38 edged to another high on a climb that remains steep and intact. Soybean Oil near 63.7 lifted from its lowest level since the spring, a small move inside the decline from its summer peak. Corn near 446 and Wheat near 594 lifted slightly after six and ten weeks of decline, small moves against the declines that remain intact on both charts. Four of the eight moves, Oats, Soybean Meal, Canola and Rough Rice, ran with the advances beneath them, and the test of the advances in Oats and Soybean Meal has, for now, held.
Meats (+4.00% | prev -5.42%)
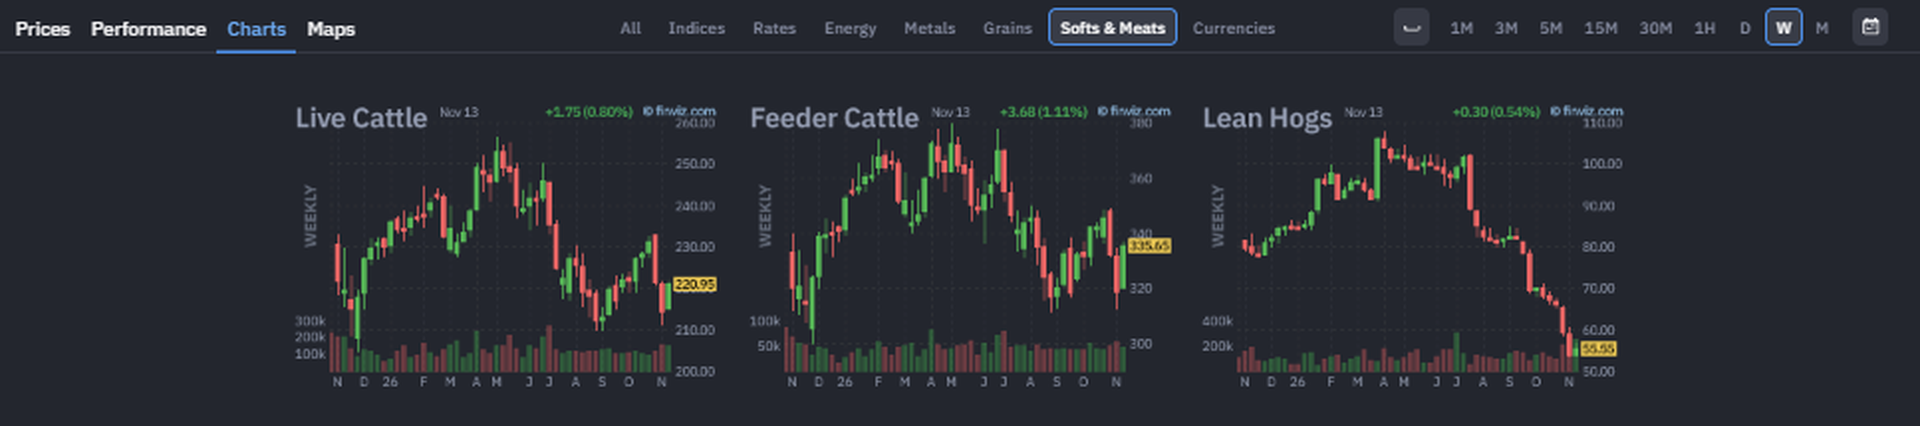
Meats gained 4.00% with all three contracts higher, the strongest sector on the board after two weeks among the weakest. Feeder Cattle rose 5.33%, the seventh largest move on the board, Lean Hogs 3.60% and Live Cattle 3.08%. Feeder Cattle near 336 and Live Cattle near 221 bounced from the lows of their recent falls, and the declines from their spring highs remain intact, with no higher high on either chart. Lean Hogs near 55.6 lifted from the low it set last week, its first weekly gain in six weeks, and remains deep inside the decline from its spring high. For a portfolio carrying short exposure in the sector, all three contracts would have been a cost this week, after two weeks in which every contract ran with its structure.
Bonds (-1.66% | prev +0.40%)
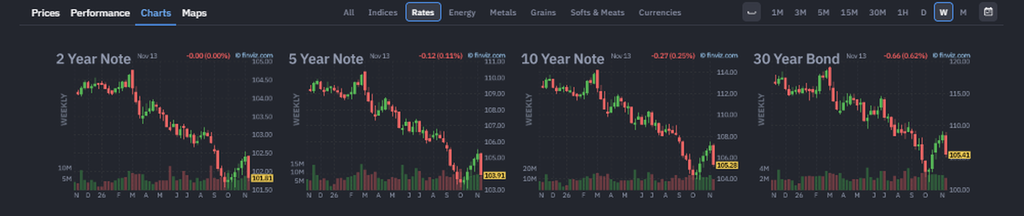
Bonds fell 1.66% with all four contracts lower, ending a run of five weekly gains. The 30 Year Bond fell 2.94%, the 10 Year Note 1.79%, the 5 Year Note 1.30% and the 2 Year Note 0.61%, and the losses grew with maturity, as the gains had in most of the previous five weeks. The 30 Year Bond near 105.41 and the 10 Year Note near 105.28 gave back a large share of their autumn rebounds, and the 5 Year Note near 103.91 and the 2 Year Note near 101.81 fell back toward their lows. For five weeks this report asked whether the bounce would become a higher high. It ended without one, and the declines that have run since the winter peaks remain intact on all four charts. For a portfolio maintaining short exposure across the curve, falling prices would have favoured those positions at every maturity after five weeks of cost, subject to exposure, position sizing and execution. The 30 Year Bond recorded the largest percentage decline, though its actual contribution would depend on the position held.
Currencies (-0.85% | prev -0.74%)
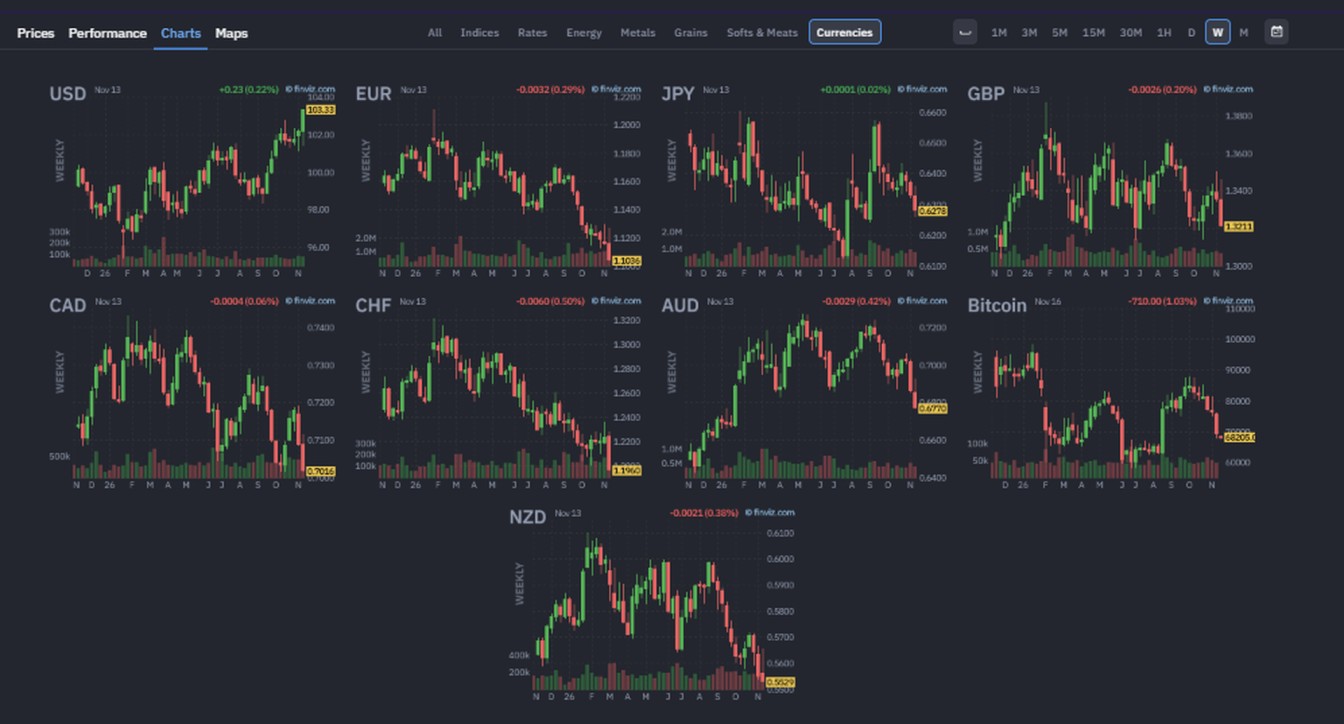
Currencies fell 0.85% with one of eight contracts higher, as the dollar extended its advance and every other contract in the basket fell. The US Dollar Index rose 1.12%, while NZD fell 0.36%, JPY 0.85%, CAD 0.97%, GBP 1.06%, EUR 1.07%, AUD 1.29% and CHF 2.33%. The Dollar Index near 103.33 rose above the range it had held since September to the highest level on its chart. EUR near 1.1036 moved to another low, extending the decline that has run since the summer, CHF near 1.1960 fell below 1.20 to the lowest level on its chart, and NZD near 0.5529 edged to another low. AUD near 0.6770 fell further below 0.70 to the lowest level since the winter, deepening the break in the climb from last year’s lows. CAD near 0.7016 fell back to its summer low near 0.70, GBP near 1.3211 fell to the lower edge of its range, and JPY near 0.6278 eased further inside the decline that has run all year. Last week EUR, NZD and JPY ran with their declines while AUD’s fall cut against its advance. This week the dollar’s breakout ran with its advance, and EUR, CHF, NZD, JPY and CAD ran with their declines, making Currencies, alongside Bonds, one of the two most consistently trend-aligned sectors this week.
Volatility, Crypto: The VIX fell 19.36% to near 19.6, the largest move on the board in either direction, more than reversing last week’s 16.38% rise and falling back below 20, inside the range it broke above a week ago. Market pricing reflected a week in which the equity indices recovered broadly, the dollar strengthened and Bonds fell, though the weekly data does not establish the cause. Bitcoin fell 8.99% to near 68,200, a sixth weekly decline and the second largest move on the board. The rebound from the summer lows near 60,000 has now faded below 70,000, and the decline from above 120,000 remains the dominant feature of its chart.
Top Movers
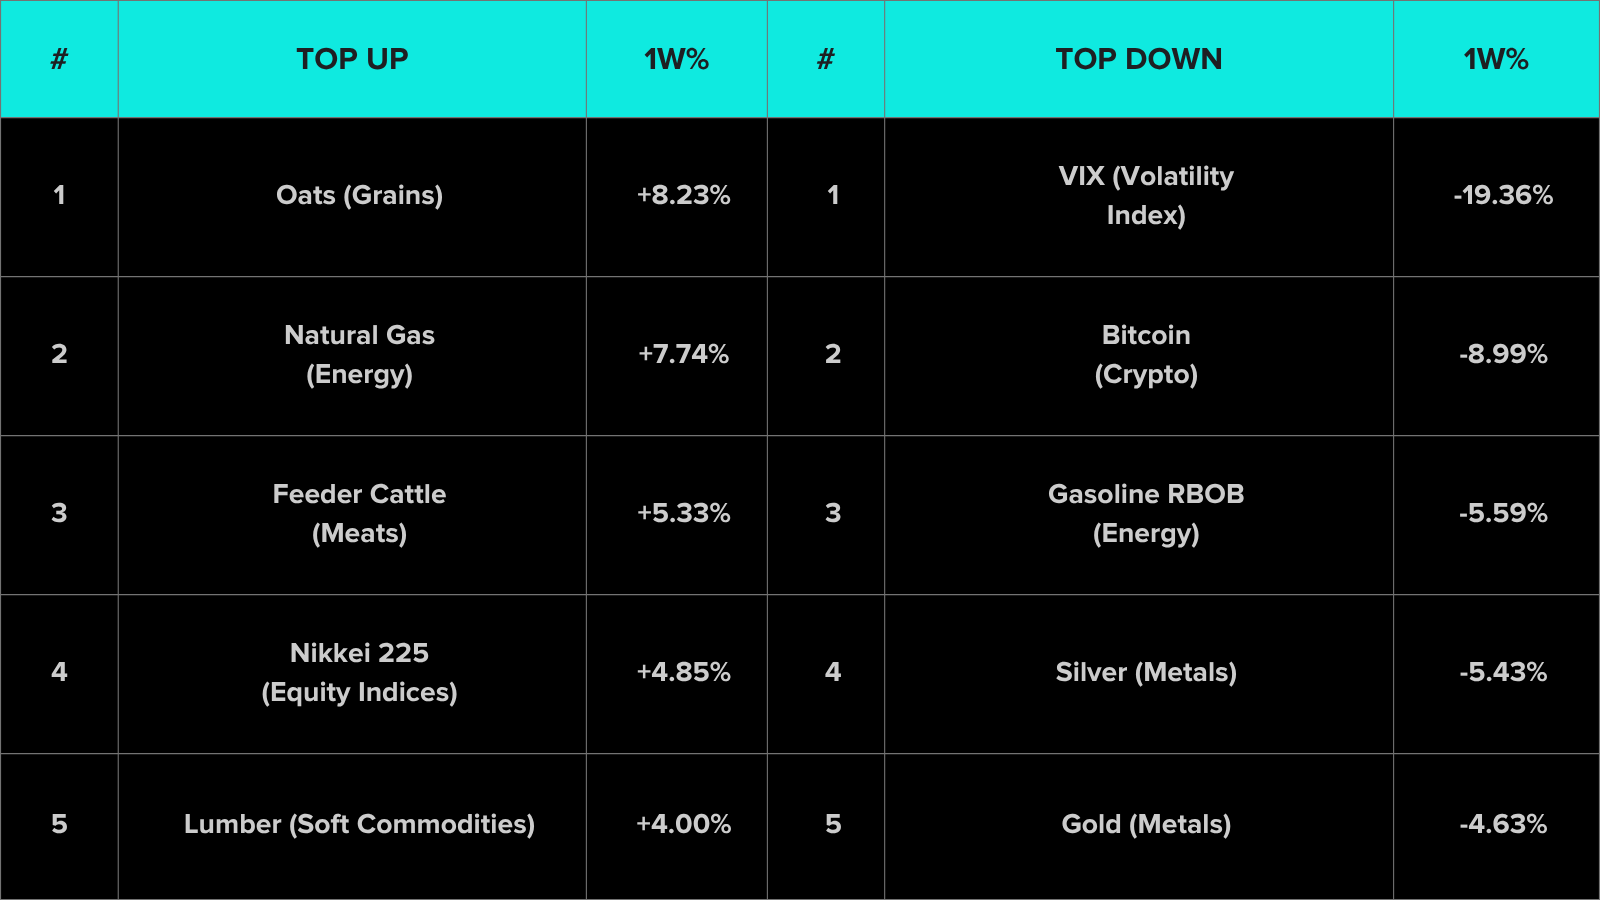
Top five up and top five down by single-week percentage move.
The two halves of the table are uneven again, but this week the imbalance comes from a single contract. The five largest gains range from 8.23% to 4.00%, and the five largest declines from 19.36% to 4.63%. Without the VIX, the largest decline would be Bitcoin’s 8.99%, close to the largest gain. The gainers come from five sectors. Oats resumed its advance, the Nikkei 225 recovered toward its summer range, and Natural Gas, Feeder Cattle and Lumber rose inside their declines. The losers come from four. Bitcoin, Silver and Gold extended their declines, Gasoline RBOB extended last week’s break below its range, and the VIX fell back inside its range. Of the ten entries, six ran with the structures beneath them and three ran against, compared with one of the ten table entries a week ago. The largest moves came more from established structures than from reversals, the reverse of last week’s pattern. That is consistent with the rise in the SG Trend Index, though a sample of ten moves cannot establish the Barometer’s precise reading or account for its 13 point rise.
Portfolio View
For a portfolio positioned with the prevailing trends, the week turned on persistence rather than reversal. The dollar’s breakout, the new lows in EUR, CHF and NZD, the resumed declines in Bonds, Gold and Silver, the fall in Bitcoin and the DAX’s new high would all have favoured positions following the structures beneath them. The Barometer rose to 52%, 3 points below the favourable threshold, and the SG Trend Index added 1.51 percentage points to +11.25% year to date. Rough Rice set another high, and the advances in Oats and Soybean Meal resumed from the levels that had tested them. The bounces in all three Meats contracts, Natural Gas and Lumber would have worked against positions following their declines, as would Copper’s break below its summer range and AUD’s further fall for positions still following their advances. The net result would have depended on each portfolio’s positions, sizing and execution, which a week of prices does not reveal. The week was directional across Currencies, Bonds, the precious metals and the equity indices, with the reversals concentrated in Meats and the smaller agricultural markets.
Final Reflections
After three weeks in which the Barometer and the index moved in opposite directions, this week they rose together, and breadth rose with them. The agreement is as informative as the earlier splits, because each of the three measures still records something the others do not.
The week’s lesson sits in the overlap between how many markets were trending and which way the largest moves ran. The Barometer counts trends; it does not weigh them. This week the count rose sharply and the largest moves ran mostly with established structures, and the index’s recovery is consistent with that combination, though it does not prove it.
1. More markets rose, and more were trending. Breadth and trend strength rose together for a second week, while the size of the moves contracted.
The five-week sequence now reads 36, 41, 36, 39 and 52. The reading sits 3 points below the favourable threshold, back at its 2 October level, and its 10-day rate of change has turned to Rising Moderately. A 13 point rise in a single week is a large change for a measure of trend prevalence, and whether it holds will say more than the size of the jump itself.
2. The return figure rose with the Barometer. The index’s recovery is consistent with established trends persisting across Currencies, Bonds and the precious metals.
For a trend-following portfolio, persistent movement in the direction of its positions creates opportunities for gains, while reversals can impose losses, and the eventual contribution depends on exposure, position sizing and execution. Six of the ten largest moves this week ran with the structures beneath them, against two of the eleven largest a week ago, so the week offered persistence where it mattered most. Without the index’s underlying positions and return contributions, the precise sources of its improvement cannot be established.
This week was a reminder that the direction of a move and its value to a trend follower are separate measurements. Gold fell 4.63%, a move that would have benefited a position aligned with its decline, while Copper fell 2.36%, a move that would have worked against a position following its advance. Oats rose 8.23% and would have benefited a position aligned with its advance, while Feeder Cattle rose 5.33% and would have worked against a position carrying short exposure in its decline. Rising markets are not good markets for a portfolio positioned against them, and falling markets are not bad ones for a portfolio positioned to fall with them. What matters each week is whether a market moved with the structure a portfolio was following.
The week ahead is therefore about whether the Barometer can hold its jump to 52% or push through the 55% threshold into a favourable environment, and whether the 10-day rate of change, now Rising Moderately, holds its turn. Currencies are the sector to follow: the Dollar Index has broken to a new high while EUR, CHF and NZD have set new lows, and whether the dollar’s breakout extends will shape the whole basket. In Bonds, the five-week bounce has ended without a higher high, and the question is whether the declines extend back toward their autumn lows. Gold is back below 4,000, and Copper has broken below its summer range. The DAX has set a new high, while the Nasdaq 100 and the Nikkei 225 remain well below theirs. And the SG Trend Index enters the third week of November at -2.76% for the month. In each case the question is the same one it always is: does the structure persist? For trend followers, up or down was never the central question. Persistence was. The opportunity was directional, but not directionally biased.

List of Resources used in the Week in Review
Important Disclaimers
This document is directly solely to Accredited Investors, Qualified Eligible Participants, Qualified Clients and Qualified Purchasers. No investment decision should be made until prospective investors have read the detailed information in the fund offering documents of any manager mentioned in this document. This document is furnished on a confidential basis only for the use of the recipient and only for discussion purposes and is subject to amendment This document is neither advice nor a recommendation to enter into any transaction. This document is not an offer to buy or sell, nor a solicitation of an offer to buy or sell, any security or other financial instrument. This presentation is based on information obtained from sources that TopTradersUnplugged (“TTU”) (“considers to be reliable however, TTU makes no representation as to, and accepts no responsibility or liability for, the accuracy or completeness of the information. TTU has not independently verified third party manager or benchmark information, does not represent it as accurate, true or complete, makes no warranty, express or implied regarding it and shall not be liable for any losses, damages, costs or expenses relating to its adequacy, accuracy, truth, completeness or use.
All projections, valuations, and statistical analyses are provided to assist the recipient in the evaluation of the matters described herein. Such projections, valuations and analyses may be based on subjective assessments and assumptions and may use one among many alternative methodologies that produce different results accordingly, such projections, valuations and statistical analyses should not be viewed as facts and should not be relied upon as an accurate prediction of future events. There is no guarantee that any targeted performance will be achieved Commodity trading involves substantial risk of loss and may not be suitable for everyone
TTU is not and does not purport to be an advisor as to legal, taxation, accounting, financial or regulatory matters in any jurisdiction. The recipient should independently evaluate and judge the matters referred to herein. TTU does not provide advice or recommendations regarding an investor’s decision to allocate to funds or accounts managed by any manager (“or to maintain or sell investments in funds or accounts managed by any manager, and no fiduciary relationship under ERISA is created by the investor investing in funds or accounts managed by any manager, or through any communication between TTU and the investor
In reviewing this document, it should be understood that the past performance results of any asset class, or any investment or trading program set forth herein, are not necessarily indicative of any future results that may be achieved in connection with any transaction. Any persons subscribing for an investment must be able to bear the risks involved and must meet the suitability requirements relating to such investment. Some or all alternative investment programs discussed herein may not be suitable for certain investors This document is directed only to persons having professional experience in matters relating to investments. Any investment or investment activity to which this document relates is available only to such investment professionals. Persons who do not have professional experience in matters relating to investments should not rely upon this document.
This document and its contents are proprietary information of TTU and may not be reproduced or otherwise disseminated in whole or in part without TTU’s prior written consent.
This document contains simulated or hypothetical performance results that have certain inherent limitations AND SHOULD BE VIEWED FOR ILLUSTRATIVE PURPOSES. Unlike the results shown in an actual performance record, these results do not represent actual trading. HYPOTHETICAL PERFORMANCE RESULTS HAVE MANY INHERENT LIMITATIONS, SOME OF WHICH ARE DESCRIBED BELOW. NO REPRESENTATION IS BEING MADE THAT ANY ACCOUNT WILL OR IS LIKELY TO ACHIEVE PROFITS OR LOSSES SIMILAR TO THOSE SHOWN IN FACT, THERE ARE FREQUENTLY SHARP DIFFERENCES BETWEEN HYPOTHETICAL PERFORMANCE RESULTS AND THE ACTUAL RESULTS SUBSEQUENTLY ACHIEVED BY ANY PARTICULAR INVESTMENT ACCOUNT.
ONE OF THE LIMITATIONS OF HYPOTHETICAL PERFORMANCE RESULTS IS THAT THEY ARE GENERALLY PREPARED WITH THE BENEFIT OF HINDSIGHT IN ADDITION, HYPOTHETICAL TRADING DOES NOT INVOLVE FINANCIAL RISK, AND NO HYPOTHETICAL TRADING RECORD CAN COMPLETELY ACCOUNT FOR THE IMPACT OF FINANCIAL RISK IN ACTUAL TRADING FOR EXAMPLE, THE ABILITY TO WITHSTAND LOSSES OR TO ADHERE TO A PARTICULAR TRADING PROGRAM OR OTHER ASSET.
There are numerous other factors related to the markets in general or to the implementation of any specific trading program which cannot be fully accounted for in the preparation of hypothetical performance results and all of which can adversely affect actual trading results. No representation is being made that any investment will or is likely to achieve profits or losses similar to those being shown.
Most Comprehensive Guide to the Best Investment Books of All Time

Most Comprehensive Guide to the Best Investment Books of All Time
Get the most comprehensive guide to over 600 of the BEST investment books, with insights, and learn from some of the wisest and most accomplished investors in the world. A collection of MUST READ books carefully selected for you. Get it now absolutely FREE!
Get Your FREE Guide HERE!