


Trend Following Performance Report - August, 2026

Persistence Returns
August reversed July's losses. All three trend benchmarks gained between 2.94 and 3.63 percent, and each finished ahead of the S&P 500 Total Return Index, which rose 2.72 percent. The TTU Trend Barometer rose in every week of the month: 34, 39, 50 and 55. July had closed at 30, the low of the 2026 cycle, after five weeks in which the reading changed direction four times. August moved one way only. The Barometer finished 25 points higher, at the 55 boundary that separates Neutral from a favourable trending environment. The weekly path was steady, but the returns it produced were not. Some weeks the environment improved and positions barely moved. In others, a small rise in the reading came with a large gain in the benchmarks.
The ranking of the three benchmarks flipped again. The TTU Trend Following Index led at plus 3.63 percent, followed by BTOP50 at plus 2.95 percent and the SG Trend Index at plus 2.94 percent. Just 69 basis points separated first from third, and one basis point separated second from third. In July the TTU TF Index had finished last, with the broad BTOP50 construction the most defensive of the three. August reversed that ordering. With trends persisting long enough to be carried, the equal-weighted ensemble of long-tenured programs captured the most. The two AUM-based benchmarks finished almost level behind it. Both reversals fit the same logic. The index most exposed to trend persistence gives back the most when trends break and gains the most when they hold.
The Barometer's path shows a trend environment repairing itself one week at a time, although the returns did not rebuild at the same pace. In the first week the reading recovered four points to 34 as breadth jumped from 24 to 34 of 49 contracts higher. Metals rose on every contract, with Silver up 9.89 percent. The equity indices pushed to new highs and Sugar surged 12.21 percent. Yet the SG Trend Index opened August down 0.75 percent, because most of those moves were young and few positions were in place to meet them. The second week lifted the Barometer to 39 and turned its 10-day rate of change positive. Energy snapped back 5.33 percent against the short-side move of the previous fortnight, Grains added 2.66 percent and the equity indices extended for a fourth week. The SG Trend Index moved to plus 0.83 percent month to date on moves that were already established, improving its year-to-date figure by roughly 1.70 percentage points.
The third week produced the Barometer's largest gain of the month, 11 points to 50, as four commodity sectors rallied together and Bitcoin jumped 21.86 percent. Much of that movement ran against existing structure, however, and the SG Trend Index added only 0.32 percentage points to reach plus 1.13 percent. The fourth week reached 55 in the quietest conditions of the month. Breadth narrowed from 31 to 21 of 49 contracts higher. Grains supplied almost all of the movement, rising 5.63 percent with every contract higher and Wheat up 12.12 percent, in the direction their charts had pointed for a fortnight. The SG Trend Index reached plus 1.66 percent at the final weekly close. It then finished the month at plus 2.94 percent, adding a further 1.28 percentage points in the closing session.
The benchmark results for August were as follows:
- TTU Trend Following Index: +3.63 percent for August (trailing 12 months +22.23 percent)
- SG Trend Index: +2.94 percent for August (trailing 12 months +23.04 percent)
- BTOP50 Index: +2.95 percent for August (trailing 12 months +17.96 percent)
- S&P 500 Total Return: +2.72 percent for August (trailing 12 months +20.38 percent)
Trailing twelve-month returns rose across the board, reversing the softening of the prior two months in the pure trend benchmarks. The TTU TF Index moved to 22.23 percent from 21.27 percent, the SG Trend Index to 23.04 percent from 22.80 percent, and BTOP50 to 17.96 percent from 16.01 percent. Year to date, BTOP50 stands at 11.13 percent, the SG Trend Index at 11.07 percent and the TTU TF Index at 9.76 percent, against 13.14 percent for the S&P 500 Total Return Index. BTOP50 and the SG Trend Index are back in double digits for 2026. The TTU TF Index led the month but still trails both on the year by around 135 basis points.
The lesson from August follows from July's. July showed that trend strength and trend persistence are different things. August showed that even when the environment improves steadily, the payoff depends on where the persistence appears. The Barometer rose five points in the second week, 11 in the third and five in the fourth. Those gains came with year-to-date improvements in the SG Trend Index of roughly 1.70, 0.32 and 0.57 percentage points. The largest improvement in the reading produced the smallest return, because its movement arrived in markets a trend book was leaning against. The week with the narrowest breadth was among the more productive, because the one sector moving with force was moving the way positions already pointed. The cycle that began in January remains intact. August closes with the Barometer at 55, the energy decline tested, Grains carrying an established trend and the equity indices still near their highs.
August 2026 Trend Index Performance
August was the first positive month for the trend benchmarks after two consecutive losses, and it recovered more than July had taken. The TTU Trend Following Index gained 3.63 percent, BTOP50 2.95 percent and the SG Trend Index 2.94 percent, against 2.72 percent for the S&P 500 Total Return Index. July had been rough beneath a quiet monthly number. August was more orderly: the Barometer rose in every week, and the SG Trend Index improved its year-to-date figure in each of the last three weeks. The gains did not arrive evenly, though. Most of the month's return came from moves that had already been running for a week or more, while the largest movements on the board repeatedly ran against existing positioning.
August opened with the board turning upward almost everywhere. In the week to 7 August breadth jumped from 24 to 34 of 49 contracts higher. Metals rose 6.52 percent with every contract advancing, led by Silver at 9.89 percent, Palladium at 7.56 percent and Gold at 7.13 percent. The equity indices rose 3.61 percent on all seven contracts, pushing to or close to new highs, and Sugar surged 12.21 percent out of a range it had held since the spring. The Barometer recovered four points to 34. Yet the SG Trend Index began the month down 0.75 percent. Four of the five metals contracts were still inside declines running since February, Sugar's move was a breakout rather than a continuation, and Bonds rallied against two weeks of falling. Energy extended its decline, with WTI down 7.67 percent, which paid positions already short the sector. The only established trend to extend on the long side was in the equity indices.
The second and third weeks told the same story in opposite ways. In the week to 14 August the Barometer rose five points to 39 and its 10-day rate of change turned positive for the first time since the late July collapse. The young moves of the previous week mostly failed their first test. Palladium gave back about half its gain, Sugar added less than one percent and Cocoa reversed. The established moves kept working: the equity indices rose for a fourth week, the VIX fell for a fourth, the Meats fell for a third and Bitcoin resumed its decline. Grains added 2.66 percent with four contracts up more than 4 percent. Energy rose 5.33 percent against the short-side move of the prior fortnight, led by Heating Oil at 9.75 percent. The SG Trend Index moved to plus 0.83 percent month to date, a year-to-date improvement of roughly 1.70 percentage points. The following week the Barometer jumped 11 points to 50, but the index added only 0.32 percentage points to reach plus 1.13 percent. Bitcoin rose 21.86 percent inside a decline in place since January. Platinum, Silver and Gold recovered ground without reclaiming their February highs, and the equity indices fell 1.87 percent on all seven contracts after four weeks of gains. Energy rose a further 4.43 percent, carrying WTI and Brent back beyond the levels where the July decline began. The average move across the board more than doubled while breadth held at 31 of 49, and a large share of that extra movement ran against the positions a trend book was carrying.
The final week reversed that pattern. In the week to 28 August breadth narrowed from 31 to 21 of 49 contracts higher, and the average move fell from 1.97 to 0.43 percent. The counter-trend moves of the previous week simply stopped. Energy fell 1.57 percent as WTI and Brent slipped back inside the July decline, Gold, Silver and Platinum turned lower again, and Bitcoin eased 1.64 percent. Grains supplied almost all of the movement, rising 5.63 percent with every contract higher. Wheat gained 12.12 percent, Oats 9.02 percent and Soybean Meal 6.86 percent, and seven of the eight contracts finished at or near the highs on their charts. This was a third consecutive advance for the sector, in the direction its structure had pointed for a fortnight. The Barometer rose five points to 55 and the SG Trend Index reached plus 1.66 percent. It closed August at plus 2.94 percent after a strong final session on 31 August. The week with the least movement was the week in which trend positions and market direction lined up most closely.
At 31 August 2026, the TTU Trend Following Index contained 52 active programs, up one from 51 in July. This is the first change to the roster since the May reconstitution reduced it from 54, and it takes the index further above the 43 programs represented at the end of 2025. Forty-eight programs had reported by the cut-off, leaving four outstanding, as highlighted in the table below: Finaltis: Cyril Systematic Strategy, Graham Capital Mgmt LP: Proprietary Matrix, Purple Valley Capital: Diversified Trend 1 and Seven Capital Management: Seven Absolute Return Fund. Reporting coverage has improved markedly on July, when nine programs were outstanding at the cut-off. July's return has since been revised to minus 1.98 percent from the provisional minus 1.63 percent as late reporters came in. The August return of 3.63 percent may also change as the remaining four programs report, although with 48 of 52 in, the scope for revision is narrower than it was a month ago. The construction methodology is unchanged and continues to require a fully verified 15-year track record.
August's relationship with equities was co-movement. The S&P 500 Total Return Index rose 2.72 percent, and the trend benchmarks gained between 22 and 91 basis points more. The equity path was far from smooth. The S&P 500 contract gained 3.46 percent in the first week, 0.32 percent in the second, lost 1.46 percent in the third and added 0.40 percent in the fourth. The equity indices remained within the uptrend established since the spring throughout, and long equity exposure was one of the few established trends that paid in the opening week. The long-run correlation between the TTU TF Index and the S&P 500 remains minus 0.09. One month of both rising does not change that structural independence. What August did show was a trend complex drawing its return from a changing set of sources: equities early, established short positions in the middle weeks and Grains at the close.
SG Trend Index
The SG Trend Index is designed to track the 10 largest trend following CTAs of the Managed Futures space.
Criteria for inclusion in the Index, as determined by Société Générale, are as follows:
- Must trade primarily futures (including FX forwards);
- Must be broadly diversified across asset classes;
- Must be an industry recognized trend follower;
- Must exhibit significant correlation to trend following peers;
- Must be open to new investment; and
- Must report returns on a daily basis (net of fees).
The index currently is:
- Equally weighted;
- Calculated in base currency;
- Has an inception date of 1st January 2000;
- Rebalanced annually on 1st January; and
- Reconstituted annually on 1st January based on eligibility criteria.
There was a slight modification to the Index from January 2013 to the present. Previously, the Programs needed to be a constituent of the SG CTA Index, and the 10 largest Managers was not a requirement.
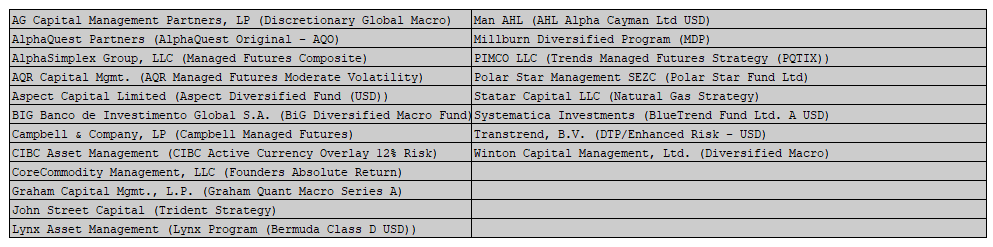
For the 2026 year, following the annual rebalance of the Index, we say goodbye to the Systematica Investments (BlueTrend) Program and welcome back the PIMCO LLC (PIMCO Trends Managed Futures) Program. The listing of the 10 eligible programs in the Index for 2026 is as follows:

The SG Trend Index, which tracks the ten largest institutional trend-following CTAs, gained 2.94 percent in August, ending a run of two consecutive negative months. It finished third among the three trend benchmarks, one basis point behind the BTOP50 at 2.95 percent and 69 basis points behind the TTU Trend Following Index at 3.63 percent. In July it had sat second. The trailing twelve-month return rose to 23.04 percent from 22.80 percent, reversing two months of decline, as the strong monthly result more than offset the August 2025 observation rolling out of the window. The year-to-date figure climbed to 11.07 percent from 7.90 percent. That returns the index to double-digit territory and leaves it six basis points behind the BTOP50 at the head of the field.
The month's shape was the mirror image of July's. July built a gain through four weeks and lost it in one. August opened with a loss and then built steadily through the rest of the month. The index began at minus 0.75 percent in the first week, its year-to-date figure easing to 7.10 percent. The metals, Sugar and a bond rally supplied most of the week's movement, and all three were young moves that few positions were in place to meet. The second week was the turn. The index moved to plus 0.83 percent month to date and 8.80 percent on the year, a gain of roughly 1.70 percentage points, as established moves carried the portfolio. Equities extended, the VIX and the Meats continued lower, Bitcoin resumed its decline and Grains strengthened. The third week added only 0.32 percentage points, taking the index to plus 1.13 percent, even as the Barometer posted its largest gain of the month. Bitcoin, the precious metals and a falling equity complex all moved hard against existing structure. The fourth week brought a further 0.57 percentage points to plus 1.66 percent, carried by Grains rising on every contract in the direction their charts had pointed for a fortnight. The final session on 31 August lifted the index to its closing gain of 2.94 percent and the year-to-date figure back above 11 percent. There was no single decisive week. The index was carried by positions that had been in place long enough to be held through the counter-trend moves around them.
The long-term characteristics of the SG Trend Index improved modestly on the month. Since inception it has delivered a historical CAGR of 5.60 percent with a maximum drawdown of 20.61 percent, reflecting both the durability and the inherent cyclicality of large-scale systematic programs. The CAGR rose from 5.51 percent at the close of July, more than recovering July's decline from 5.57 percent. The maximum drawdown was unchanged for a third consecutive month. These managers benefit most when sustained trends persist in the direction of their positioning, and August supplied enough of that persistence, in enough places, to carry the index back into positive territory.
Since its launch in 2000, the SG Trend Index has maintained its role as a core institutional benchmark for trend-following performance. Over the long run it sits between the higher-returning TTU Trend Following Index and the broader BTOP50 Index, capturing the central tendency of the industry's largest managers. In August it finished at the foot of the monthly ordering, although only a single basis point separated it from the BTOP50. The two AUM-based benchmarks tracked each other closely while the longevity-based TTU construction captured more of the month's persistence. Its high correlation of 0.95 with the TTU TF Index reinforces its usefulness as a barometer of collective institutional behaviour, even as its construction produces more moderated long-run returns relative to smaller or more aggressive trend-following composites.
The performance of the SG Trend Index since 1st January 2000 to the end of last month is seen in the following chart:

You will notice how the SG Trend Index is highly correlated with the BTOP50 Index and the TTU TF Index and uncorrelated with the S&P500TR Index.
Despite the high correlation between the various trend following Indexes, the long-term performance of these three Trend Following Indexes in terms of CAGR is different. The SG Trend Index plots between the BTOP50 Index and the TTU TF Index.
BTOP 50 Index
The BTOP50 Index seeks to replicate the overall composition of the managed futures industry with regards to trading style and overall market exposure. Unlike the SG Trend Index and the TTU TF Index, the BTOP50 is not strictly a trend-following index and is more broadly representative of the entire managed futures segment, of which a dominant style is trend following. We like to think of the BTOP 50 as a ‘quasi trend-following Index’ as opposed to a pure trend-following Index.
Like the SG Trend Index, the BTOP50 Index is designed to track the performance of the largest Programs by AUM, however the Programs included may not be all Trend Following Programs.
The criteria for inclusion in the Index as determined by BarclayHedge are as follows:
- Must be a Program represented in the Barclay CTA Universe;
- In each Calendar year, the Programs selected must in aggregate be no less than 50% of the investable assets of the Barclay CTA Universe;
- The Programs must be open for investment;
- The Manager must be willing to provide Barclay Hedge with daily return performance;
- The Program must have at least two years of trading activity; and
- The Program’s advisor must have at least three years of operating history.
The index currently is:
- Equally weighted;
- Rebalanced annually on 1st January
- Reconstituted annually on 1st January based on eligibility criteria.
Despite the '50' tag in the BTOP 50 description, the 2026 constituent listing has not yet been released by BarclayHedge at the time of this report. The 2025 listing of 20 constituents remains the most recent available reference.
The BTOP50 Index gained 2.95 percent in August, ending a run of two consecutive negative months. It finished second among the three trend benchmarks, one basis point ahead of the SG Trend Index and 68 basis points behind the TTU Trend Following Index. In July it had led the field. Over the trailing twelve months the index now stands at 17.96 percent, up from 16.01 percent in July, a second consecutive rise as a weaker August 2025 comparative rolled out of the window. The year-to-date figure climbed to 11.13 percent from 7.87 percent. That places the broad managed futures composite, which had trailed both pure trend benchmarks for most of the year, at the head of the field on a year-to-date basis. It sits six basis points ahead of the SG Trend Index and 137 basis points ahead of the TTU TF Index.
Trend followers already understand this principle at the market and system level. Broader diversification reduces dependence on any single market, signal or path. The TTU TF Index extends the same logic across managers. Instead of relying on one implementation of trend following, it combines many long-lived implementations into a single ensemble.
The long-term profile of the BTOP50 improved on the month. Since inception it has produced a historical CAGR of 4.40 percent with a maximum drawdown of 15.94 percent, reinforcing its reputation for stability and drawdown moderation. The CAGR rose from 4.30 percent at the close of July, as a monthly gain well above the long-term compounding rate lifted the figure. The maximum drawdown was unchanged for a third consecutive month.
August showed the other side of the trade-off that July had illustrated. In July the BTOP50's broad construction worked as protection. The index committed less to the trends that broke and so gave back less. In August the trends that had been in place long enough to be carried delivered, and the same broad construction captured less of them than the TTU TF Index did. The BTOP50 still matched the SG Trend Index almost exactly. Its narrow year-to-date lead over the SG Trend Index rests on a single basis point in August, the two having finished July almost level, while its lead over the TTU TF Index was built largely in July. Across the two months, the index lost least when persistence failed and gained less than the longevity-based ensemble when persistence returned. That is the structural profile of a broad managed futures composite, and it is consistent with the lowest long-run return of the three.
The index's high correlation of 0.96 with the SG Trend Index and 0.93 with the TTU TF Index confirms that its performance remains closely aligned with its trend-following peers, even as its broader mandate produces more moderated long-term returns. The correlation of minus 0.10 with the S&P 500 Total Return Index remains an important structural feature of the index over the long run. In August the BTOP50 and the S&P 500 rose together, the equity index by 2.72 percent and the BTOP50 by 23 basis points more. After July's unrelated movements, August's co-movement is a reminder that a correlation near zero describes the long-run relationship, and any single month can show the two moving together, apart or independently.
The performance of the BTOP 50 Index since 1st January 2000 to the end of last month is seen in the following chart:

The BTOP 50 Index is highly correlated with the trend following Indexes of the SG Trend Index and the TTU TF Index, however its long-term performance is the lowest of the 3 Trend Following Indexes. While there is a significant representation of Trend Following Programs within the Index, the non-trend following Programs contribute to this diluted long-term performance.
TTU TF Index
The TTU TF Index has been developed by Top Traders Unplugged to provide a performance measure of the trend-following programs with a long-term track record.
At TTU, we recognize the importance of a robust trading approach to these uncertain markets and feel that AUM is not a good robustness measure when it comes to assessing performance of the trend-following industry. It is our strong opinion that the ultimate selection measure to apply in constituting a Trend Following Index is not AUM or a proxy risk metric such as the Sharpe, Sortino, MAR ratio, Ulcer Index or Serenity ratio. The superior metric to assess long-term performance is the long-term validated track record itself.
We have therefore developed a different method for constructing our TTU TF Index.
The criteria for inclusion into the TTU TF Index are as follows:
- Monthly performance results need to be captured in the Nilsson Hedge CTA database;
- Must be geographically diversified across asset classes;
- Must be fully systematic in nature using quantitative rules for entry and exit;
- Must possess at least a 15-year unbroken track record to the current reporting month;
- Must adopt trend following as their dominant investment strategy;
- Are currently active programs; and
- Must report performance monthly (net of fees).
The Index:
- Is Equally weighted;
- Is Rebalanced monthly;
- Is Reconstituted monthly;
- Has an inception date of 1st January 2000
As of 31 August 2026, the TTU Trend Following Index is composed of 52 active programs, each with a long-term, fully verified performance record. The roster has risen by one from 51 at the close of July, its first increase since the reconstitution that trimmed it from 54 in May. That reconstitution interrupted a steady expansion from 43 programs at the close of 2025 through 47 in January, 49 in February, 51 in April and 54 in May. The count then held at 51 through June and July before this month's addition. The construction methodology is unchanged, continuing to require a fully verified 15-year track record. The composite retains the broad, long-tenured cross-section of systematic trend-following behaviour that defines it, with nine more programs than it carried at the close of 2025. The monthly index return reflects the equal-weighted average performance of all programs reporting for the period.
For August, 48 of the 52 programs submitted performance data by the reporting cut-off, with four programs yet to report as highlighted in the table below. This is a substantial improvement on July, when 42 of 51 programs had reported and nine were outstanding. It is close to the 49 recorded in each of May and June. With four programs outstanding against nine a month earlier, the August equal-weighted return is drawn from a considerably broader base than July's. It may still be revised as the remaining programs report.

The performance of the TTU TF Index from 1st January 2000 to the end of last month is as follows:

Now you might be intrigued by the performance result of the TTU TF Index. While it is highly correlated with the BTOP 50 Index and the SG Trend Index, we can see that long term performance of the TTU TF Index clearly outstrips alternative Index measures.
The dominant contributor of this outperformance is the requirement for any participating Program in the Index to have a long-term track record. You see, using AUM as a criterion for inclusion is not necessarily a useful selection criterion. While AUM reflects 'market appeal', it does not imply that this 'market appeal' is strongly correlated with 'long term performance'.
Our process of Index construction gives us an insight into how any diversified ensemble of trend following Programs with a long-term track record approaches an optimal portfolio as we increase the number of Programs in the Index. Simply by diversifying into a large ensemble of Trend Following Programs with a long-term track record, we magically improve the Index result. CAGR is increased and our drawdowns are reduced.
Of course, we already know this 'diversification' principle of Trend Following. As we increase our diversification efforts, we obtain improvement both in terms of the maximum drawdown and in the CAGR generated by the ensemble. This is why we seek to strive for maximum market and system diversification within our individual programs. The TTU TF Index just takes this diversification one step further and diversifies across many different TF Programs to deliver a stronger return and drawdown profile.
TTU TF Index Performance
The TTU Trend Following Index, composed exclusively of long-tenured systematic trend programs, gained 3.63 percent in August, ending a run of two consecutive negative months. It was the strongest of the three trend benchmarks for the month, 68 basis points ahead of the BTOP50 at 2.95 percent and 69 ahead of the SG Trend Index at 2.94 percent. That reverses July, when it had finished third. Over the trailing twelve months the index stands at 22.23 percent, up from 21.27 percent in July, as the August 2026 gain replaced a smaller August 2025 gain of 2.19 percent in the rolling window. July's return has been revised to minus 1.98 percent from the provisional minus 1.63 percent, which lowers the year-to-date figure through July to 5.92 percent from the published 6.62 percent. From that revised base the year-to-date figure rose to 9.76 percent. The index leads the month but still trails the BTOP50 at 11.13 percent and the SG Trend Index at 11.07 percent on the year.
August's gain came from a month that rewarded trends held long enough to be carried. The TTU Trend Barometer rose in every week, tracing 34, 39, 50 and 55 from July's closing reading of 30. The returns did not follow the environment reading in proportion. The strongest improvement in realised trend performance came in the second week, as established moves extended. Equities rose for a fourth week, the VIX and the Meats continued lower, Bitcoin resumed its decline and Grains strengthened. The third week produced the Barometer's largest gain, but much of that week's movement ran against existing structure, with Bitcoin up 21.86 percent inside its decline, the precious metals recovering ground and the equity indices falling on all seven contracts. The final week narrowed to 21 of 49 contracts higher, and Grains rose on every contract in the direction their charts had pointed for a fortnight. In July the composite's full commitment to trend following had made it the benchmark most exposed to the trends that broke. In August the same commitment made it the benchmark best placed to capture the trends that held.
The long-term profile of the TTU TF Index improved on the month. Since its inception in 2000, the index has delivered a CAGR of 7.62 percent with a maximum drawdown of 20.72 percent. The CAGR rose from 7.53 percent at the close of July, as a monthly gain well above the long-term compounding rate lifted the figure. The maximum drawdown was unchanged for a third consecutive month. On the revised monthly figures, June and July together cost the index 3.78 percent, and August's gain recovered all but about 0.3 percent of that. These characteristics continue to reflect the strength of the construction methodology, which prioritises the durability of verified track records over scale, popularity, or short-term risk statistics.
The TTU TF Index remains closely aligned with the institutional trend benchmarks, with correlations of 0.95 to the SG Trend Index and 0.93 to BTOP50. The important difference is in the long-run outcome. Its track-record-based construction has produced the strongest compound return of the three while retaining the broad behavioural signature of systematic trend following. The roster now stands at 52 programs, nine more than at the end of 2025, with 48 reporting for August. In July, that breadth offered little shelter because many long-tenured programs were exposed to the same reversals in the closing week. In August the shared exposure worked in the composite's favour, as the persistent trends were ones many of those programs already held. Across the two months, the index moved from the weakest to the strongest of the three benchmarks. The 22.23 percent trailing twelve-month return remains the more useful context for either result.
For comparison, the S&P 500 Total Return Index gained 2.72 percent in August and returned 20.38 percent over the trailing twelve months. Since 2000 it has compounded at 8.27 percent, but its maximum drawdown of 50.95 percent is far deeper than that of the trend benchmarks. June saw equities and the TTU TF Index fall together, July saw equities finish almost unchanged while trend following eased, and August saw both rise, with the TTU TF Index ahead by 91 basis points. None of these observations changes the structural point. The long-run correlation between the two indices is minus 0.09. Their return engines are different, and that independence is the reason trend following can play such a useful role inside a broader portfolio.

TTU Trend Barometer
The TTU Trend Barometer closed August at 55, at the boundary where Neutral gives way to a favourable regime and 25 points above July's closing reading of 30. The path matters as much as the destination. July oscillated across a 34-point range, changing direction four times in five weeks. August rose in every week: four points, then five, then 11, then five. The reading recovered the entire 22 points lost in the final week of July and finished three points above the 52 that preceded that collapse.
The Barometer, which measures the persistence of price trends across 44 global futures markets, began August at 30, ten points below the Neutral floor. The first week lifted it four points to 34 as the board turned upward almost everywhere. Contract-level breadth jumped from 24 to 34 of 49 contracts higher. The metals rose on all five contracts, with Silver up 9.89 percent, and the equity indices advanced on all seven to or near new highs. Sugar surged 12.21 percent out of a range it had held since the spring. The recovery was modest against the size of the advance, because most of the week's movement came in markets that were only beginning to move. Four of the five metals contracts remained inside declines running since February. The Grains stopped falling without starting anything, with no contract moving more than 3 percent, and Orange Juice undid the bounce it had made a week earlier. The 10-day rate of change eased to "Falling Moderately" from "Falling Rapidly."
The second week added five points to 39, one point below the Neutral floor. The 10-day rate of change turned to "Rising Weakly," its first positive reading since the late July collapse. Breadth narrowed to 31 of 49 contracts higher, yet the reading rose, because the moves that continued were the ones already established. The equity indices extended for a fourth week, the VIX fell for a fourth, the Meats fell for a third and Bitcoin resumed its decline. Grains added 2.66 percent with four contracts up more than 4 percent. The young moves of the previous week mostly failed their first test. Palladium gave back about half its gain, Sugar added less than one percent and Cocoa reversed. Energy surged 5.33 percent on every contract, a sharp reversal of the fortnight's decline rather than the continuation of a trend.
The third and fourth weeks carried the reading through the Neutral band to its upper boundary. The week to 21 August produced the largest gain of the month, 11 points to 50, with the rate of change accelerating to "Rising Moderately." Breadth was unchanged at 31 of 49, but the average move across the board more than doubled, from 0.80 to 1.97 percent. Four commodity sectors rallied together, Energy rose for a second consecutive week on all six contracts, and Bitcoin jumped 21.86 percent. The equity indices fell on all seven contracts after four weeks of gains. The week to 28 August added five points to 55 in the quietest conditions of the month. Breadth narrowed sharply to 21 of 49, and the average move fell to 0.43 percent. The counter-trend moves of the previous week stopped: Energy slipped back inside the July decline, and Gold, Silver and Platinum turned lower again. Grains rose 5.63 percent on all eight contracts, with Wheat up 12.12 percent and seven contracts at or near the highs on their charts. The rate of change slowed to "Rising Weakly" but remained positive for a third consecutive week.
Read as a sequence, 34, 39, 50 and 55 is the opposite of July. Each week built on the one before, and the reading moved in one direction throughout. Breadth moved the other way, from 34 to 31, 31 and then 21 contracts higher. The Barometer measures how decisively markets are trending, not how many are rising, and August's reading strengthened as participation narrowed. The month again showed that the Barometer and realised CTA returns are related but not interchangeable. The five-point rise in the second week accompanied the largest improvement in the SG Trend Index's year-to-date figure, roughly 1.70 percentage points. The 11-point rise in the third week accompanied an improvement of only 0.32 percentage points, because much of that week's movement ran against positions already held. The Barometer does not know whether a portfolio is positioned in the trends it counts. In August, the weeks in which the persistent moves were ones trend followers already held were the weeks that paid.
The Barometer enters September at 55, 15 points above the Neutral floor and at the favourable boundary, with its 10-day rate of change at "Rising Weakly." Level and momentum both point upward, although the pace of improvement slowed in the final week. The cleaner structures are in the equity indices, which remain near their highs with the DAX at the highest level on its chart, and in Grains, where seven of eight contracts are pressing chart highs. The Meats have now declined for five consecutive weeks and the VIX for six. The picture elsewhere is less settled. Crude's two-week rebound failed to extend and left WTI and Brent back inside the July decline. The precious metals turned lower again below their February highs, the dollar rose 0.94 percent in the final week after falling through much of the month, and Bitcoin remains inside the decline in place since January.

The Trend Barometer is a proprietary tool we use at TTU to assess the trend strength of a diversified portfolio consisting of 44 markets across all sectors. We firstly subdivide the trend strength of each market of a hypothetical diverse portfolio into five ranges from strong up, medium up, neutral, medium down and strong down. We then aggregate these results into a single portfolio number which we use to describe the overall trend strength across a hypothetical Program portfolio.
We then arbitrarily divide this percentage range into 3 where a value of 0-30 is considered a very unfavourable market regime for trend following programs, a range between 30 to 55 is a somewhat neutral environment for Trend Following Programs (but not an environment where you could expect consistent performance) and values more than 55 are considered to be a favourable regime for trend following programs, where they should see good performance.
Aside from the occasional dispersed readings when compared to overall trend following performance, this method is surprisingly powerful in describing CTA monthly performance and can be used to connect market trading environments to resultant manager performance.
The Macro Environment
For a blow-by-blow macro wrap for the month, we recommend you listen to our weekly systematic investor series by clicking on the links below. It is also worthwhile listening to our past catalogue, as it provides you with an understanding of how these markets can shape the emotions of a trader and why it is therefore essential that trend followers adopt systematic rules-based processes to keep these emotions in check.
You can find all of our weekly conversations by clicking this link.
Top 10 Lists
We have prepared the following Top 10 lists (excluding non-reporting programs) for various performance categories based on monthly performance returns for a 15-year period commencing 1st January 2011 to the current month.
Top 10 Listing – by Compound Annual Growth Rate


Top 10 Listing – by Risk Adjusted Return (Serenity Ratio)


Top 10 Listing – by Last 12 months Performance


Performance Results for the TTU Top 5 by Serenity Ratio
In a research project we undertook at TTU, we examined three different allocation methods that could be deployed by an investor seeking to optimally allocate investment funds towards 5 of the top-ranked Globally Diversified Systematic Trend Following Programs with a long-term track record.
These three methods adopted 3 different forms of performance metric, namely:
- Top 5 performers by Compound Annual Growth Rate (CAGR) using a rolling lookback of 15 years.
- Top 5 performers by MAR ratio (CAGR/Max Draw%) using a rolling lookback of 15 years.
- Top 5 performers by Serenity Ratio using a rolling lookback of 15 years.
The findings of our project can be obtained by clicking on this link.
Our research determined that the optimal selection method was the Serenity Ratio method.
The Serenity Top 5 Selection Method gained 5.62 percent in August, ending a run of three consecutive negative months. It was the strongest result among the trend composites covered in this report, 199 basis points ahead of the TTU TF Index at 3.63 percent and well clear of the BTOP50 at 2.95 percent and the SG Trend Index at 2.94 percent. In July the concentrated composite had finished inside the range of the broad trend benchmarks for the first time in three months. In August it finished well outside that range again, this time on the upside. The trailing twelve-month return rose to 40.19 percent from 38.00 percent, and the year-to-date result climbed to 20.18 percent. Man AHL's AHL Dimension reported for August, so this month's composite is struck on all five constituents.
August suited a concentrated trend portfolio better than any of the three preceding months. The Barometer rose in every week, from 30 at the close of July to 55. The moves that paid were ones that persisted beyond their first week. The equity indices extended an uptrend in place since the spring, the VIX and the Meats continued lower, and Grains rose for three consecutive weeks, finishing the month with seven of eight contracts at or near the highs on their charts. A concentrated composite has less breadth to dilute its exposure than the 52-program TTU index, so it gains more when established trends extend and gives back more when they break. June showed the second of those cases, with a loss of 4.27 percent. August showed the first. The counter-trend moves of the third week, in Bitcoin, the precious metals and the equity indices, were a cost, but they did not persist into the final week.
The 2026 Serenity selection retains the same five programs as 2025, with the revised ranking applying from 1 February 2026 to 31 January 2027. That continuity reflects the durability of the managers across the full 15-year evaluation window. Mulvaney Capital Management's Global Diversified Program remains the largest source of variation within the group. Its high-convexity profile responds to persistent, expanding trends rather than to any preferred direction, which means it can amplify both gains and give-backs. A month in which trends held for several consecutive weeks is the environment that profile is designed to exploit. That variability is part of the asymmetry the selection is designed to retain.
The Serenity Ratio remains useful because it rewards durability, compounding and drawdown control across a long evaluation window rather than chasing recent returns. Across the full reporting history of 26.68 years, the Serenity composite has produced a CAGR of 5.79 percent with a maximum drawdown of 26.82 percent and a Serenity Ratio of 0.47. Its correlation is minus 0.02 to the S&P 500 Total Return Index and 0.81 to the TTU TF Index. The CAGR rose from 5.59 percent in July, while the historical maximum drawdown was unchanged. August added a fourth version of the diversification relationship in four months: opposite directions in May, both negative in June, trend following down modestly against an almost flat equity market in July, and both rising in August, with the composite 290 basis points ahead of the S&P 500. The long-run near-zero equity correlation describes the relationship, and any single month can show any of these combinations.

The 2026 Serenity selection is as follows and will be maintained for the investment period between 1st February 2026 to 31st January 2027:
- Man AHL: AHL Evolution;
- Man AHL: AHL Alpha;
- Quantica Capital AG: Managed Futures Program;
- Mulvaney Capital Management: Global Diversified Program; and
- Man AHL: AHL Dimension.
Individual Performance Results for the 5 Programs used for the Serenity allocation to the reporting month using the 2026 listing are as follows:


Performance Results for the Alternative 60/40 portfolio using the TTU Top 5 by Serenity Ratio
In our “How to Invest with the Best”blog post, we also highlighted the significant improved risk-adjusted performance results that could be achieved by replacing the 40% allocation to Bonds in the traditional 60/40 portfolio with an allocation of 40% towards the TTU Top 5 by Serenity ratio.
The evaluation compared the performance of a traditional 60% Equity/40% Bond portfolio against a 60% Equity/40% Serenity portfolio to highlight the uncorrelated historical nature of this Alternative 60/40 portfolio and demonstrate the benefits that a sizeable allocation towards the Serenity portfolio would bring to an investor if equity and bond markets go back to their historic relationship and become more positively correlated in the future. There is no guarantee that correlations remain static over time and it is possible that bond markets and equity markets may lose their uncorrelated relationship that has existed in the last 20 years or so. It is far less likely that the TF managers within the Serenity Grouping will ever be strongly positively correlated to the Equities market, over the long run, given the extensive global diversification and ability to go long and short, that is present within the constituents of the Serenity Grouping.
Chart 21 below showcases the comparative performance results for the period 1 January 2000 to the end of last month:
- A 100% investment in the S&P500TR portfolio;
- A 100% investment in the VBMFX which is a proxy for the bond market;
- A 100% investment in the VBIAX which is a suitable proxy for the classic 60% Equity/40% Bond portfolio;
- A 100% investment in a 60% S&P500TR 40% Serenity portfolio; and
- A 100% investment in the Serenity Portfolio.

The comparison of alternative portfolio allocations above highlights the strong historic risk adjusted returns that have been enjoyed by 60% S&P500TR / 40% Serenity Composite Portfolio.
A more detailed assessment of this powerful 60/40 investment option is reflected below.

Important Disclaimers
This document is directly solely to Accredited Investors, Qualified Eligible Participants, Qualified Clients and Qualified Purchasers. No investment decision should be made until prospective investors have read the detailed information in the fund offering documents of any manager mentioned in this document. This document is furnished on a confidential basis only for the use of the recipient and only for discussion purposes and is subject to amendment This document is neither advice nor a recommendation to enter into any transaction. This document is not an offer to buy or sell, nor a solicitation of an offer to buy or sell, any security or other financial instrument. This presentation is based on information obtained from sources that TopTradersUnplugged (“TTU”) (“considers to be reliable however, TTU makes no representation as to, and accepts no responsibility or liability for, the accuracy or completeness of the information. TTU has not independently verified third party manager or benchmark information, does not represent it as accurate, true or complete, makes no warranty, express or implied regarding it and shall not be liable for any losses, damages, costs or expenses relating to its adequacy, accuracy, truth, completeness or use.
All projections, valuations, and statistical analyses are provided to assist the recipient in the evaluation of the matters described herein. Such projections, valuations and analyses may be based on subjective assessments and assumptions and may use one among many alternative methodologies that produce different results accordingly, such projections, valuations and statistical analyses should not be viewed as facts and should not be relied upon as an accurate prediction of future events. There is no guarantee that any targeted performance will be achieved Commodity trading involves substantial risk of loss and may not be suitable for everyone
TTU is not and does not purport to be an advisor as to legal, taxation, accounting, financial or regulatory matters in any jurisdiction. The recipient should independently evaluate and judge the matters referred to herein. TTU does not provide advice or recommendations regarding an investor’s decision to allocate to funds or accounts managed by any manager (“or to maintain or sell investments in funds or accounts managed by any manager, and no fiduciary relationship under ERISA is created by the investor investing in funds or accounts managed by any manager, or through any communication between TTU and the investor
In reviewing this document, it should be understood that the past performance results of any asset class, or any investment or trading program set forth herein, are not necessarily indicative of any future results that may be achieved in connection with any transaction. Any persons subscribing for an investment must be able to bear the risks involved and must meet the suitability requirements relating to such investment. Some or all alternative investment programs discussed herein may not be suitable for certain investors This document is directed only to persons having professional experience in matters relating to investments. Any investment or investment activity to which this document relates is available only to such investment professionals. Persons who do not have professional experience in matters relating to investments should not rely upon this document.
This document and its contents are proprietary information of TTU and may not be reproduced or otherwise disseminated in whole or in part without TTU’s prior written consent.
This document contains simulated or hypothetical performance results that have certain inherent limitations AND SHOULD BE VIEWED FOR ILLUSTRATIVE PURPOSES. Unlike the results shown in an actual performance record, these results do not represent actual trading. HYPOTHETICAL PERFORMANCE RESULTS HAVE MANY INHERENT LIMITATIONS, SOME OF WHICH ARE DESCRIBED BELOW. NO REPRESENTATION IS BEING MADE THAT ANY ACCOUNT WILL OR IS LIKELY TO ACHIEVE PROFITS OR LOSSES SIMILAR TO THOSE SHOWN IN FACT, THERE ARE FREQUENTLY SHARP DIFFERENCES BETWEEN HYPOTHETICAL PERFORMANCE RESULTS AND THE ACTUAL RESULTS SUBSEQUENTLY ACHIEVED BY ANY PARTICULAR INVESTMENT ACCOUNT.
ONE OF THE LIMITATIONS OF HYPOTHETICAL PERFORMANCE RESULTS IS THAT THEY ARE GENERALLY PREPARED WITH THE BENEFIT OF HINDSIGHT IN ADDITION, HYPOTHETICAL TRADING DOES NOT INVOLVE FINANCIAL RISK, AND NO HYPOTHETICAL TRADING RECORD CAN COMPLETELY ACCOUNT FOR THE IMPACT OF FINANCIAL RISK IN ACTUAL TRADING FOR EXAMPLE, THE ABILITY TO WITHSTAND LOSSES OR TO ADHERE TO A PARTICULAR TRADING PROGRAM OR OTHER ASSET.
There are numerous other factors related to the markets in general or to the implementation of any specific trading program which cannot be fully accounted for in the preparation of hypothetical performance results and all of which can adversely affect actual trading results. No representation is being made that any investment will or is likely to achieve profits or losses similar to those being shown.
Most Comprehensive Guide to the Best Investment Books of All Time

Most Comprehensive Guide to the Best Investment Books of All Time
Get the most comprehensive guide to over 600 of the BEST investment books, with insights, and learn from some of the wisest and most accomplished investors in the world. A collection of MUST READ books carefully selected for you. Get it now absolutely FREE!
Get Your FREE Guide HERE!